China's Heavy-Duty Gas Turbine Industry 2026: Where AI's Power Hunger Meets a 25-Year March to Self-Reliance
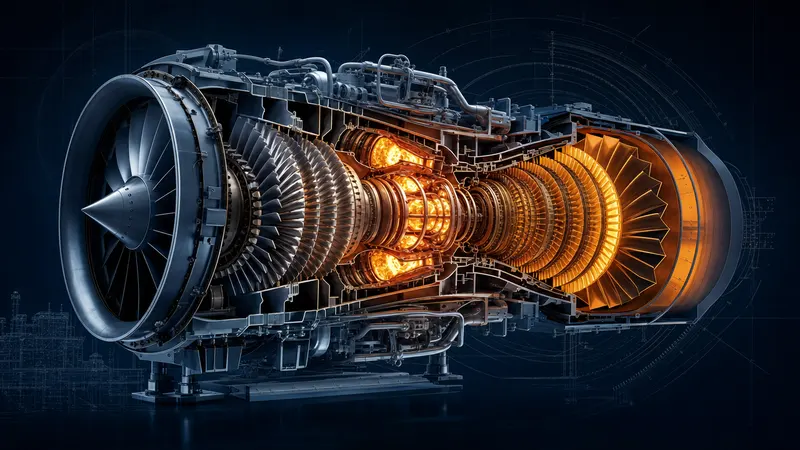
AI data centers have pushed global gas turbine order books beyond 2030, with the Big Three sold out and prices roughly tripling in three years. At precisely this moment, China's homegrown heavy-duty gas turbines completed three critical steps: G50 commercial operation, 300 MW first fire, and export to North America. This 33-chapter report dissects the historic convergence, from hot-section technology and capacity pricing to the export window and its risks.
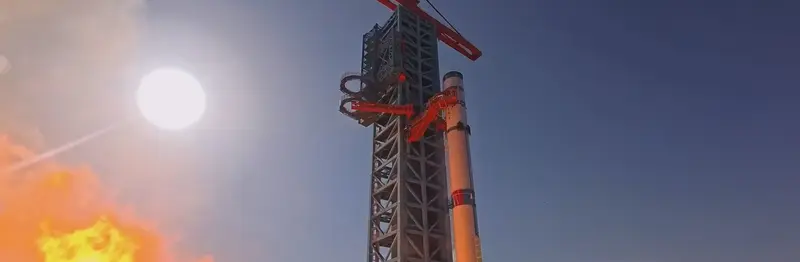
Catching Itself: Zhuque-3 and the Industrial Chain Behind China's Private Reusable Rockets
In late 2025 Zhuque-3's maiden flight reached orbit but its first-stage recovery failed; the static-fired Y2 now aims for China's first orbital-class first-stage recovery by a private firm. Tracing the rocket from methalox Tianque engines and a stainless-steel airframe to landing control, reuse economics, constellation launch demand, China's two recovery routes and a supply chain opening to Chinese factories, this report argues reusability is at heart a manufacturing question.
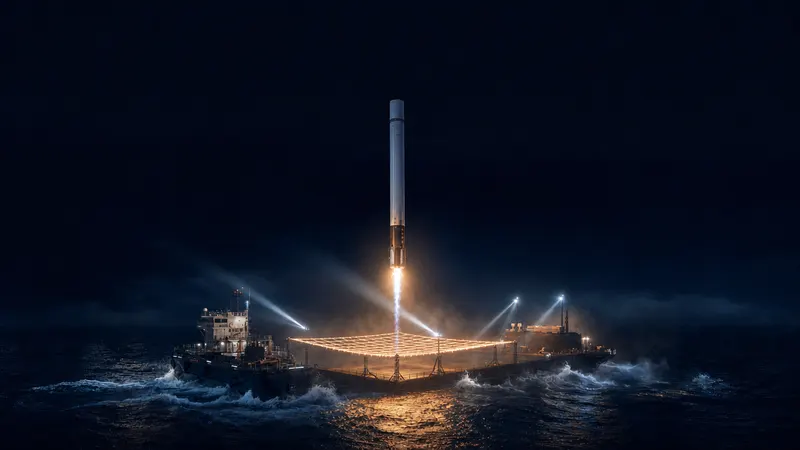
Catching a Rocket: China's Offshore Net-Capture Recovery and the Reusable-Launch Supply Chain
After the world's first offshore net-capture recovery of an orbital booster, this in-depth report dissects the catch mechanics, the global genealogy of recovery routes, the economics of reuse, and the fiber-net-ship supply chain behind Long March 10B - including a sober debunking of a supplier-attribution frenzy - and closes with three testable forecasts.
China's Green Hydrogen and Electrolyzer Equipment Industry (2026): 3 GW of Tenders, 58 GW of Capacity, and the Upstream Order Map
China's domestic electrolyzer tenders reached 3.02 GW in 2025 against roughly 58 GW of nameplate capacity, with extreme alkaline bids down to about RMB 375/kW — this report translates the green hydrogen mega-base boom into an order map for upstream suppliers of diaphragms, electrodes, and rectifier power supplies.
China's Injection Molding Machine Industry 2026: All-Electric, Super-Sized, and Going Global in a Cold-at-Home, Hot-Abroad Market
Haitian International posted RMB 17.733 billion in 2025 revenue with overseas sales up 26.4%, and industry-wide exports hit RMB 13.9 billion in the first ten months — incremental orders for injection molding machines are shifting from China's domestic market to Southeast Asia and Mexico, and rippling upstream through servo systems, screws and barrels, and hydraulic components.
China's Solid-State Battery Supply Chain (2026): Order Opportunities Along the Materials and Equipment Tracks
Global solid-state battery shipments reached 5.3 GWh in 2024 — all semi-solid-state; in 2026 semi-solid-state vehicle installations are scaling up and leading battery makers' all-solid-state pilot lines are landing in clusters, while lithium sulfide still costs over RMB 3 million per tonne and all-solid-state equipment investment per GWh runs 2–3x that of liquid-electrolyte lines — procurement windows on both the materials and equipment ends are opening at the same time.
China's eVTOL and Low-Altitude Economy Supply Chain (2026): Now That Airframers Have Their Certificates, Which Upstream Factories Are the Orders Flowing To?
The newly revised Civil Aviation Law took effect on July 1, 2026, EHang delivered 221 aircraft in 2025, and AutoFlight won the world's first overseas airworthiness validation for an eVTOL — on the eve of volume production, order opportunities are opening up across four upstream tracks: motors and motor controllers, aerospace-grade carbon fiber, high-rate batteries, and vertiport equipment.
China's Laser Processing Equipment and Laser Industry in Review (2026): After Localization Is Settled, Where Are the Orders Flowing?
China's laser equipment market returned to 95.8 billion yuan in 2025, Raycus's 10kW-plus laser shipments grew another 26%, and China's share of IPG's revenue fell to around 28% — with the price war over, the procurement hotspots along this industry chain are being reshuffled.
On the Eve of Humanoid Robot Mass Production: China's Components Supply Chain Reignited by Orders
Global humanoid robot shipments reached roughly 18,000 units in 2025, up more than fivefold year on year, with Chinese vendors taking the top two spots; TrendForce expects shipments to grow another sevenfold in 2026. Beyond the spotlight on complete machines, a capacity race in screws, reducers, motors, and dexterous hands is unfolding across China's component industrial clusters.
China Industrial Lubricants 2026: Great Wall and Kunlun Duopoly with Longpan Going Abroad
China consumed about 7.7 Mt of lubricants in 2025; Sinopec Great Wall and PetroChina Kunlun together hold about 38%, while Lubrizol, Infineum, Chevron Oronite and Afton still control over 91% of compound additives. This report dissects the 2025 market structure, API Groups I-V base oils, refining and blending, leading players, industrial and automotive categories, EV coolants, downstream factory identification, Longpan going abroad via Lubricos, capacity, pricing, policy and risk.
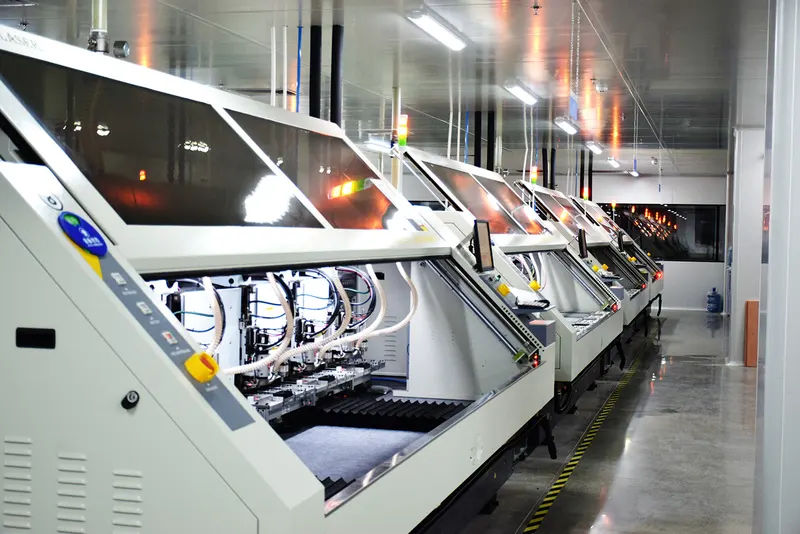
2026 China PCB Equipment Industry: Market Size & Localization Substitution
A research-institute report on China PCB equipment 2026: mechanical and laser drillers, LDI direct-imaging exposure, wet lines and AOI. Benchmarks Han's CNC, Dingtai Hi-Tech, Dongwei, Suzhou Tianzhun against Schmoll Maschinen, Hitachi ViaMechanics, Mitsubishi, Posalux, Orbotech, with a 2026–2030 outlook.
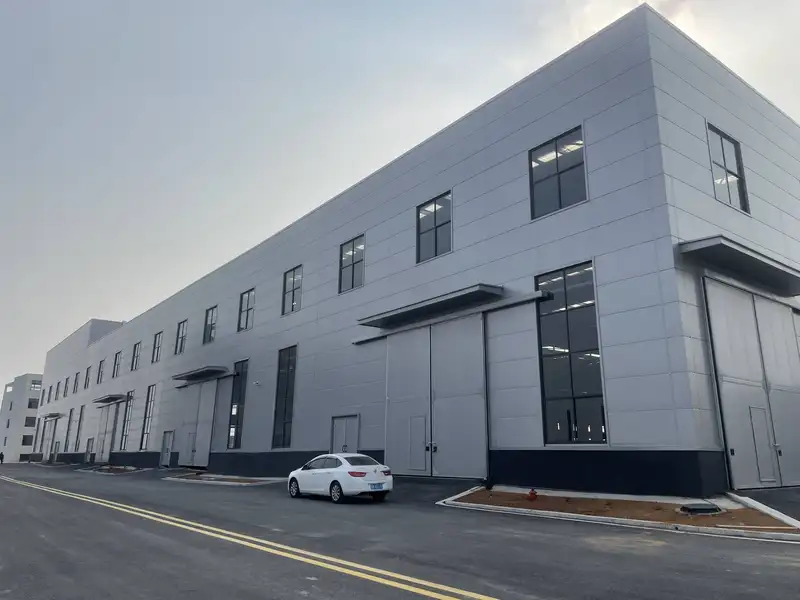
China's Prefab Steel Structure and Construction 2026 — Industrial Plants, Mega Venues, and Steel Bridges Reshaping the General-Contracting Tier
2026 China steel-structure and prefab-construction deep research: 132M-t output, 35.6% prefab share, CR10 9.4%; Honglu/Jinggong/Hangxiao/Southeast/Fuhuang/CRBC vs Nucor/Steel Dynamics/Tata/SSAB/Cleveland-Cliffs/ArcelorMittal Europe; fabs, lithium, data centres, EV assembly, cross-sea bridges, prefab housing, floating wind; CBAM + prefab plan + East-West Compute + BRI; 5-to-10-year consolidation window.