


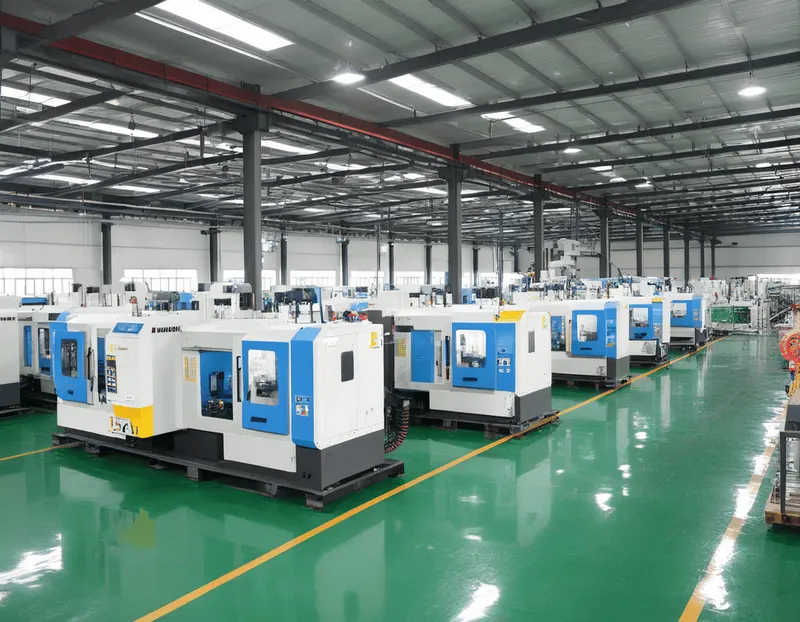
China's Injection Molding Industry 2026: Market Size and Competitive Landscape
A systematic analysis of the market size, value chain, and competitive landscape of China's injection molding industry in 2026: a highly concentrated machine segment (Haitian leads at home with 30%+ share, first worldwide) versus an extremely fragmented midstream of roughly 5 million molders. Chinese machines have moved from import substitution to export leadership, yet all-electric, precision, and large-tonnage high-end still belong to Japan and Germany.
China's Fastener Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's fastener industry in 2026: nearly 10 million tonnes produced a year and first worldwide, yet a fragmented pyramid of low-end overcapacity and high-end imports, where imported high-end fasteners fetch 8-9 times the price of exported standard parts. Demand concentrates in automotive (~58%); wind power, rail, and aerospace are the high-value growth tracks, with aerospace titanium-alloy fasteners the ultimate chokepoint.
China's Bearing Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's bearing industry in 2026. Called the joints of industry, bearings see China produce nearly 30 billion units a year (first worldwide for years; 2024 revenue about RMB 231.5 billion), yet it stays a textbook large-industry-of-small-companies: CR10 only about 28%, high-end products just about 5% with roughly 70% import dependence. An import-export unit-price gap of about 74% lays bare the gulf between scale and precision.
China Reducer Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
The reducer is the joint of manufacturing. This report examines China reducer industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. The industry has two faces: general-purpose reducers are small and scattered with over 90% localization, while precision reducers are the value high ground for domestic substitution. Domestic RV reducers now hold about 60.8% share and harmonic reducers over 80%, yet lifespan and upstream bottlenecks still lag.
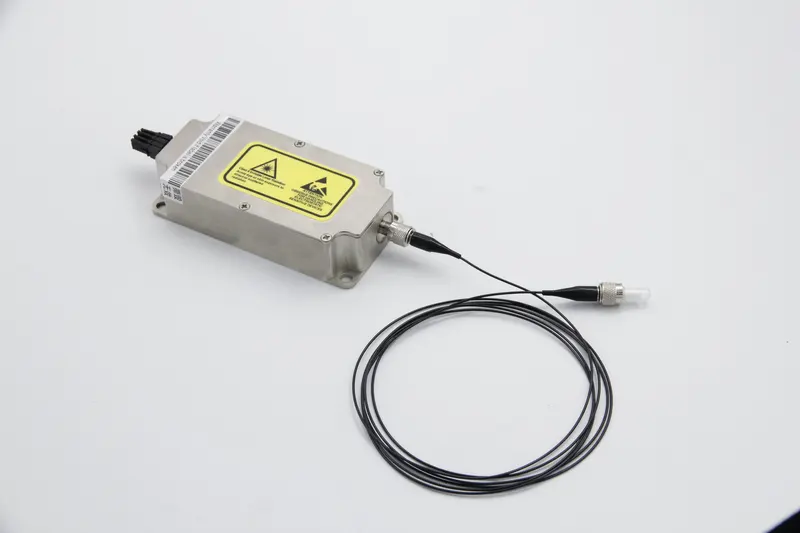
China Laser Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Lasers are the optical scissors of industry. This report examines China laser industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. China is the largest laser equipment consumer globally; low-to-mid power fiber laser localization exceeds 99%, with Raycus overtaking IPG at about 27% China share. Yet high-power pump chips, ultrafast lasers and ASML EUV CO2 sources remain held by IPG, TRUMPF and Coherent.
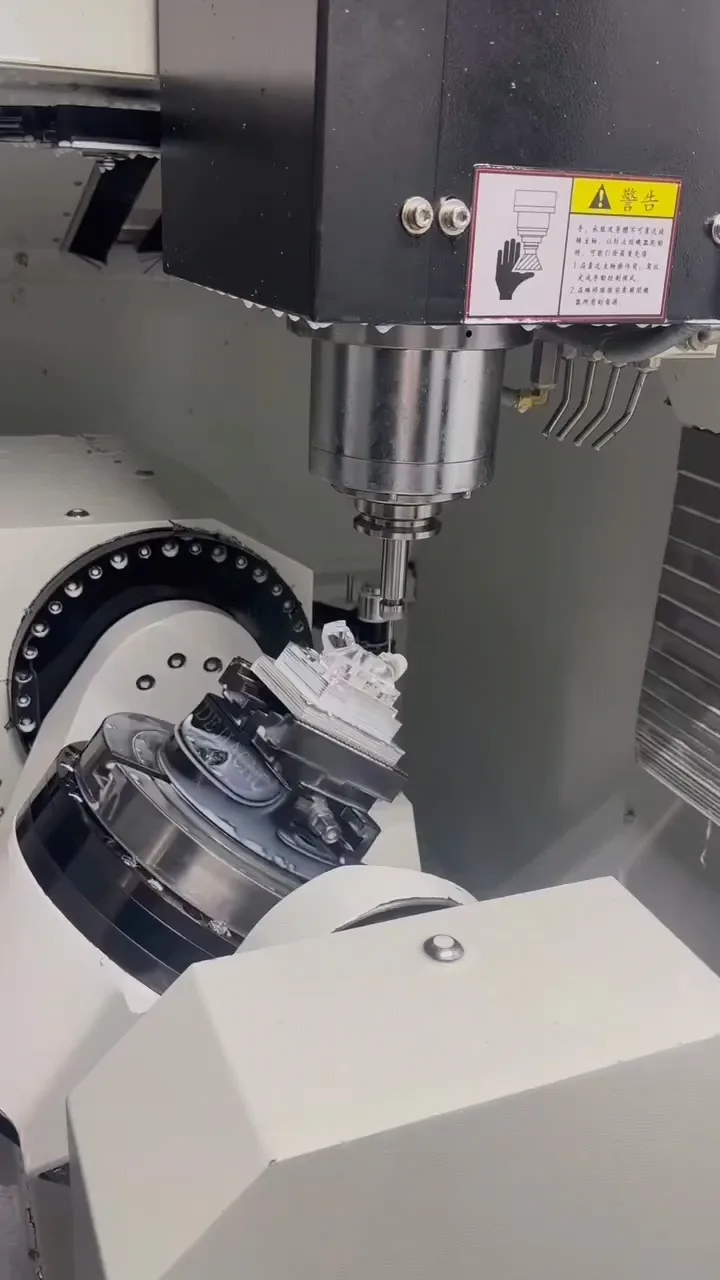
China Machine Tool Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Machine tools are the mother machines of manufacturing — they set the precision ceiling for every factory. This report examines China machine tool industry in 2026: market size, value chain, competition, technology and the 2026-2030 outlook. China leads globally in both output and consumption (about 32% and 33% in 2024), yet localization of high-end five-axis stays around 25% and high-end CNC controllers at just 6%, while Germany and Japan still hold the value peak.
2026 China Construction Machinery Industry: Market Size and Competitive Landscape Deep Research Report
Overseas expansion and electrification define China's construction machinery industry in 2026: domestic real estate contraction drove the four majors toward global markets; excavator domestic/export parity marks a structural shift; electric excavators totaled 86 units in 2024 but loaders crossed 10% penetration. Hengli Hydraulic leads hydraulic localization; SANY, XCMG, Zoomlion, and LiuGong target 58-62% overseas revenue by 2030.
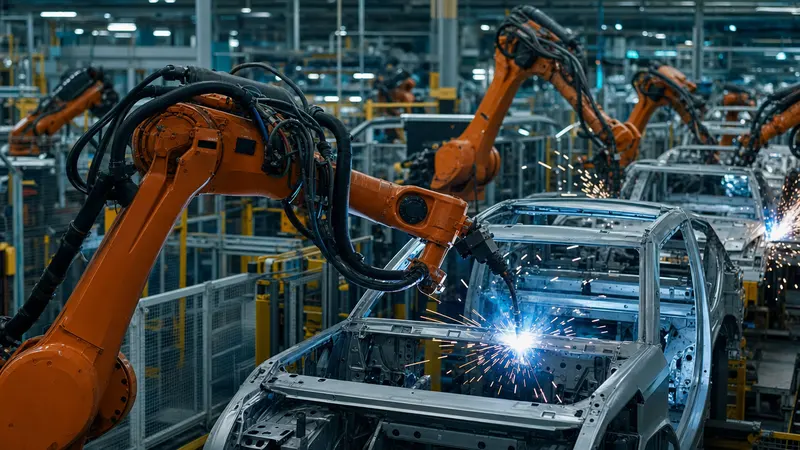
China Industrial Robot Sector: 2026 Market Scale and Competitive Landscape Research Report
In 2024, China added 295,000 newly installed industrial robots (54% of global total), with domestic brands capturing 57% domestic share for the first time—a historic inflection. The Big Four (Fanuc, ABB, KUKA, Yaskawa) still hold the high-end segment with precision-reducer and controller moats, while Estun and Inovance drive domestic breakthroughs. Humanoid robots are the largest upside scenario and the greatest uncertainty through 2030.
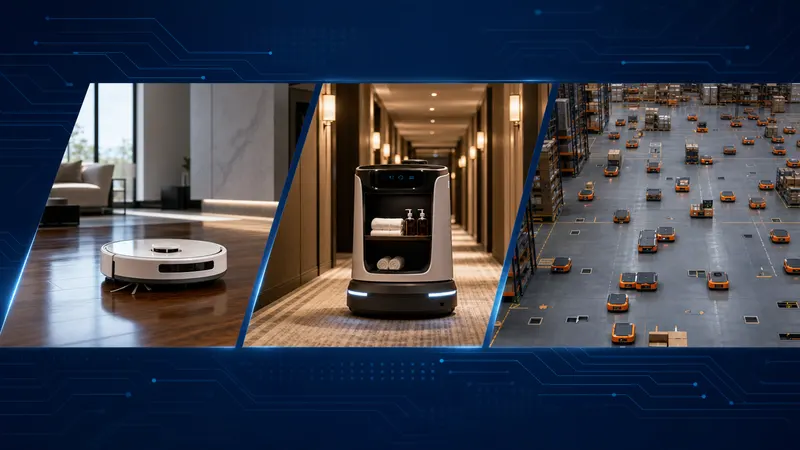
2026 China Service Robots Industry Report: Market Scale, Competitive Landscape and Forecasts (Robotic Vacuums, Commercial Delivery & Warehouse AMR)
China service robot market reached approximately ¥200 billion in 2025, capturing 40%+ of the global market. Roborock revenue hits ¥18.7B, Geek+ IPO at HK1B, iRobot bankrupt and taken over by Shenzhen OEM — this deep-dive report analyzes market scale, competitive dynamics, supply chain and 2030 forecasts across household cleaning, commercial delivery, and warehouse AMR segments.
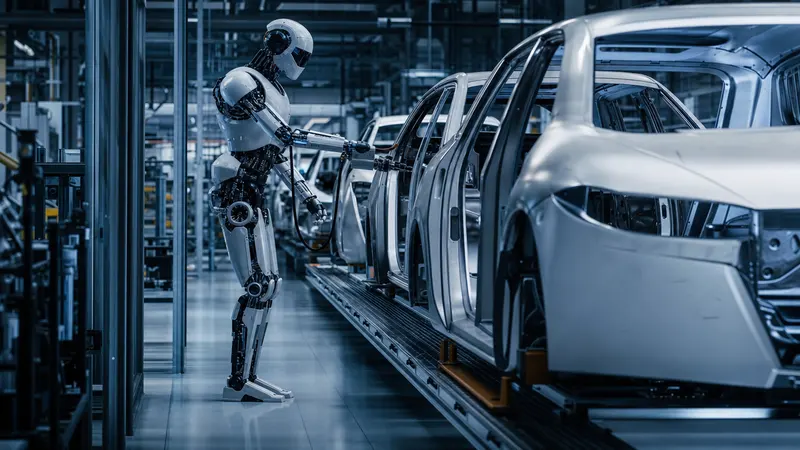
2026 China Humanoid Robot Industry Market Scale and Competitive Landscape Deep Research Report
2026 mass-production year panorama: China accounts for 84.7% of global shipments, Unitree holds 32.4% global market share, embodied AI models GR00T/Helix/GO-1 drive intelligence leap, harmonic reducer localisation accelerates — systematic overview of global landscape, supply chain deep dive, key companies and 2026–2030 market forecast.
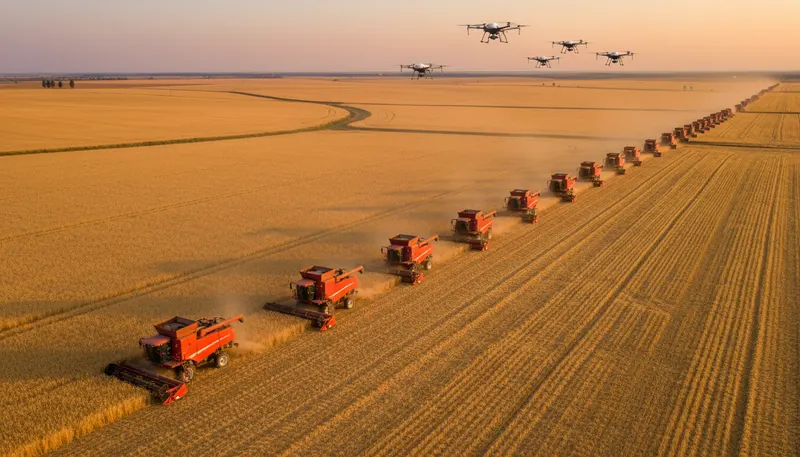
National Fortune in the Harvest Machine: The Rise and Future of Chinese Agricultural Machinery (2025-2030)
In the first half of 2025, China's agricultural machinery exports reached RMB 34.9 billion, up 37% year on year; cumulative agricultural drone holdings surpassed 500,000 units. Chinese-made combine harvesters work in Southeast Asian rice paddies, and Dongfanghong tractor orders extend to the black soil of Africa. This is the complete puzzle of Chinese agricultural machinery: a RMB 450 billion market, four narrative threads, and the restructuring of the global competitive landscape.
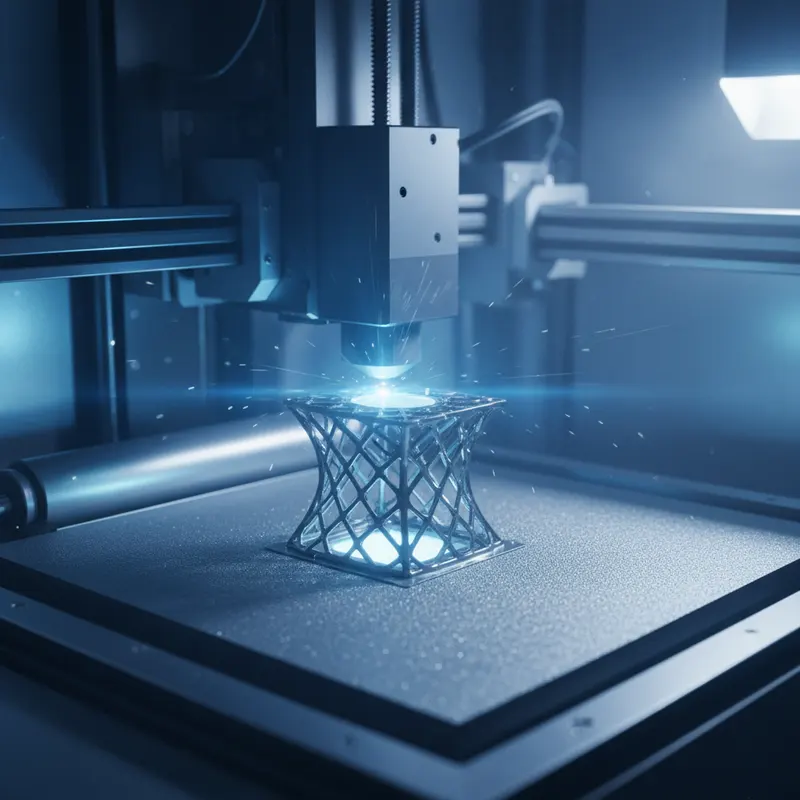
2026 China Additive Manufacturing and 3D Printing: Market Scale, Competitive Landscape & 5-Year Outlook
A comprehensive analysis of the global USD 30.5B and China RMB 52B additive manufacturing market in 2025, featuring in-depth financials on BLT, Farsoon, 3D Systems, Stratasys, and Desktop Metal bankruptcy, with vertical application deep-dives and 2026–2030 forecasts at 24% CAGR.
2026 China Vacuum Pump & Compressor Industry Deep Research Report
Comprehensive analysis of industrial vacuum pumps, semiconductor dry pumps, refrigeration compressors: market scale CNY 11.7B, localization progress, refrigerant transition, and 2026-2030 strategic outlook.
China Precision Bearing and Ball Screw Industry 2026 — The Precision Lifeline of Machine Tools, Robots and EV Powertrains
A panoramic 2026 report on China's precision bearing and ball screw industry: domestic substitution tiers, upstream bearing steel, precision grinding, six downstream battlefields (machine tools, robots, wind power, high-speed rail, EV, semiconductors), planetary roller screws in humanoid robots, and supply-chain insights from 4.8 million verified factory records.
China Industrial Valve 2026 — Breaking Through in Nuclear Ball Valves and LNG Cryogenic Valves
Driven by batch nuclear power construction, rapid LNG expansion, hydrogen energy development, and semiconductor capacity growth, China's industrial valve industry is accelerating its transformation from mid- to low-end general components toward high-end categories such as nuclear-grade ball valves, LNG cryogenic valves, hydrogen-station valves and semiconductor specialty valves.
China Industrial Pump Industry 2026: Full-Spectrum Localization from Chemical Process Pumps to Nuclear Reactor Coolant Pumps
Industrial pumps are the most widely used fluid machinery in manufacturing. This report covers centrifugal pumps, magnetic drive pumps, canned motor pumps, reactor coolant pumps, slurry pumps, and metering pumps—providing a comprehensive 2026 outlook on China's industrial pump industry including global market structure, technology barriers, supply chain analysis, localization progress, and future trends.
China Industrial Metrology 2026 — Domestic Breakthrough from CMM to Laser Trackers
A comprehensive analysis of China's industrial metrology industry — from CMM, structured-light scanning, and laser trackers to industrial CT — covering market structure, four-tier domestic substitution framework, key players, and strategic outlook for 2026–2030.
China Mobile Robots AGV/AMR 2026 — Collaborative Vehicle Intelligence from Warehouse Logistics to Flexible Production Lines
China's AGV/AMR market reached RMB 19.665 billion and 158,300 units in 2024, covering e-commerce warehousing, new energy vehicles, lithium batteries, and 3C electronics. This report analyzes the AGV vs AMR technology divide, competitive landscape, key technology trends, typical industry applications, export competitiveness, supply chain value distribution, and lifecycle ROI.
China Collaborative Robot 2026 — From JAKA and Dobot to ABB Yumi, A New Human-Robot Co-Line Industrial Order
A comprehensive 2026 research report on China's collaborative robot industry. Covering market landscape, core technologies, supply chain, applications, key players, domestic substitution trends, investment, and research judgments based on data from 4.8 million verified factories.
China CNC Controller 2026 — The Domestic Substitution Battle for the Industrial Mother Machine Brain
An in-depth analysis of China CNC system market in 2026: technology tiers, leading players, domestic substitution progress, AI-enabling trends across 14 key themes.
China Industrial Welding 2026
2026 China industrial welding research report.
China Food Packaging Machinery 2026: High-Speed Aseptic Filling and PET Line Localization
A systematic review of the 2025-2026 China food packaging machinery market, PET blow molding and aseptic filling processes, financial performance of domestic leaders Tech-Long and Newamstar, benchmarked against global giants Krones, Tetra Pak, and Sidel, with deep analysis of the PET line localization roadmap and capex cycles in downstream beverage and food factories.
China High-Pressure Cylinders 2026 — Twin Ramp of 70 MPa Type-IV Hydrogen Storage and LNG Mobile Tank Containers
China's 2025 high-pressure cylinder market reached RMB 124 billion. 35 MPa Type-III is nearly fully localized; 70 MPa Type-IV just crossed national-standard certification; LNG-heavy-truck penetration is rising fast; industrial cylinders provide stable cash flow. This 14-chapter report maps the chain from carbon fiber to cylinder valves and the next 5-year evolution.
China Cutting Tools 2026: High-End Domestic Substitution of Carbide Indexable Inserts
Global metal cutting tools market USD 46.6 billion; China RMB 54 billion. From Zhuzhou Diamond, Oke Precision, Huarui Precision to Worldia and Hengfeng Tools, domestic indexable insert localization has exceeded 70%. Next 3 to 5 years are the critical window from mid-low to mid-high end.
China Industrial Hydraulics 2026 — High-end Domestic Substitution from Excavator Cylinders to High-pressure Piston Pumps
China Offshore Engineering Equipment 2026: Premium Breakthrough in Wind Installation Vessels and Deep-Water Drilling Platforms
Global offshore engineering equipment hit 75 to 88 billion US dollars in 2025; Chinese yards captured 31.2 billion (41.2 percent global). WTIV is in short supply; deep-water drillship and FPSO orders rebound. Six firms (CSSC Offshore, CNOOC Engineering, Zhenhua, China Merchants, CIMC Raffles, Waigaoqiao) split workload. DP3, deep-sea pressure, and work-class ROV localization decides the 3 to 5 year premium breakthrough window.
China Mechanical Seals 2026 — Hidden Champion Cdsii and High-End Domestic Substitution
China Mechanical Seals 2026 in-depth report: focusing on the pattern evolution between local leaders like Cdsii and global giants like John Crane, EagleBurgmann, Flowserve, AESSEAL — decomposing the three high-end breakthrough battlegrounds of dry gas seals, nuclear primary pump seals, and gas turbine seals.
China Powder Metallurgy 2026: The Dual-Track Breakthrough of MIM and High-End Metal Soft Magnetic Powder Cores
Powder metallurgy is long underestimated by outsiders, but China hit nearly RMB 48 billion in 2025 at 12% CAGR. Press-and-sinter, MIM, metal soft-magnetic cores, and 3D printing metal powder are four sub-tracks with vastly different growth. This report covers leading players, overseas giants, four downstream drivers (foldable, EV OBC, AI servers, COMAC), 3-5-year calls and risks.
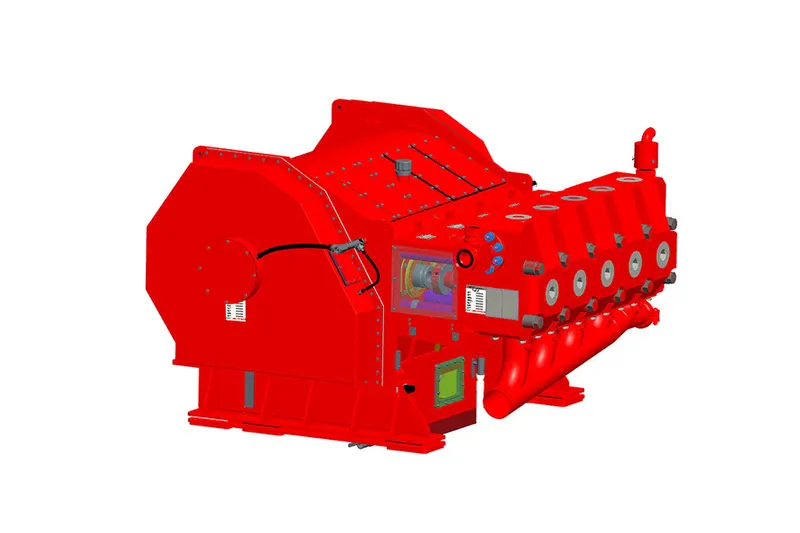
China Oil & Gas Drilling Equipment 2026 — The Dual Engine of Shale Frac Pumps and Overseas Rig Exports
China oil & gas drilling equipment 2026: covers land rigs, frac pumps, cementing, workover and downhole tools. Benchmarks Jereh, Baoji and Zhongman against Halliburton, Schlumberger, Baker Hughes and NOV. Electric frac, Middle East and Central Asia exports, price cycles, 3-5 year outlook.
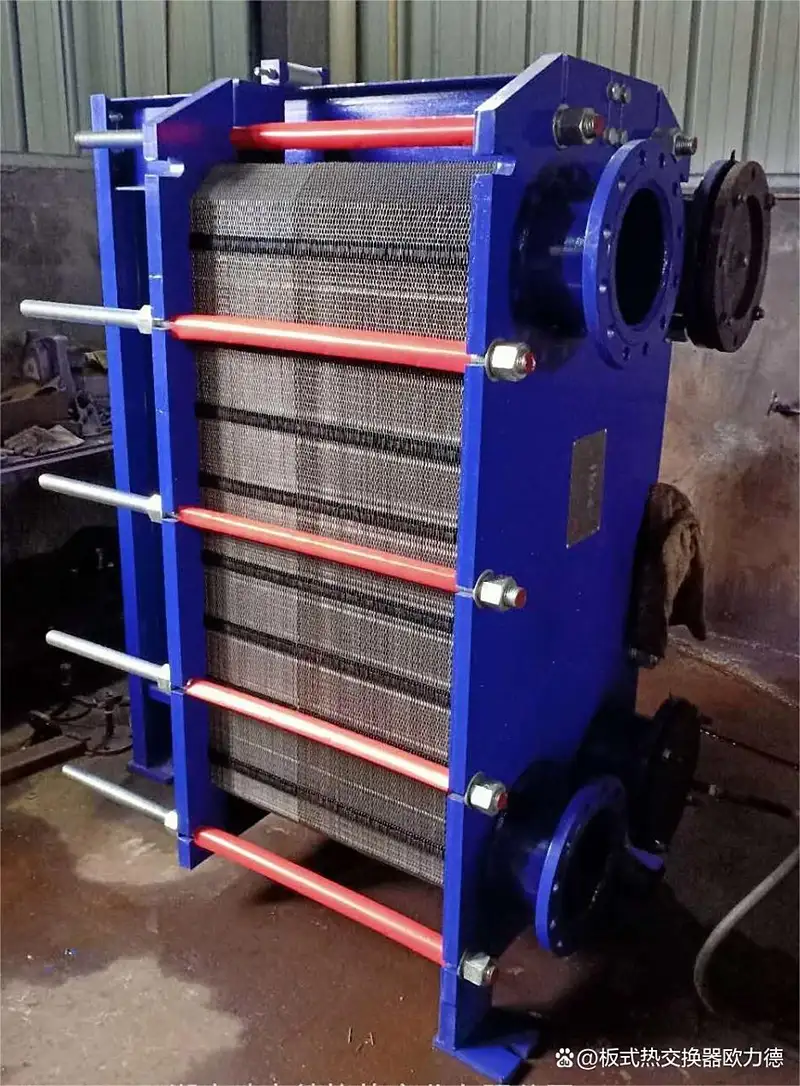
China Industrial Heat Exchanger 2026: High-End Localization and Overseas Penetration of Plate, Shell-and-Tube and Microchannel
An in-depth research view of China's industrial heat exchanger market in 2026: plate, shell-and-tube, microchannel, plate-fin and air-cooler segments; localization milestones against Alfa Laval, Kelvion, SWEP, Tranter and Danfoss; capacity maps for Yuanda, Shuangliang, Sifang, Hongsheng and Yinlun; data-center liquid cooling, NEV thermal management, heat pumps and hydrogen as the new growth engines.
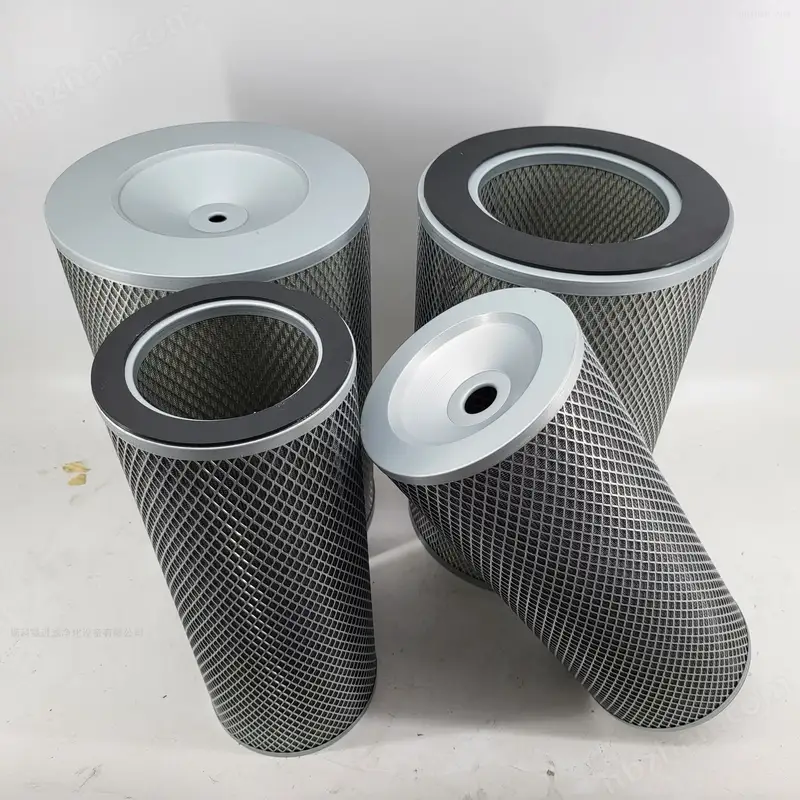
China Industrial Filters 2026: How Domestic Substitution Is Quietly Rewriting a List Long Dominated by Foreign Giants
China's industrial filter sector — long undervalued — enters 2026 with policy and domestic substitution dividends. The report walks through five product categories, seven process barriers, thirteen makers, two downstream groups, seven substitution cells, capacity expansion, pricing, China 7, Phase III fund and risks. Total market 40-45B yuan with domestic share rising to 55-60%.
China Industrial Pneumatic Components 2026 — Localization of Cylinders, Solenoid Valves, and Vacuum Equipment
An in-depth research report on China's industrial pneumatic components industry in 2026, covering cylinders, solenoid valves, vacuum equipment, and domestic substitution by AirTAC, SMC China, Festo, and Ningbo Jialing.
China Industrial Kiln and Furnace Equipment 2026: Cement, Glass, Ceramics, Metallurgy EPC and Overseas Expansion
This report maps China industrial kiln and furnace equipment in 2026 — cement, float glass, ceramic, EAF, semiconductor vacuum, and lithium-battery firing furnaces. It tracks the retreat of FLSmidth, KHD, Maerz, Vesuvius from China; the rise of Sinoma International, Triumph Group, Tangshan Hexiang, NHI, Beijing Lier, NAURA; and the structural surge of overseas EPC and new-energy furnace demand.
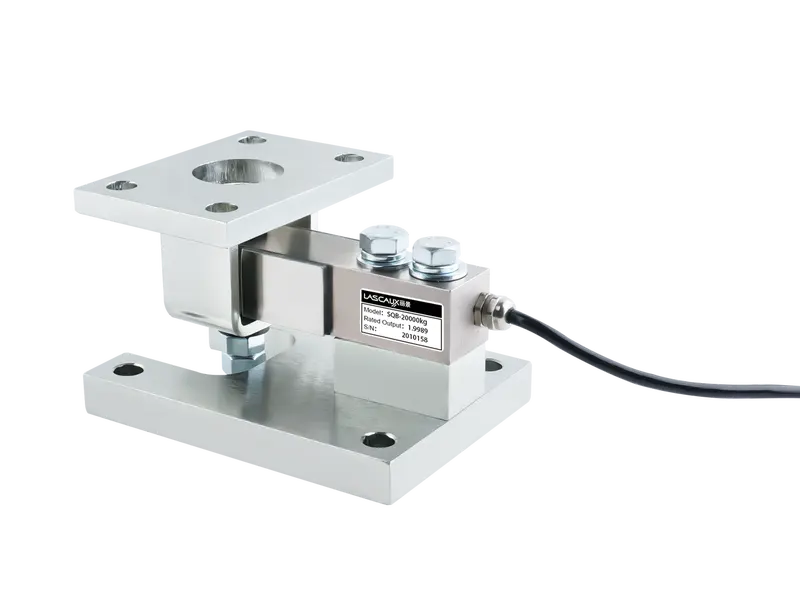
China Industrial Force Sensors 2026: The Hidden Champions Behind Weighing, Torque and Pressure
Comprehensive 2026 research on China's industrial force sensor industry: load cells, torque, pressure, 6-axis, dynamic piezoelectric, microbalance. 14 chapters covering RMB 22B China market, USD 10.5B global market, humanoid robot 6-axis ramp, COMAC C919/C929 + CJ-1000A high-end breakthrough, capacity expansion across Ningbo/Xi'an/Suzhou/Xiangyang/Beijing, OIML international recognition, price cycles, policy windfalls and six major risks.
On the Eve of Humanoid Robot Mass Production: China's Components Supply Chain Reignited by Orders
Global humanoid robot shipments reached roughly 18,000 units in 2025, up more than fivefold year on year, with Chinese vendors taking the top two spots; TrendForce expects shipments to grow another sevenfold in 2026. Beyond the spotlight on complete machines, a capacity race in screws, reducers, motors, and dexterous hands is unfolding across China's component industrial clusters.
China's Laser Processing Equipment and Laser Industry in Review (2026): After Localization Is Settled, Where Are the Orders Flowing?
China's laser equipment market returned to 95.8 billion yuan in 2025, Raycus's 10kW-plus laser shipments grew another 26%, and China's share of IPG's revenue fell to around 28% — with the price war over, the procurement hotspots along this industry chain are being reshuffled.
China's Injection Molding Machine Industry 2026: All-Electric, Super-Sized, and Going Global in a Cold-at-Home, Hot-Abroad Market
Haitian International posted RMB 17.733 billion in 2025 revenue with overseas sales up 26.4%, and industry-wide exports hit RMB 13.9 billion in the first ten months — incremental orders for injection molding machines are shifting from China's domestic market to Southeast Asia and Mexico, and rippling upstream through servo systems, screws and barrels, and hydraulic components.
China's Heavy-Duty Gas Turbine Industry 2026: Where AI's Power Hunger Meets a 25-Year March to Self-Reliance
AI data centers have pushed global gas turbine order books beyond 2030, with the Big Three sold out and prices roughly tripling in three years. At precisely this moment, China's homegrown heavy-duty gas turbines completed three critical steps: G50 commercial operation, 300 MW first fire, and export to North America. This 33-chapter report dissects the historic convergence, from hot-section technology and capacity pricing to the export window and its risks.
China's Shield Machine and Tunnel-Boring Equipment Industry 2026: From the Qinling Blockade Line to Seventy Percent of the World, and Where to Go After the Summit
From paying RMB 350 million per German machine at Qinling in 1997 to holding roughly 70% of global capacity in 2026 and rolling out a world record almost every month, China's shield-machine industry completed its reversal in under three decades. But after the summit, the concerns are real: 1,500 idle machines, an ebbing metro market, net margins below 5%, and a 300,000-person talent gap. This report dissects how China moves from 'first in manufacturing' to 'first in industrial health.'
China's Construction Machinery Industry 2026: Heavy Iron Goes Global, the Last Mile from Chaser to Peer
In 2026, on the KHL Yellow Table, XCMG ranks third globally, SANY sixth and Zoomlion tenth—three Chinese firms in the top ten. China dominates concrete pump trucks, leads in large cranes, and electric-loader penetration broke 50% in a year. Yet from the summit—Caterpillar—its makers are still 'one last mile' away: high-end hydraulics, engines and sensors remain constrained, and brand premium still trails. A study of an industry 'big and growing strong, one last mile from the summit.'
2026 China Sewing Machinery Industry: Market Size & Competitive Landscape
In 2025 Vietnam overtook China as the largest apparel supplier to the US — yet the sewing machines stitching those garments still come from Taizhou. This report dissects China's sewing machinery industry: 170 years of migration (US–Japan–China), a strongly cyclical market and its export structure, the four survival paths of leading firms, four decades of the Taizhou cluster, the Zhuji embroidery-machine belt, the frontier of automated sewing, and our 2026–2030 outlook.
2026 China Electric Motor Industry: Market Size & Competitive Landscape
Everything that spins hides an electric motor, yet no consumer can name a motor brand. This report dissects the heart of industry: the volume-down-value-up shift since the 2021 output peak, high-efficiency motor output rising from 39% to 73% in three years, WEG overtaking ABB while Nidec exits EV traction, 7.76 million EV drive units and their profit squeeze, humanoid-robot hype versus a RMB 209M frameless-motor market, and a 2026-2030 outlook.