2026 China Sewing Machinery Industry: Market Size & Competitive Landscape
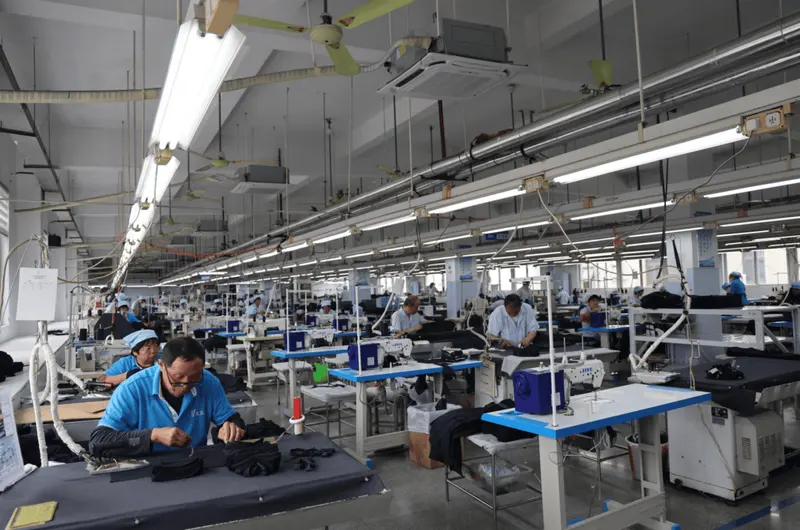
In 2025 Vietnam overtook China as the largest apparel supplier to the US — yet the sewing machines stitching those garments still come from Taizhou. This report dissects China's sewing machinery industry: 170 years of migration (US–Japan–China), a strongly cyclical market and its export structure, the four survival paths of leading firms, four decades of the Taizhou cluster, the Zhuji embroidery-machine belt, the frontier of automated sewing, and our 2026–2030 outlook.
China's Power-Battery Recycling 2026: The First Year of Binding Rules, and a Disordered Urban Mine
On 1 April 2026, MIIT Order No. 73, issued jointly by six ministries, took effect, giving power-battery recycling in China its first binding regulation. It confronts a peculiar industry: whitelisted firms hold nominal capacity counted in millions of tonnes yet process only a fraction of it, and roughly eight in ten scrapped electric vehicles arriving at licensed dismantlers have no battery. This is not an industry short of capacity, but one short of order.
China's Elevator Industry 2026: 12.3 Million Units Installed and a New-Build Market That Has Peaked
At the end of 2025 China's installed base of elevators reached 12.3159 million units, the largest single class of special equipment in the country. In the same year, output of elevators, escalators and lifts fell to 1.401 million units. An industry that staked thirty years of growth on new buildings is now being forced to learn a different business: maintaining, modernising and replacing the twelve million units already in place.
China's Home Appliance Industry 2026: White-Goods Kingdom — From Selling the Most to Selling the Priciest
Haier has topped Euromonitor's global major-appliances retail-volume brand ranking for 17 straight years, Midea is the world's largest appliance maker by revenue (RMB 458.5 billion), and China makes nearly 95% of the world's AC compressors. Home appliances are China's most complete leap from world's factory to world's brand. Yet from selling the most to selling the priciest, one last leg remains: appliance chips, brand premium and high-end kitchen appliances.
China's Display Panel Industry 2026: From 'Screen Famine' to Global Dominance—A Counter-Cyclical Comeback and the Last Fortresses at the High End
In 2012, China imported USD 50.3 billion of LCD panels—its fourth-largest import after chips, crude oil and iron ore: the 'screen famine.' A decade later, mainland China supplies about 95% of the world's LCD panels, BOE leads all five major categories, and panel revenue share topped half in H1 2025 (52.1%). Powered by counter-cyclical investment and the Hefei model, China staged its most dramatic manufacturing comeback. Yet the high-end 'last fortresses' remain.
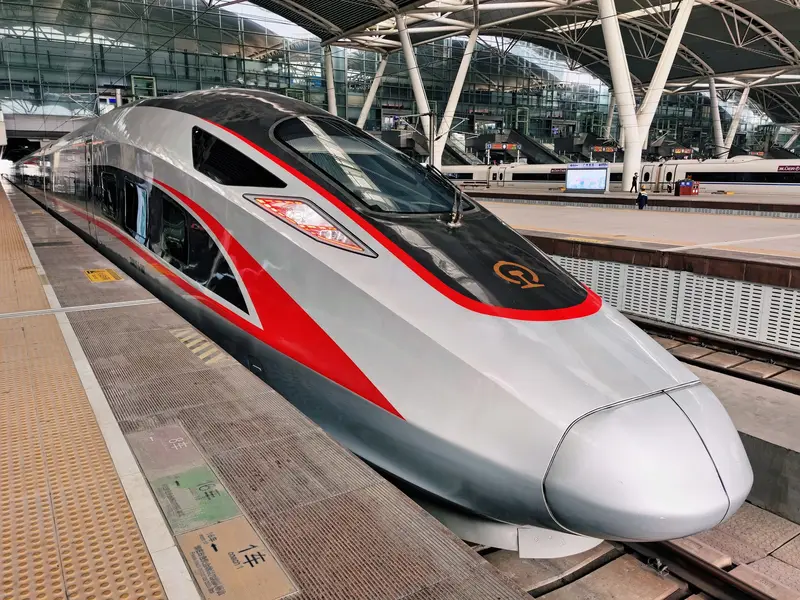
China's High-Speed Rail and Rail Transit Equipment Industry 2026: A National Calling Card's Ascent, and Its 'Smooth South, Blocked North' Overseas Expansion
In 2026, China's high-speed rail in service tops 50,000 km—over 70% of the world's total; CRRC is the world's largest rail-equipment maker at about 53% share; and the CR450 enters uncharted territory at 400 km/h in service. From importing four technology platforms to the fully indigenous Fuxing and leading UIC standards, China completed the full arc of ascent to the summit. Yet this calling card's overseas push is 'smooth in the South, blocked in the North.'
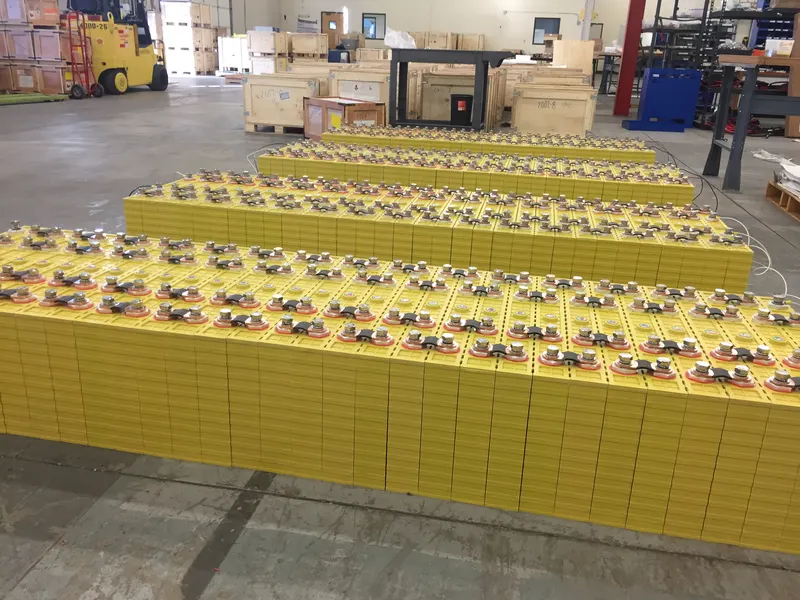
China's Power Battery Industry 2026: One Battery Behind Many World Firsts, and Its Threefold Siege
In 2026, CATL leads the world for a ninth straight year (39.2% share), BYD is second, six Chinese firms sit in the global top ten, and Chinese makers hold about 69% of the world EV-battery market. Yet precisely because it is so strong, it faces a threefold siege: external regulatory encirclement (US IRA/FEOC and tariffs, EU battery law), an upstream resource chokepoint (70% of lithium imported), and internal overcapacity. This report dissects the peak and the predicament.
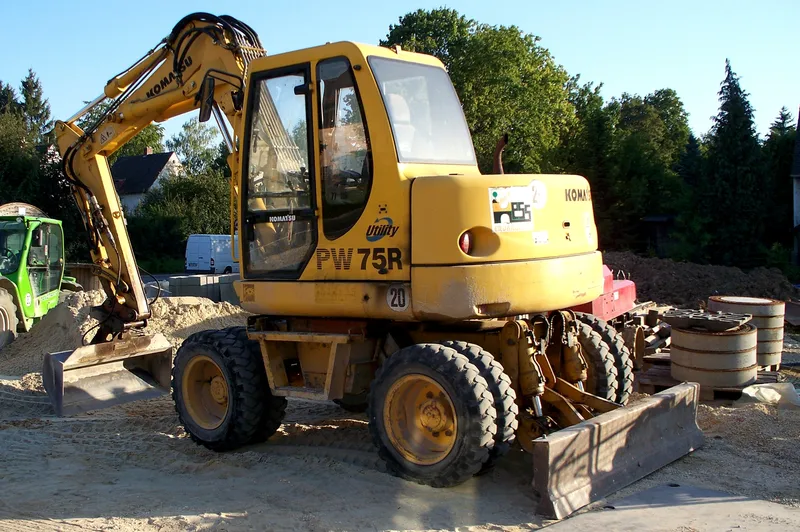
China's Construction Machinery Industry 2026: Heavy Iron Goes Global, the Last Mile from Chaser to Peer
In 2026, on the KHL Yellow Table, XCMG ranks third globally, SANY sixth and Zoomlion tenth—three Chinese firms in the top ten. China dominates concrete pump trucks, leads in large cranes, and electric-loader penetration broke 50% in a year. Yet from the summit—Caterpillar—its makers are still 'one last mile' away: high-end hydraulics, engines and sensors remain constrained, and brand premium still trails. A study of an industry 'big and growing strong, one last mile from the summit.'
China's Civilian Drone Industry 2026: Strong Yet Besieged — One Company, One Nation's Sky
In 2026, DJI holds roughly 70% of the global consumer-drone market, China's agricultural drones top 300,000 units and enter the No.1 Central Document, and delivery-drone orders outpace Google's Wing—a technologically dominant, globally leading industry. Yet precisely because it is so strong, DJI faces US category-wide sales bans, customs seizures, and supply-chain warfare. This report dissects the era's defining question of a Chinese industry that is 'strong yet besieged.'
China's Power Tool Industry 2026: From World's Factory to World's Brand, the Next Leg for Hidden Champions
In 2026, Techtronic Industries (TTI) overtook Stanley Black & Decker with USD 15.3 billion in revenue to top the global power-tool industry—a quiet ascent. Yet China makes 60-80% of the world's power tools while brands and premium profits still rest with Milwaukee and Bosch. This report dissects the climb from world's factory to world's brand: the tariff rollercoaster, the cordless revolution and battery platforms, OPE electrification and robotic mowers, and cells displacing Japan and Korea.
China's Tire Industry 2026: Volume Champion, Quality Climb, and a Second Wave of Globalization Under Tariff Siege
China makes roughly half the world's tires yet earns a margin of only about 3%—the starkest picture of being 'big but not strong.' This report dissects how China climbs from volume champion to quality contender: Sailun's Liquid Gold, the NEV OE reversal, Lighthouse factories, near-90% import dependence on natural rubber, and a second wave of globalization from Southeast Asia to Morocco and Egypt.
China's Shield Machine and Tunnel-Boring Equipment Industry 2026: From the Qinling Blockade Line to Seventy Percent of the World, and Where to Go After the Summit
From paying RMB 350 million per German machine at Qinling in 1997 to holding roughly 70% of global capacity in 2026 and rolling out a world record almost every month, China's shield-machine industry completed its reversal in under three decades. But after the summit, the concerns are real: 1,500 idle machines, an ebbing metro market, net margins below 5%, and a 300,000-person talent gap. This report dissects how China moves from 'first in manufacturing' to 'first in industrial health.'