


China PCB Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Printed circuit boards are the backbone of electronics. This report examines China PCB industry in 2026 across market size, supply chain, competition, technology and the 2026-2030 outlook. China mainland accounts for about 54% of global PCB output; Zhen Ding Tech leads at around 12% share. Yet IC substrate and Ajinomoto ABF film localization stays at only 4%-10%, dominated by Ibiden, AT&S and Unimicron. AI servers are the biggest 2024 engine, lifting margins at WUS, Victory Giant and Shennan.
China MLCC and Passive Components: Market Scale and Competitive Landscape Research Report 2026
China consumes 40% of global MLCC output yet mainland producers held only 10% revenue share in 2024. Global MLCC market: USD 140-180B, dominated by Murata (~40%), SEMCO (~24%), Taiyo Yuden, TDK, Yageo (CR5 ~75%). BEVs use 10,000+ MLCCs vs 3,000 in ICE vehicles; automotive localization rate <5%. An Nvidia GB200 rack needs 440,000 MLCCs -- 30x a smartphone. Three-Ring Group leads domestic automotive-grade MLCC. 2030 forecast: USD 230-280B.
China Semiconductor Equipment Market 2026: Scale, Competition, and Localization Roadmap
China is the world's largest semiconductor equipment market (~$40B in 2024, 37% of global demand), yet domestic equipment covers only ~10-12% of total demand. Localization rates span enormously from stripping (65%) to lithography (<5%). This report analyzes ASML, AMAT, Lam, TEL, KLA, thirteen Chinese listed equipment makers, upstream chokepoints, six regional clusters, and forecasts category-level domestic penetration rates through 2030.
2026 China Optical Transceiver Industry: Market Size and Competitive Landscape Research Report
The global optical transceiver market reached approximately USD 17–18 billion in 2024 (+52% YoY), with Chinese vendors holding 7 of the global top 10 positions and CR3 combined share exceeding 50%. This report systematically reviews the optical transceiver supply chain, 800G/1.6T technology roadmaps, key company financials, and a five-year market forecast. Core conclusion: the most certain Chinese advantage segment in the AI compute downstream chain; upstream optical chips are the next domest...
2026 China Display Panel Industry: Market Scale and Competitive Landscape Deep Research Report
Mainland China controls 70%+ of global LCD panel capacity, led by BOE, TCL CSOT, and HKC. Chinese OLED smartphone share surpassed Korea for the first time (50.7%, H1 2024). Gen 8.6 OLED lines — BOE B12 (evaporation) and CSOT t8 (inkjet-printed) — are the biggest technology variable of 2024-2026. This report covers technology taxonomy, global landscape, supply chain, key companies, cluster geography, six application markets, technology roadmap, and 2030 forecasts.
2026 China CMOS Image Sensor (CIS) Industry Market Scale and Competitive Landscape Deep Research Report
CMOS Image Sensors (CIS) are among the most widely deployed visual perception chips today, with a global market of approximately USD 23.7 billion in 2024. Sony leads with ~52% market share. China's domestic localization rate stands at ~30%, with the Big Three (Will/OmniVision, Galaxycore, SmartSens) holding ~23% combined global share and accelerating through automotive ADAS and security tracks. Projected composite localization rate: 45–50% by 2030.
Apple Chain Reshaping and the AI Hardware Boom: China Consumer Electronics Foundry Deep Research Report 2026
In 2025, Luxshare surpassed Foxconn in iPhone assembly share; India production reached 25% of global iPhone output, while China's Apple chain share declined to 65–70%. AI servers, AI glasses, and foldables are opening a RMB 1–2 trillion new growth window. This report covers FY2025 data for ten leading companies and forecasts the 2026–2030 landscape.
China IC Design Industry: Market Size, Competitive Landscape, and In-Depth Research Report 2026
In 2025, China's IC design sector posted annual sales of RMB 835.73 billion (~USD 118B), crossing the hundred-billion-dollar threshold for the first time; 3,901 IC design firms — most globally. Domestic AI chip share rose from ~5% (2022) to 42% (2025); automotive analog IC substitution is accelerating; Montage Technology co-leads DDR5 RCD globally with Rambus. Full 12-chapter report covering FY2025 financials of 20+ companies.
The Sub-RMB-1500 Inflection: 2026 Deep Research Report on China LiDAR Industry Market Size and Competitive Landscape
In 2025, global automotive LiDAR shipments surpassed 2.5 million units with Chinese vendors capturing 80%+; RoboSense MX achieved the historic sub-RMB 1,500 mass-production price point; Luminar filed for bankruptcy; and robot LiDAR materialized as current-quarter revenue. This report uses 2026 as its observation point to systematically review China LiDAR technology routes, supply chain, market size, key companies, and 2026-2030 forecasts.
Smartphones: China's Global Contest for the Palm of Your Hand (2026 Deep Research Report)
In 2025, more than one in every two smartphones sold globally came from a Chinese brand. Huawei reclaimed China's top shipment position for the first time in five years; Apple set an all-time iPhone shipment record; foldable screen penetration surpassed 3%; and on-device AI large language models became the new standard on flagship handsets. This is a systematic study of the structure, technology, and future trajectory of China's smartphone industry.
2026 China Third-Generation Semiconductor (SiC/GaN) Substrate and Device Industry: Market Size and Competitive Landscape Deep Research Report
In 2025, China's SiC substrate capacity ranks No.1 globally; Tianyue Advanced leads conductive SiC substrates with 27.6% global share and 51.3% of 8-inch SiC; Innoscience's GaN power devices turn gross-margin positive for the first time; and Wolfspeed's bankruptcy restructuring reshapes global supply. This deep-dive covers China's complete third-generation semiconductor supply chain, FY2025 enterprise data, the 8-inch SiC technology roadmap, and 2026-2030 market forecasts.
2026 China Semiconductor Packaging and Test (OSAT) Industry: Market Size and Competitive Landscape Deep Research Report
The global OSAT market reached ~USD 48B in 2025. Mainland China holds ~30% of global capacity, forming the "Second Pole" alongside Taiwan. JCET ranks global 3rd, Tongfu 4th, Huatian 6th — together ~22-24% of global OSAT. Yet in CoWoS/HBM advanced packaging, mainland localization is under 5%. This report maps the global OSAT landscape, sub-segment localization rates, advanced packaging gaps, and equipment controls, with a 2026-2030 forecast.
2026 China MCU Microcontroller Industry: Market Size and Competitive Landscape Deep Research Report
Global MCU market in 2025 approximately US8 billion; ST/NXP/Microchip/Renesas/Infineon/TI six giants hold 80% globally. China MCU market approximately RMB 35 billion, 32-bit exceeding 70% share, domestic localization rate approximately 20%, automotive-grade under 5%. GigaDevice GD32 cumulative shipments exceed 2 billion units, Espressif ESP32 global Wi-Fi MCU share over 30%; automotive-grade localization is the deepest moat, RISC-V + AI MCU is the next battle.
2026 China Power Semiconductor Market Scale and Competitive Landscape: Deep Research Report
2025 global power semiconductor market ~USD 60B; China ~USD 25B (42%). Automotive IGBT domestic rate ~67%; Tianyue Advanced SiC substrates global #1 (27.6%); Wolfspeed bankruptcy; Starpower revenue RMB 4B; Innoscience GaN enters Nvidia supply chain. Triple drivers: NEV 800V SiC + PV IGBT + energy storage PCS.
2026 China Semiconductor Materials Industry (Silicon Wafers + Photoresist + Electronic Chemicals + Targets + CMP + Photomasks): Market Size and Competitive Landscape Deep Research Report
Semiconductors are called the "oil" of modern industry, yet the true bottleneck rarely sits with the chips themselves — it lies in the ultra-pure materials that make chip fabrication possible. Silicon wafers, photoresists, electronic chemicals, sputtering targets, CMP polishing materials, photomasks, and packaging substrates: each of these sub-sectors has its own technological barriers, and each is a battlefield where Chinese industry is pushing hard for domestic substitution.
China Electronic Specialty Gases 2026 — Semiconductor Localization Breakthrough at the Critical Chokepoint
Electronic specialty gases are strategic consumables in semiconductor manufacturing, with prices multiples of gold by weight. In 2026, two major Japanese WF6 suppliers permanently exited due to China's tungsten export controls, handing China the fastest single-category global share restructuring in ESG history. This report covers NF3/WF6/SiH4 category dynamics, 8 A-share listed companies, three-tier localization progress, and a 5-year trend analysis anchored to June 18, 2026.
China Machine Vision Core Components 2026 — Localization Map for Industrial Cameras, Lenses, Light Sources, and Frame Grabbers
A comprehensive 2026 analysis of China machine vision core components—industrial cameras, optical lenses, LED light sources, frame grabbers, and 3D vision modules—covering market sizing, a four-tier localization map, key players, and technology trends across the full supply chain.
China Semiconductor Photoresist 2026 — A Five-Generation Climb from i-line, KrF, ArF to EUV
A comprehensive deep dive into China's semiconductor photoresist industry: five-generation technology evolution (g-line/i-line/KrF/ArF/EUV), Japan's global monopoly, domestic breakthroughs by Nanda Optoelectronics, Tongcheng/Beijing Kechuang, and peers, plus the 2026 localization roadmap and risk assessment.
China EDA Software Industry 2026 — From Synopsys Triopoly to the Domestic Trio of Empyrean, Primarius & Broadway Tech
A comprehensive analysis of the global EDA triopoly's dominance, the technical roadmaps and financials of China's leading domestic EDA companies (Empyrean, Primarius, Broadway Tech, Xinyuazhang), the impact of US export controls, Big Fund III catalysis, AI-EDA trends, and the realistic progress of domestic substitution with a 2030 outlook.
China's Industrial Tape 2026 — The Localization Climb from Release Films to High-End OLED Membrane Materials
A systematic review of China's industrial tape industry covering PSA tape, release films, OCA optical adhesives, and OLED process films — mapping the supply chain, competitive landscape, domestic substitution trajectory, and structural opportunities through 2028.
China PCB Substrate CCL Copper Clad Laminate 2026 — From General FR-4 to High-Frequency, High-Speed and Package Substrate Breakthroughs
Deep research on the global CCL copper clad laminate market in 2026: AI server-driven high-speed CCL boom, Shengyi M9 NVIDIA certification breakthrough, ABF substrate supply gaps, domestic substitution tiers and M&A landscape.
China MEMS Sensors 2026 — From Consumer Acoustics to Industrial Inertia: A Dual-Track Domestic Breakthrough
An in-depth analysis of China's MEMS sensor industry covering acoustic, inertial, pressure, RF, optical, and bio-MEMS categories: global competitive landscape, domestic substitution tiers, supply chain depth, key player profiles, investment trends, and 2026–2030 forecasts grounded in data from 4.8 million factories.
China Electronic-Grade High-Purity Silicon Chemicals 2026 — Closing the Loop on TEOS, HMDS and Polysilicon Precursors
A comprehensive deep dive into China's electronic-grade silicon-based chemicals industry across eight product categories (TEOS, HMDS, high-purity polysilicon, silane coupling agents, D4, high-purity quartz sand, electronic-grade SiO2, and silicone gels): global landscape, supply chain structure, investment analysis, domestic-substitution profiles, and future trends.
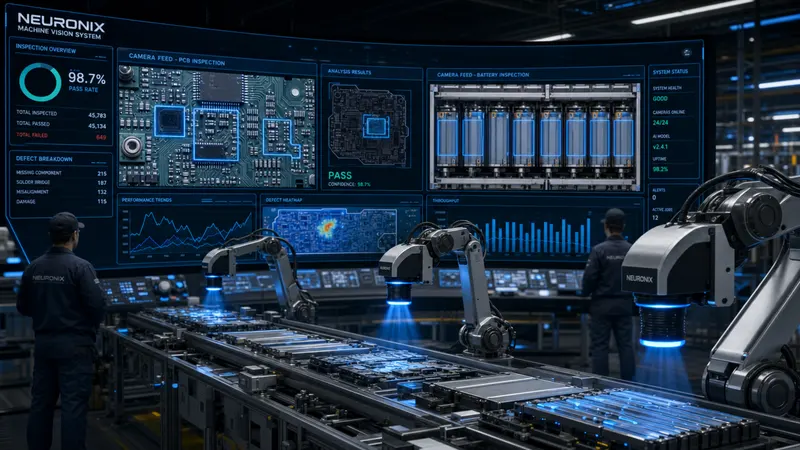
China Machine Vision Algorithm SDK 2026 — From HALCON Dominance to VisionMaster's Domestic Rise
An in-depth analysis of China's industrial machine vision SDK market: from HALCON's historical dominance to the rise of domestic SDKs like VisionMaster and VisionWARE, covering FY2025 financial data, AI vision emerging scenarios, business model evolution, and 2030 forecasts.
China Semiconductor CMP Pad and Slurry 2026 — From DuPont Monopoly to Dual Domestic Substitution by Dinglong and Anji
A comprehensive 2026 analysis of China's semiconductor CMP polishing pad and slurry industry: DuPont's global dominance, Dinglong and Anji Microelectronics' domestic substitution progress, SiC CMP emerging markets, policy tailwinds, and investment outlook. Data current through June 20, 2026.
China High-Purity Metal Sputtering Targets 2026 — Domestic Breakthrough from Semiconductor Cu/Al Targets to Display ITO
Sputtering targets are the core PVD consumables for semiconductor, display, and photovoltaic manufacturing. This report systematically analyzes the global landscape, domestic substitution progress, and competitive positioning of key players across Cu, Al, Ta, W, Ru, and ITO categories, anchored to the latest 2026 data.
China High-End Connectors 2026 — Domestic Breakthrough Driven by AI Servers and EV Powertrains
In 2026, China's high-end connector industry stands at a historic inflection point: NVIDIA GB200/GB300 AI computing rack 224G high-speed interconnect demand, 800V EV liquid-cooled high-voltage connector deployment at scale, and defense procurement recovery are collectively accelerating domestic substitution from consumer electronics into premium connector segments. This report covers 14 dimensions and presents three core judgments and a systemic risk framework.
China Wafer Foundry 2026: Mature-Node Expansion Wave and Advanced-Node Breakthrough
In 2025 mainland China wafer foundry approached RMB 200B revenue, 1.2M 12-inch wpm, utilization 90%+; SMIC's USD 9.3B revenue lifted it to global #2; N+2/N+3 serves Huawei Kirin and Ascend. This 14-chapter report covers industry overview, node breakdown, process barriers, key players, capacity, advanced-node breakthrough, supply chain, price war, capex, policy, customer structure, scenarios and risks.
China Memory Chip 2026: DRAM, NAND Twin Breakthrough and HBM On-Board
A full-landscape research on China memory chip industry 2026 — YMTC NAND, CXMT DRAM, domestic HBM, and module ecosystem advancing in parallel; generation gap and breakthrough paths versus SK Hynix, Samsung, Micron, Kioxia. Fourteen chapters of in-depth analysis.
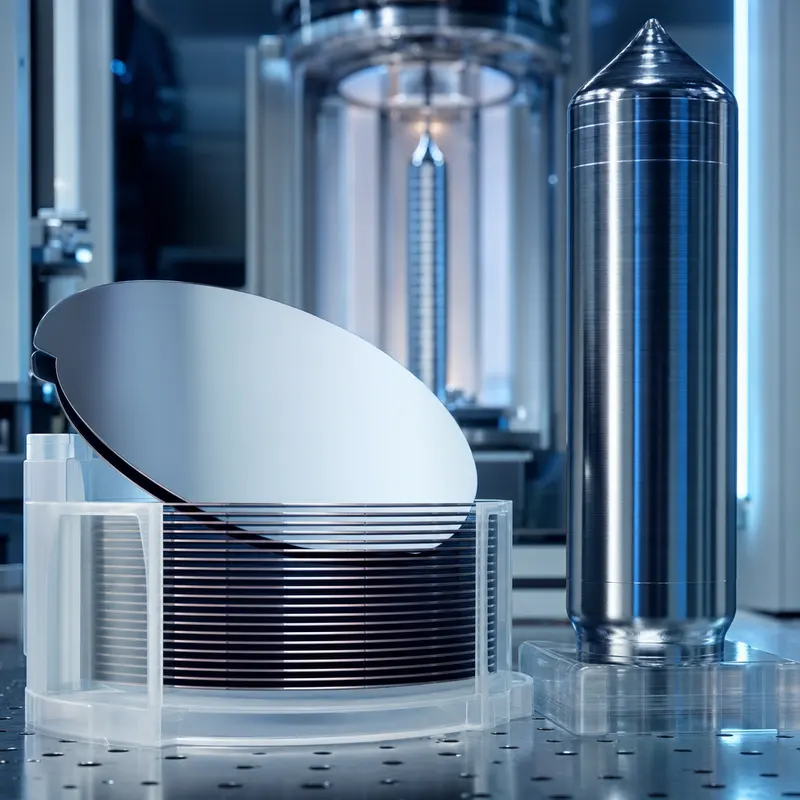
China Semiconductor Silicon Wafer 2026 — The 300mm Localization Push
2026 China semiconductor silicon wafer deep research: USD 13.6B global market with five oligopolies at 90% share; Shin-Etsu/SUMCO/GlobalWafers/Siltronic/SK Siltron vs NSIG/Sien/TCL Zhonghuan Lingxian/GlobalWafers-China/Beijing Yanyu Semiconductor; 300mm polished localization 35%, epi only 15% still bottleneck; electronic-grade 11N polysilicon, 72-hour CZ pull, zero-tolerance CMP; SUMCO 15% epi hike in 2026; Big Fund Phase III RMB 344B; 2030 55% composite localization path.
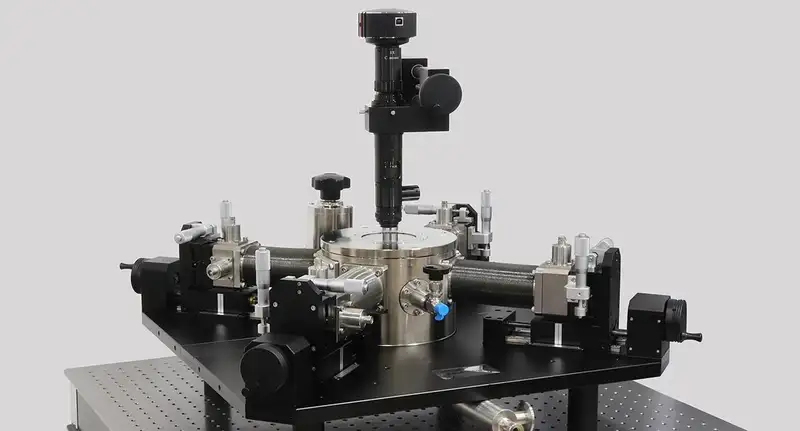
China Semiconductor Test Equipment 2026: SoC ATE and Probe Station Localization Push - Market Size and Competitive Landscape Deep Research Report
2025 global semiconductor test equipment market reached about USD 9 billion; mainland China 32% (USD 2.9B) at 28% localization. Analog and power 62/56% localized; high-end SoC ATE only 4%, HBM test 2%. Changchuan, Hwatsing, Jingce, Xinyichang combined CNY 8B 2025 revenue. Report dissects 6 ATE sub-segments, 7 process moats, customer groups, capacity expansion, price cycle, export controls; gives 2026-2030 path to 50% localization.
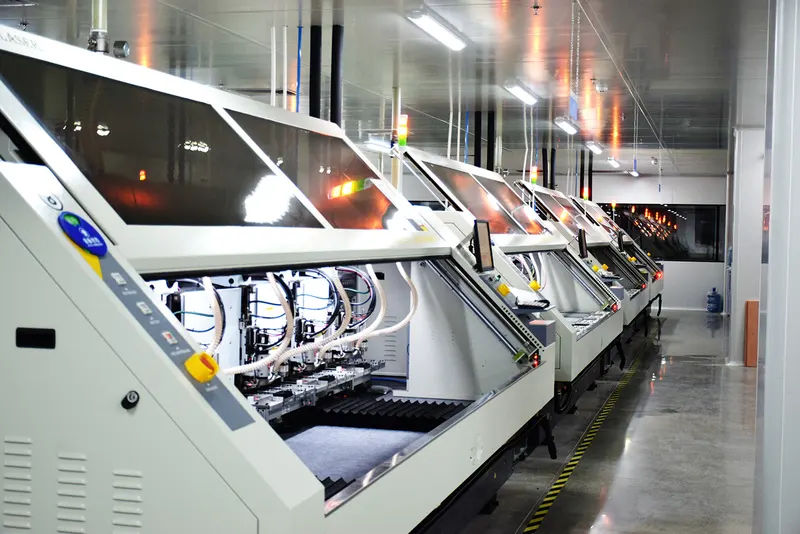
2026 China PCB Equipment Industry: Market Size & Localization Substitution
A research-institute report on China PCB equipment 2026: mechanical and laser drillers, LDI direct-imaging exposure, wet lines and AOI. Benchmarks Han's CNC, Dingtai Hi-Tech, Dongwei, Suzhou Tianzhun against Schmoll Maschinen, Hitachi ViaMechanics, Mitsubishi, Posalux, Orbotech, with a 2026–2030 outlook.
China's Display Panel Industry 2026: From 'Screen Famine' to Global Dominance—A Counter-Cyclical Comeback and the Last Fortresses at the High End
In 2012, China imported USD 50.3 billion of LCD panels—its fourth-largest import after chips, crude oil and iron ore: the 'screen famine.' A decade later, mainland China supplies about 95% of the world's LCD panels, BOE leads all five major categories, and panel revenue share topped half in H1 2025 (52.1%). Powered by counter-cyclical investment and the Hefei model, China staged its most dramatic manufacturing comeback. Yet the high-end 'last fortresses' remain.