


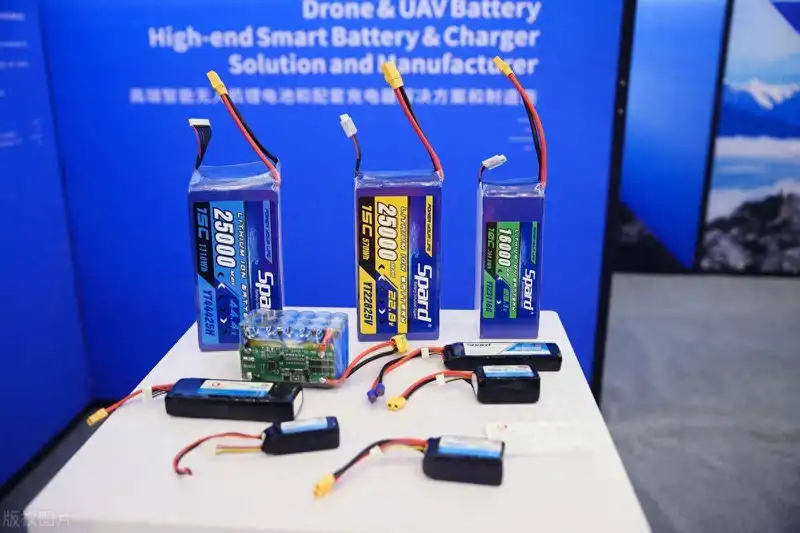
Sodium-Ion Battery 2026: How China Built the Industry's Second Card Alone After Lithium Crashed
From 2024 to 2025, foreign sodium-ion pioneers (UK's Faradion acquired by India, Sweden's Northvolt bankrupt, US's Natron shut down) collapsed almost entirely — while China's sodium-ion shipments grew from 0.7 GWh in 2023 to 3.7 GWh in 2024, then another 3.5 GWh in H1 2025, with energy storage taking 62%. This is a research-institute analysis on why the sodium-ion battery supply chain has consolidated to China and where it heads in 2026-2027.
China Lithium Battery Four Key Materials 2026: Market Scale and Competitive Landscape Deep Research Report
Deep-dive on China's four key lithium battery materials, updated through FY2025 annual reports. 2025 cathode ~5.03 million tonnes (+50%), output value ~RMB 274bn (+31%). Yuneng net profit +115%, Tianci net profit +181%, SEMCORP returned to profit. Lithium carbonate ~RMB 170,000/tonne by May 2026. Covers LMFP ramp, sodium-ion, semi-solid milestones, EU battery rules, and 2026-2030 forecasts.
2026 China Solar Module Industry: Market Scale and Competitive Landscape Deep Research Report
In 2024, China produced ~600 GW of solar modules — over 80% of global output — while the six major module giants combined for losses exceeding 140 billion RMB. Under the triple pressure of overcapacity, price floors (0.65 RMB/W), and overseas anti-dumping duties, the industry faces a war of attrition. This report analyzes technology route competition (TOPCon vs BC vs HJT), the integration vs. specialization debate, and the 2026-2030 outlook.
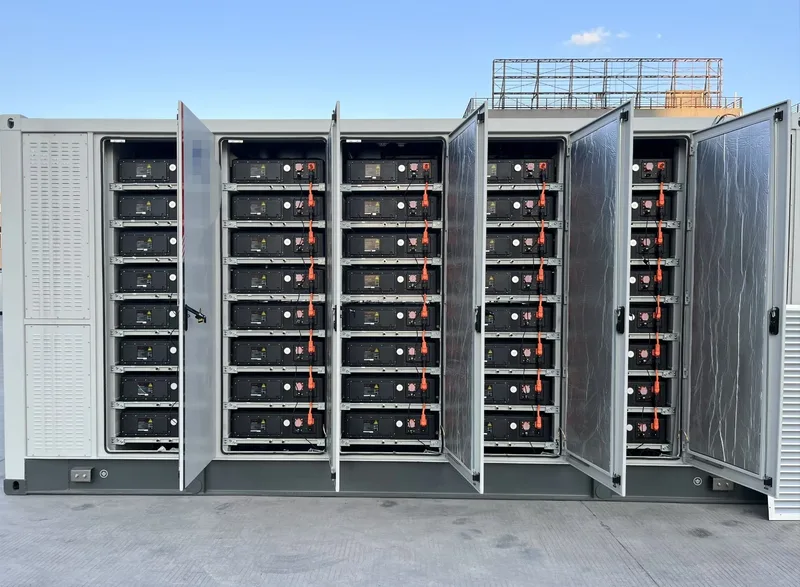
2026 China Energy Storage Industry: Market Size and Competitive Landscape Deep Research Report
China added over 80 GWh of new electrochemical storage in 2024, the most in the world; system prices fell from 1.3 yuan/Wh to 0.6 yuan/Wh; CATL and BYD lead cells while Sungrow and Huawei dominate PCS; standalone storage exceeded co-located for the first time. This report covers China's storage supply chain, competitive landscape, sub-segments, technology trends, and 2026–2030 outlook.
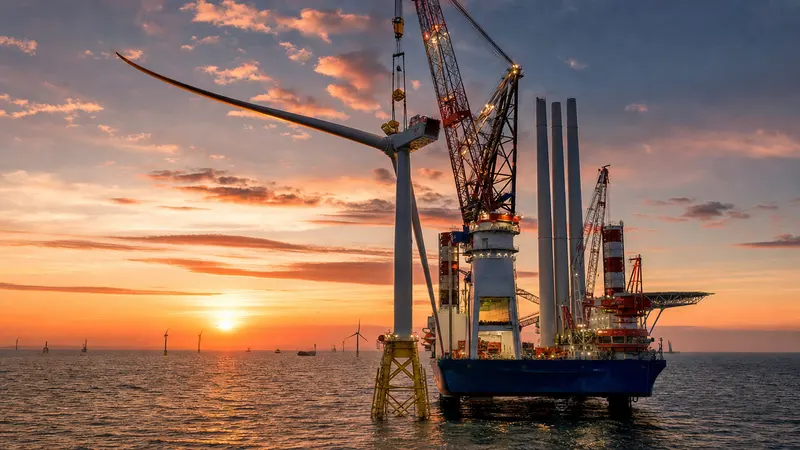
2026 China Wind Turbine Industry Market Scale and Competitive Landscape: An In-Depth Research Report
In 2024, China's newly installed wind power capacity reached approximately 87 GW, with cumulative installations of 520 GW accounting for half the global total. Chinese turbine makers claimed the top four global positions for the first time. Yet average turbine prices fell to a historic low of 1,381 yuan/kW, with turbine gross margins compressed to just 3–8%. This report examines three key variables—the onshore price war, offshore scale-up to 18MW→26MW, and accelerating exports—and maps the in...
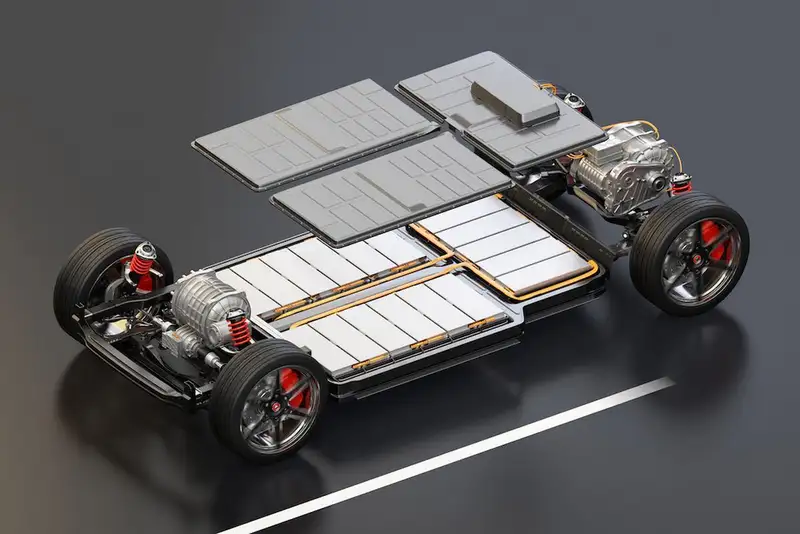
2026 China Power Battery Industry: Market Scale and Competitive Landscape Deep Research Report
In 2025, China EV power battery installation reached 769.7 GWh (world #1), LFP share 81.2%; CATL + BYD hold ~65% domestic share; Chinese firms surpassed 70% global share for the first time. This report covers the cell/module/Pack value chain, key company financials and technology, six major industrial clusters, semi-solid/sodium-ion/large-format cylindrical/CTC frontier topics, and a 2026-2030 five-year forecast.
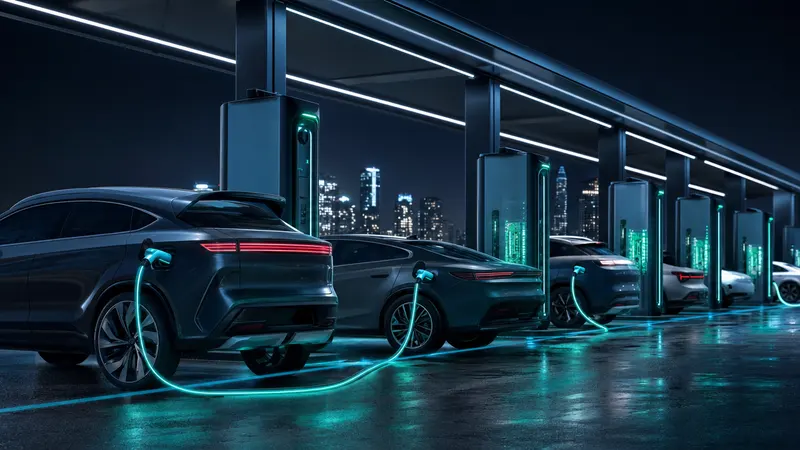
Supercharging Arms Race: 2026 China EV Charging Infrastructure Market Size and Competitive Landscape Deep Research Report
By end-2025, China's EV charging infrastructure installed base surpassed 20.09 million units — the world's largest. The supercharging arms race has restructured the value chain: Huawei launched a 1,440kW megawatt supercharger, and liquid-cooled modules have become the gating component for supercharger deployment. This report systematically covers the 2025–2026 China EV charging market: size, competitive landscape, industrial clusters, and 2030 outlook.
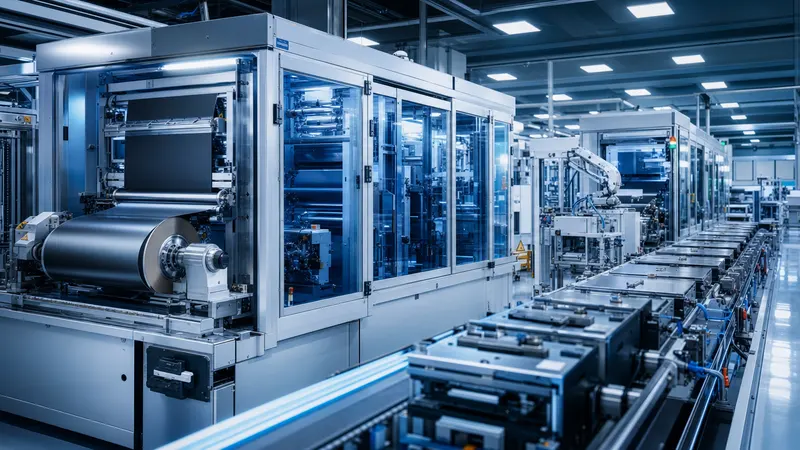
Battery Equipment: The Hidden Backbone of Chinese Manufacturing (2026 Deep Research Report)
China's lithium battery equipment market reached approximately RMB 800–900 billion in 2025. After the 2024–2025 trough, recovery is now underway in 2026. Pioneer Intelligent leads globally; Hymson Laser holds the high ground in laser welding; Hangke Technology anchors the back-end formation and grading segment. Solid-state battery pilot lines and overseas factory orders are reshaping this sector's competitive landscape.
2026 China Hydrogen Energy Deep Research Report: Green Hydrogen, Fuel Cells, and Storage-Transport Full Landscape
China is the world's largest hydrogen producer at ~35 million tonnes/year, but 97%+ is grey hydrogen. In 2025, renewable green hydrogen in operation reached ~250,000 tonnes/year, fuel cell vehicle fleet stood at ~30,000, and 560 hydrogen refuelling stations were built. Cost, infrastructure, and commercial loops — three gateway bottlenecks — are determining the pace of China's journey from planning powerhouse to industrial leader.
The Rare Earth Chain: 2026 Deep-Dive Research Report on China's Rare Earth Permanent Magnets and Permanent Magnet Motors
China's April 2025 export controls on seven heavy rare earths and Tb/Dy-containing NdFeB magnets triggered a 40%+ PrNd price rebound. JL MAG net profit +142%, Zhongke Sanhuan +661%. This FY2025 report covers NdFeB and SmCo magnets plus permanent magnet motors across NEVs, wind, servo, appliances, and humanoid robots — analysing market size, competition, technology evolution, risks, and a 2026–2030 outlook.
China Wind Power Components Deep Report 2026: Blades · Towers · Main Shafts · Flanges · Gearboxes · Offshore Monopiles · Wind Power Castings
A comprehensive analysis of China's seven core wind power component segments (blades, towers, main shafts, flanges, gearboxes, offshore monopiles, and castings) covering 2025 market size, technology evolution, and competitive landscape of leading enterprises including SINOMA, Riyue, and Oriental Cable, with a 2026-2030 outlook.
China Carbon Fiber 2026: From Wind Blades to Large-Tow, Localization at the Crossroads
China's carbon fiber industry in 2025: 162,000 tonnes capacity, 96,400 tonnes consumption, over 80% localization, 60%+ global share in large-tow, profit per tonne at just 330 RMB. A 14-chapter map from precursor to wind blades, hydrogen tanks, aerospace, low-altitude, and robotics—analyzing the three-year high-end localization window and five-year competitive evolution.
China Submarine Cable 2026: Dual Drivers from Offshore Wind and Cross-Sea Interconnection
China Glass Fiber 2026: The Dual Front of Wind Yarn and Electronic Yarn
In 2026 Owens Corning formally completes its global Glass Reinforcements divestiture; the industry enters a China-dominant, Japan-specialty two-pole era. China's yarn output reaches 8.43M tons (~70 percent global). Wind yarn is pulled by offshore scale-up; electronic yarn and cloth enter a decade-tightest shortage on AI compute demand. This report covers furnace scale-up, generations, corporate landscape, substitution, cycles, policy, and risks.
2026 China High-Purity Quartz Sand: Twin-Track Battle in PV Crucibles and Semiconductor Quartz
From RMB 300,000 to 50,000 per tonne in three years — the price cliff masks a twin-track divergence: PV-grade 4N8 has cleared substitution while 5N semiconductor-grade remains 95% import-dependent. This research institute report dissects ore sources, processing barriers, manufacturers, pricing, policy and risks for a 3-to-5 year industry framework.
China Polysilicon 2026 — Top-Tier Cost Discipline and the N-Type Granular Breakthrough
Deep 2026 research on China polysilicon: 3.2M tonnes capacity vs 1.1M demand (2.9x oversupply); prices crashed from RMB 300K to 40K/tonne; Tongwei, GCL, Daqo, Xinte, Asia Silicon vs Wacker, Hemlock, OCI in N-type era; granular share rises to 24%; USD 5B integration fund; Oman/Indonesia/Malaysia overseas bases; EU CBAM and green silicon; 'four-plus-two' 2030 forecast.
China Electrolytic Copper Foil 2026: The 4.5μm Ultra-Thin and HVLP High-Frequency Dual-Track Breakthrough
China's electrolytic copper foil industry enters 2026 recovery: 2.07 million tons capacity; Jiayuan hit a record 9.64 billion yuan in 2025 while Norde posted a second 260 million yuan loss; 4.5μm lithium foil 100% localized, 4μm under attack, HVLP-3/4 still choked. This report maps the process chain, six Chinese leaders vs four overseas giants, power battery + AI server dual downstream, the composite foil threat, and 2026-2030 supply-demand projections.
China PV Encapsulation Film 2026 — From Transparent EVA to POE Co-Extrusion for the N-Type Upgrade
Deep 2026 research on China PV encapsulant: 8B m² global demand vs 5.2B m² China capacity; EVA transparent prices fell from RMB 22 to 8.8/m²; Foster, Hiuv, Cybrid, Sveck vs Mitsui, Bridgestone, 3M; EPE co-extruded share from 3% to 30%; N-type TOPCon and HJT drive POE/EPE adoption; POE 75% controlled by Dow, ExxonMobil, Mitsui with Wanhua, Satellite breaking through; CBAM, UFLPA, IRA triple policy battle; 2030 ten-trend outlook.
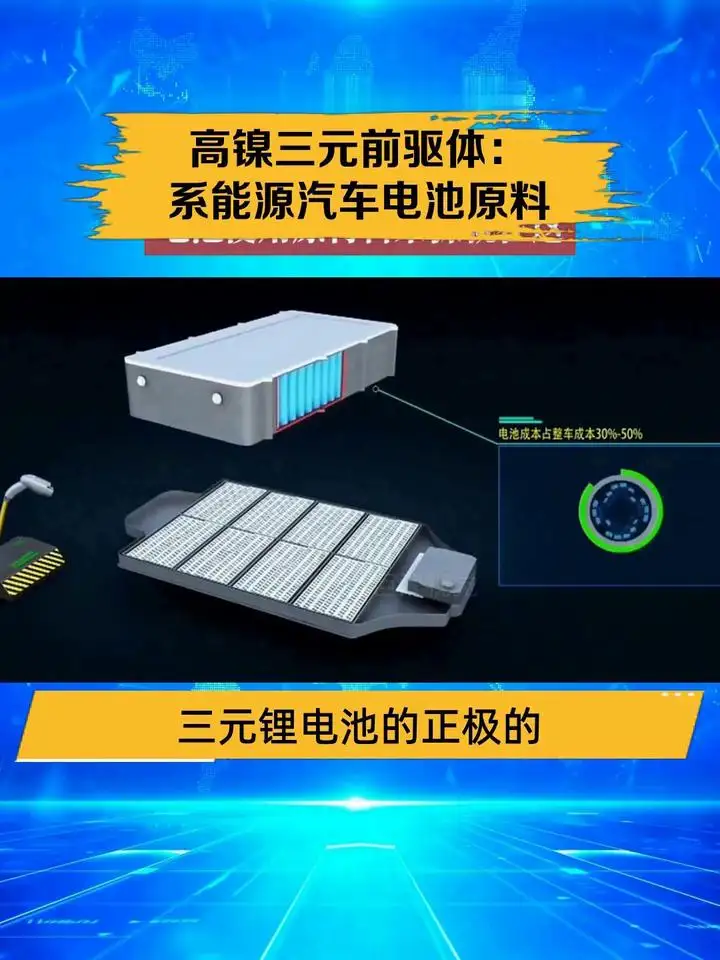
China Ternary Precursor 2026 — Nickel-Cobalt-Manganese Integration and the Global Resource Race
2026 China ternary precursor: shipments 88 kt (84% global), CR3 76% (CNGR 33 + Huayou 18 + GEM 16). NCM811 processing fee at floor ¥8500/t; high-nickel single crystal + NCMA + solid-state adaptation drive premium. Indonesian HPAL Ni 45 kt, DRC cobalt + EOL recycling 380 kt; CBAM + IRA reshape global flows. 14 chapters.
Tides of White Oil: 2026 Deep-Dive Research Report on China's Lithium Carbonate Industry
In Nov 2022 China's battery-grade lithium carbonate spiked to RMB 600,000/t; 21 months later it collapsed to RMB 72,000 — an 88% drop. By June 2026 the price hovers around RMB 100,000. China produced 780 kt LCE of carbonate and 360 kt of hydroxide in 2025, over 60% of global supply. This report covers the upstream-midstream-downstream chain across 14 chapters.
China's Solid-State Battery Supply Chain (2026): Order Opportunities Along the Materials and Equipment Tracks
Global solid-state battery shipments reached 5.3 GWh in 2024 — all semi-solid-state; in 2026 semi-solid-state vehicle installations are scaling up and leading battery makers' all-solid-state pilot lines are landing in clusters, while lithium sulfide still costs over RMB 3 million per tonne and all-solid-state equipment investment per GWh runs 2–3x that of liquid-electrolyte lines — procurement windows on both the materials and equipment ends are opening at the same time.
China's Green Hydrogen and Electrolyzer Equipment Industry (2026): 3 GW of Tenders, 58 GW of Capacity, and the Upstream Order Map
China's domestic electrolyzer tenders reached 3.02 GW in 2025 against roughly 58 GW of nameplate capacity, with extreme alkaline bids down to about RMB 375/kW — this report translates the green hydrogen mega-base boom into an order map for upstream suppliers of diaphragms, electrodes, and rectifier power supplies.
China's Power Battery Industry 2026: One Battery Behind Many World Firsts, and Its Threefold Siege
In 2026, CATL leads the world for a ninth straight year (39.2% share), BYD is second, six Chinese firms sit in the global top ten, and Chinese makers hold about 69% of the world EV-battery market. Yet precisely because it is so strong, it faces a threefold siege: external regulatory encirclement (US IRA/FEOC and tariffs, EU battery law), an upstream resource chokepoint (70% of lithium imported), and internal overcapacity. This report dissects the peak and the predicament.
China's Power-Battery Recycling 2026: The First Year of Binding Rules, and a Disordered Urban Mine
On 1 April 2026, MIIT Order No. 73, issued jointly by six ministries, took effect, giving power-battery recycling in China its first binding regulation. It confronts a peculiar industry: whitelisted firms hold nominal capacity counted in millions of tonnes yet process only a fraction of it, and roughly eight in ten scrapped electric vehicles arriving at licensed dismantlers have no battery. This is not an industry short of capacity, but one short of order.