


China's Coatings Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's coatings industry in 2026: nearly 35 million tonnes produced a year and first worldwide for 15 straight years, yet a textbook large-industry-of-small-companies where the top ten hold only about 21.7% and foreign brands dominate the high end. Raw materials (resins, titanium dioxide) make up 80-90% of cost. Architectural coatings are dragged down by the property downturn and a wave of project bad debt, while industrial coatings have risen to about 66%.
China's Modified Plastics Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's modified-plastics industry in 2026. Modified plastics tunes base resins into high-performance materials, where value lies in formulation and additives. China makes about 29.75 million tonnes a year, yet its modification rate is only about 25%, less than half the global level (about 50%) and the core room for growth. The market is highly fragmented: CR3 about 14%, Kingfa only about 7.86%, over 10,000 firms.
China Steel Industry 2026: Market Scale, Competitive Landscape & Deep Research Report
China produced 1.005 billion tonnes of crude steel in 2024 (53%+ of global output), with steel exports at 110.7 Mt — near-record. Industry profits fell 90%+ from 2021 peak as real estate contraction, overcapacity, and anti-dumping waves collided. Covers Baowu/ArcelorMittal/Nippon Steel competition, supply-demand balance, supply chain, eight companies 2024 financials, rebar/auto-sheet/special-steel segments, EAF and hydrogen decarbonization roadmap, 2026-2030 output and carbon forecasts.
2026 China Chemical New Materials Industry: Market Scale and Competitive Landscape Deep Research Report
China's chemical new materials market is approximately RMB 1 trillion; overall domestic substitution rate is ~70%. Advanced photoresist remains below 5% localised. Wanhua MDI anchors the base while Yake and TongCheng crack open ArF photoresist. Strategic bottleneck materials localisation is entering a new phase.
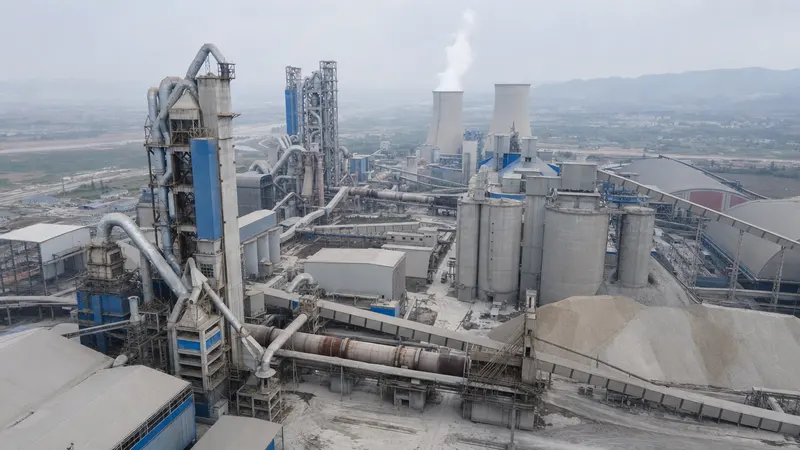
China Cement Industry 2026: Market Size and Competitive Landscape Deep Research Report
China's cement output reached approximately 1.69 billion tonnes in 2025, down over 30% from the 2014 peak of 2.495 billion tonnes. This report systematically covers the global landscape, China market scale, full value chain, and key companies (Conch Cement, Huaxin Cement, Tianshan Shares, China Resources Building Materials, Jinyun Jidong), with analysis of the 2026–2030 consolidation, overseas expansion, and carbon neutrality themes.
Copper vs. Aluminium: 2026 Deep-Dive Research Report on China's Non-Ferrous Metals Industry
In 2025, LME copper peaked above USD 12,000/tonne — best year since 2009 — while China's refined copper broke 14 million tonnes and electrolytic aluminium held near the 45-million-tonne policy ceiling. Against the triple overlay of AI infrastructure, grid upgrades, and EV acceleration, non-ferrous metals face structural demand revolution. This report covers copper, aluminium, lead-zinc, nickel, tungsten, molybdenum, and rare earths through a 2026–2030 outlook.
Four Faces of Glass: Solar Overcapacity, Float Bottoming, Fuyao's Monopoly, and Electronic Breakthrough (2026 Deep Report)
China produces enough glass each year to cover the entire island of Hainan. But behind the word 'glass' lie four completely different stories: solar glass trapped in the most brutal price war in its history; float glass bottoming out alongside real estate; a Fujian company quietly capturing one-third of the global automotive glass market; and electronic glass substitution, inch by inch prying open an iron curtain long held by Corning and AGC.
2026 China Industrial Gas Industry In-Depth Report: Bulk Gases, Electronic Specialty Gases and On-Site Production in a Three-Track Race
China's industrial gas market exceeded RMB 200 billion in 2025, with electronic specialty gas localization rising from ~5% in 2020 to ~25%; semiconductor fab expansion, hydrogen energy supply chains and CCUS pilots form three demand engines. The global triad of Linde, Air Liquide and Air Products still controls over 60% of the China market, while domestic four horsemen — Hangyang, Guanggang Gas, Huate Gas and Nanda Optoelectronics — press forward on systematic catch-up.
2026 In-Depth Research Report on China Paper Industry Market Scale and Competitive Landscape (Pulp + Paper Products + Packaging + Specialty Paper)
Based on FY2025 annual reports and 2026 Q1 data, this report comprehensively analyzes China paper industry capacity of 121.05 million tonnes, competitive dynamics among leaders Nine Dragons/Sun Paper/APP, specialty paper import substitution progress, and 2030 strategic outlook.
2026 China Building Ceramics and Sanitary Ware Deep Research: Competitive Landscape of Tiles, Sanitary Ceramics, Bathroom Hardware, and Smart Toilets
China is the world's largest building ceramics producer, with annual tile output of approximately 5.91 billion square meters — over half of global production — and a full sanitary ware value chain of approximately 600–700 billion RMB. Overseas expansion, rock slab premiumization, and smart toilet adoption are the three new growth engines. Dongpeng, Marco Polo, JOMOO, and HEGII lead domestically; Kohler, TOTO, and Geberit mine China's premium segment.
2026 China Flexible Packaging Materials (BOPET + BOPP + Laminated Film + Food-Grade Aluminum Foil + Lithium Battery Aluminum-Plastic Film): Market Size and Competitive Landscape Deep Research Report
Deep research on China's flexible packaging materials: 2025 market size approx. RMB 500-550 billion, BOPET capacity near 7 million tons, BOPP over 4.5 million tons, lithium battery aluminum-plastic film domestic production exceeding 60%, Amcor-Berry Global merger reshaping global dynamics. Analysis of 11 Chinese listed companies and global giants' FY2025 results, covering five sub-tracks and 2030 outlook.
2026 China Refractory Materials Industry Deep Research Report (FY2025-2026H1)
A systematic analysis of China's refractory materials industry covering market scale, competitive landscape, supply chain structure, and global dynamics: 2025 output of 21-22 million tonnes, product-side revenue of approximately 56.3 billion yuan; the industry's core logic is shifting from 'selling products' to 'selling capabilities,' with ICM integrated contracting accelerating penetration and leading companies diverging sharply.
China Superhard Materials 2026: A Full-Spectrum Analysis of Synthetic Diamond, Lab-Grown Diamond, CBN and Industrial Coatings
A comprehensive analysis of China's superhard materials industry: from the price cycle of industrial diamond and lab-grown diamond to the rise of CVD diamond heat spreaders and quantum materials, covering market scale, FY2024 financials of leading companies, a nine-stage value chain breakdown, and five structural forecasts for 2026–2030.
China Industrial Adhesives Industry 2026 — Sub-Segment Localization from Silicones to Lithium Battery Structural Adhesives
A systematic overview of China's industrial adhesives industry in 2026: seven chemical systems, six functional categories, and a domestic substitution matrix across all sub-segments, with focus on the three frontier areas — lithium-battery thermal adhesives, automotive BIW structural adhesives, and OCA optical adhesives. Includes financial and strategic analysis of Huitian New Materials, Guibao Technology, and other leading domestic players.
China PEEK & High-Performance Engineering Plastics 2026 — From Victrex Dominance to a Three-Pillar Domestic Breakthrough
From ICI's 1978 PEEK synthesis to China's 2026 thousand-tonne domestic production, this report maps the global competitive landscape, industrial chain value distribution, player financials, and domestic substitution progress across PEEK, PI, PPS, LCP, and PEI.
China Industrial Ceramics 2026 — From Alumina and Silicon Nitride to Semiconductor Wafer Carrier Breakthroughs
A comprehensive 2026 research report on China's advanced ceramics industry, covering alumina, silicon nitride, aluminum nitride, silicon carbide, and sapphire material systems; semiconductor electrostatic chucks and wafer carriers; power module substrates; 5G filter ceramics; domestic substitution progress; and Tianxia Gongchang factory database insights.
China Superalloys and Single-Crystal Turbine Blades 2026 — The Last Mile of Aero-Engine Localisation
A full-spectrum analysis of China's superalloy and single-crystal turbine blade industry in 2026: localisation milestones from DD6 to DD9, powder metallurgy turbine discs, thermal barrier coatings, and structural opportunities across the five-year outlook.
China Fluorochemicals 2026 — Refrigerant Quotas Capped and the Fluorinated New-Materials Breakthrough
Fluorochemicals connects fluorspar mines to new-energy, semiconductors, hydrogen, and home appliances. After China's 2024 HFC quota system, R32 rose 4x to 110,000 yuan/ton; meanwhile fluoropolymers (PTFE/PVDF/FKM) and electronic fluorochemicals (LiPF6, EG-HF, PFSA membrane) are breaking through. Covers fluorspar resources, refrigerant generations, eight players, quota dynamics, new materials, policy, and 3-5 year outlook.
China Integrated Die-Casting 2026: The 9000T Mega-Press Wave and NEV Body Reconstruction
In 2025 China integrated die-casting structural-parts market crossed thirty billion yuan; close to twenty 9,000-ton mega presses now installed; 16,000-ton class running at XPeng P7+ and Hongtu Guangzhou. A 14-chapter picture from heat-treatment-free alloy, mega molds, mega presses to Tier1 casters and OEM programs — localization milestones, the economic argument, insurance and crash dynamics, and the five-year landscape evolution.
China Titanium Alloy 2026 — Domestic Breakthrough in Aerospace High-End Materials
Sponge titanium capacity 75% of global; aerospace titanium share jumped from <5% (2020) to 22% (2025); ~7 tons titanium per COMAC C919. But highest-end grades TC21, Ti60 still in engineering ramp; process database gap to VSMPO remains the core unfinished work. From midstream processing lens, this report unpacks Chinese titanium capacity, price cycle, process barriers, downstream map, import substitution, industry belt, and five-year key nodes.
2026 China Phosphate Chemicals: From Phosphate Rock to LFP Cathode — Industrial Chain Integration
Deep research on the 2026 China phosphate chemicals industry: covering rock, yellow phosphorus, industrial phosphoric acid, iron phosphate, LFP cathode, glyphosate, and fertilizer; analyzing Yuntianhua, Xingfa, Hubei Yihua, Chuanfa Longmang, Chuanheng vs OCP, Mosaic, Nutrien, PhosAgro, EuroChem; five structural shifts 2026-2030: integration, mining rights, new energy, green low-carbon, China-Morocco duality.
China Tungsten and Molybdenum Alloys 2026: Strategic Metals Across Cemented Carbide, Photovoltaic Tungsten Wire and High-end Equipment
A comprehensive analysis of China's tungsten-molybdenum alloys chain — from Jiangxi-Hunan tungsten and Henan-Shaanxi molybdenum, through APT/W-powder/cemented-carbide midstream, covering FY2025 results of China Tungsten & Hightech, Xiamen Tungsten, CMOC, Jinduicheng Molybdenum, Zhangyuan Tungsten with Sandvik/Plansee/Kennametal benchmarks, the APT price doubling to RMB 780K/ton, the Feb 2025 export controls, four emerging downstream applications, and five structural judgments for 2026-2030.
2026 China Polyurethane MDI Industry Research Report: Wanhua Integration and Global Pricing Power
2026 China Polyurethane MDI industry report. From 2025 global MDI/TDI oligopoly, Wanhua integration, upstream aniline and PO chain, downstream rigid/flexible foam and CASE TPU, to 2024-2026 price cycle, policy, and 2026-2030 outlook with risks.
China Titanium Dioxide 2026 — Chloride Route Replacing Sulfate and Global Export Pricing Power
Deep 2026 research on China TiO₂: 9.4M t global capacity vs 7.45M demand; China 64% of output, 51% of exports; CR5 58%, chloride 31%; Longbai Jiaozuo 500K-t chloride line pushes cash cost to RMB 10800/t; 2.07M t exports vs global AD encirclement; ilmenite Africanization accelerates; EU PFAS+CBAM + China dual-control; industry margin recovers from 20.1% to 27% by 2030.
China Dyes & Pigments 2026 — Oligopoly in Disperse/Reactive and High-End Pigment Breakthrough
Deep 2026 research on China dyes and pigments: 1.1M-t output at 60% global share; Longsheng/Runtu/Jihua disperse CR3 60%+; Runtu H acid self-sufficiency 80%; Lily/Caihong high-end pigment localization (DPP, quinacridone); reduction-product 300% surge driving Q1 2026 rebound; EU PFAS+ZDHC+REACH compliance reshaping; 2027-2030 consolidation outlook.
China Chlor-Alkali and PVC 2026 — Carbide vs Ethylene, and the Western Energy Arbitrage Rewriting Industrial Geography
Chlor-alkali is China's largest inorganic chemical subsector: 52 Mt caustic and 29.2 Mt PVC capacity in 2025 (47% and 40% global). This report covers electrolysis, carbide vs ethylene battle, Western energy arbitrage, 12 key players, caustic and PVC downstream maps, price cycles, EU CBAM and anti-dumping dynamics, and 3-5 year outlook.
China Special Steel 2026 — High-End Import Substitution in Bearing and Tool & Die Steel
Deep 2026 research on China midstream special steel: 84M-tonne output, purity migration, large-forging competence, the 3-to-5-year high-end substitution window; CITIC, Fushun, Baowu Tegang, Northeast, Xining, Daye vs Voestalpine, Tata, Sandvik, NSSMC, Daido, SeAH; GCr15 bearing and H13/718H/SKD11/SKH-9 die-steel downstream mapping; four-tier high-end tiers and pacing.
China Copper Smelting 2026 — The Race for Overseas Copper Mines and Global Cathode Pricing Power
2026 China copper smelting: cathode 13.64 Mt (47% global); concentrate dependency 78%; TC/RC at -$8/ton; LME on $10,000 plateau. Six leaders — Jiangxi Copper, Tongling, Zijin (Kamoa + Julong), China Molybdenum (KFM + Tenke), Jinchuan, China Copper. 14 chapters: process, mining, midstream, three downstreams, expansion, cycle, dual-carbon, eight-drivers outlook.
China Aluminum Smelting 2026: Alumina Value-Chain Integration and the Electrolytic-Aluminum Green-Power Revolution
In 2025 China's electrolytic-aluminum output hit 43.7 Mt — 59.8 percent of global; operating capacity touched 44.2 Mt against the 45 Mt policy ceiling. Under the triple overlay of EU CBAM collection from Jan 2026, Guinea export-policy tightening, and super-linear NEV battery-foil demand, top producers keep migrating capacity to Yunnan hydropower aluminum. This 14-chapter report covers upstream bauxite, process, green-power replacement, recycled aluminum, capacity, prices, policy, and risks.
China Plastic Pipe Industry 2026 — The Three Resin Oligopolies (PPR, PVC, PE) and Overseas Penetration
Plastic pipes are the quiet workhorse of China's construction and municipal infrastructure. 2025 output 16.5 Mt (41% global), industry revenue RMB 258 bn. Covers PPR/PVC-U/PE/PEX/PB, extrusion and corrugated processes, Chinese leaders (Lesso, Weixing, Eric) versus global majors (Aliaxis, Wavin, Pipelife, Orbia, Georg Fischer), price cycles, export expansion, policy tailwinds, and the 3-5 year outlook.
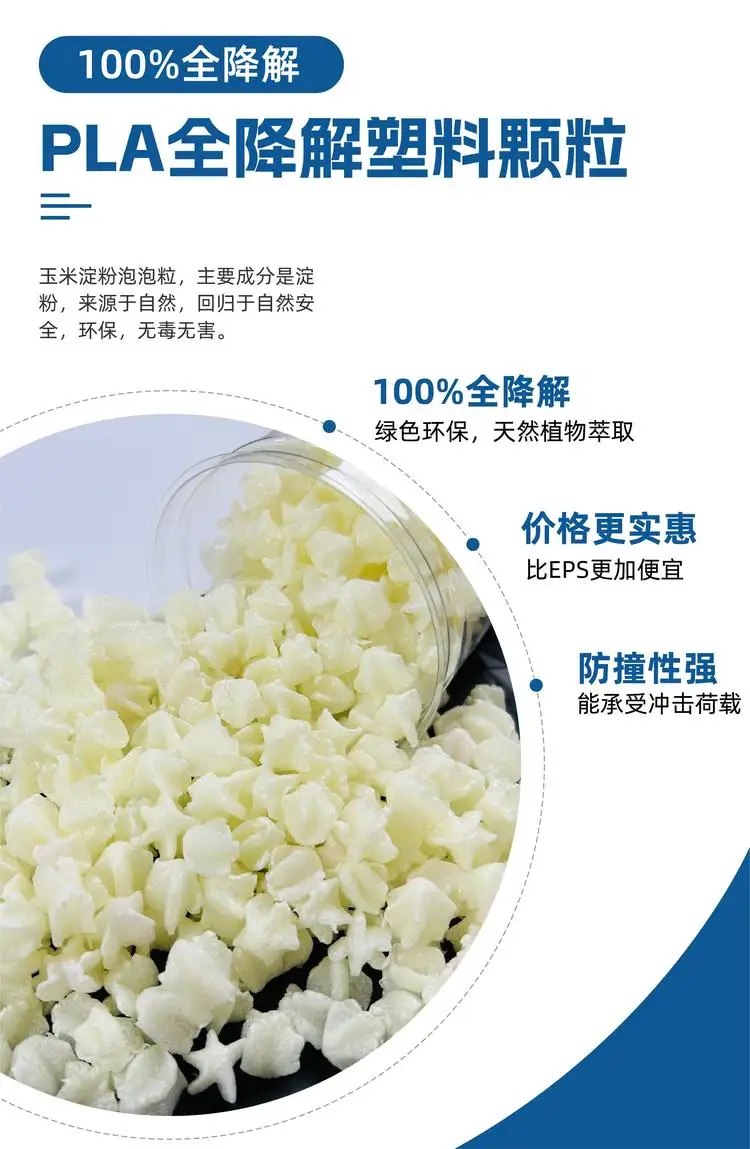
China Biodegradable Plastics 2026: PLA, PBAT, and the Capacity Showdown
A 2026 panoramic on the Chinese biodegradable-plastic industry: PLA and PBAT process routes, the standoff between 4.2 million tonnes of planned capacity and 36% utilisation, the Kingfa-Fengyuan-Hisun-NatureWorks-BASF map, single-use-plastic restrictions and capacity overhang, EU SUP and CBAM impact on exports.
China Specialty Paper 2026 — Decor Base, Food Packaging and the High-End Breakthrough
2026 deep research on China specialty paper: industry output ~5 mn t, top-two share ~50%; Xianhe 2024 revenue RMB 10.3 bn; Wuzhou H1 2025 revenue RMB 4.1 bn; Huawang decor base going global; Kane capacitor paper duopoly; EU PPWR + PFAS effective August 2026; 14 chapters on 2026-2030 global pathway.
China Industrial Aluminum Extrusion 2026: Dual-Engine Restructuring Driven by Automotive Lightweighting and Solar Module Frames
China industrial aluminum extrusion crossed 12.5M tons in 2025 (54% of total profile output), completing the inversion from construction-led to industrial-led. Solar frames 3.95M, NEV 1.4M, general 3.6M, rail body 480K. Under EU CBAM 2026, anti-dumping, export-rebate cut, and green-power push, leaders pivot to auto-structural and solar-frame engines. 14 chapters: billet, process, players, downstream, capacity, prices, policy, risks.
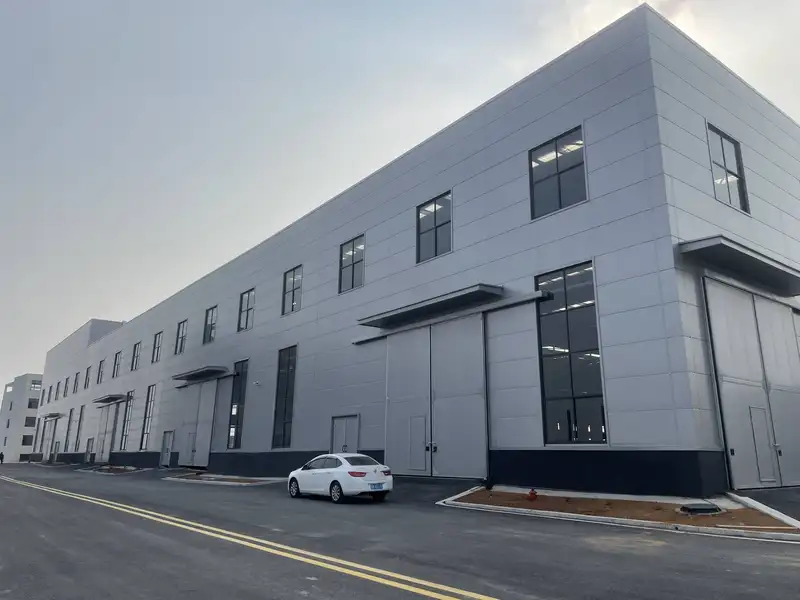
China's Prefab Steel Structure and Construction 2026 — Industrial Plants, Mega Venues, and Steel Bridges Reshaping the General-Contracting Tier
2026 China steel-structure and prefab-construction deep research: 132M-t output, 35.6% prefab share, CR10 9.4%; Honglu/Jinggong/Hangxiao/Southeast/Fuhuang/CRBC vs Nucor/Steel Dynamics/Tata/SSAB/Cleveland-Cliffs/ArcelorMittal Europe; fabs, lithium, data centres, EV assembly, cross-sea bridges, prefab housing, floating wind; CBAM + prefab plan + East-West Compute + BRI; 5-to-10-year consolidation window.
China Industrial Lubricants 2026: Great Wall and Kunlun Duopoly with Longpan Going Abroad
China consumed about 7.7 Mt of lubricants in 2025; Sinopec Great Wall and PetroChina Kunlun together hold about 38%, while Lubrizol, Infineum, Chevron Oronite and Afton still control over 91% of compound additives. This report dissects the 2025 market structure, API Groups I-V base oils, refining and blending, leading players, industrial and automotive categories, EV coolants, downstream factory identification, Longpan going abroad via Lubricos, capacity, pricing, policy and risk.
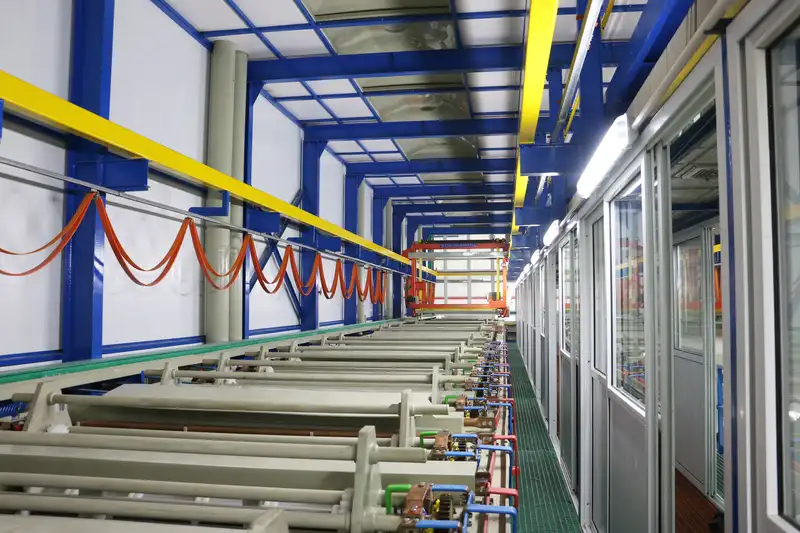
2026 China Surface Treatment Industry: Market Size & Competitive Landscape
The last stop for almost every industrial product is a plating tank, an anodizing line or a spray booth. Surface treatment never appears on the nameplate, yet it decides how long a product lasts. This report dissects the invisible industry: a RMB 180 billion plating services market, 40,000+ companies, some 160 centralized parks, two decades of environmental consolidation, the localization battle in chemistry, the copper foil bust, semiconductor plating growth, and a 2026-2030 outlook.
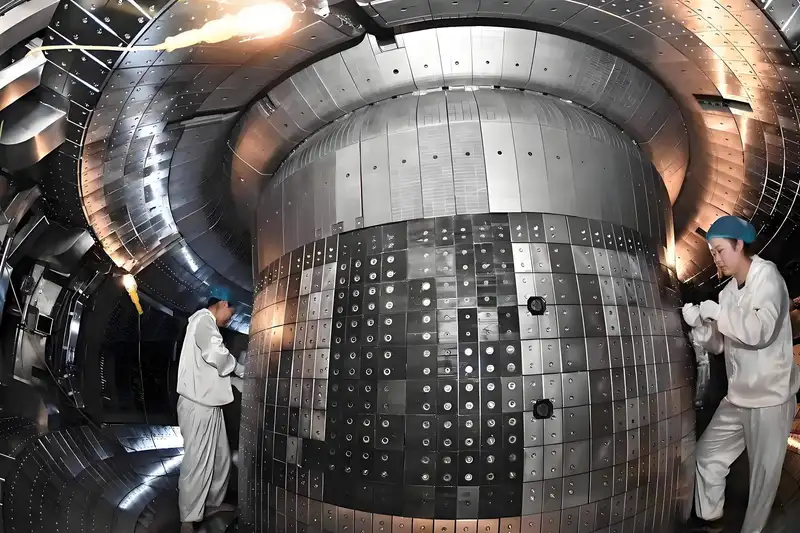
2026 China High-Temperature Superconductor Industry: Market Size & Competitive Landscape
Superconductivity is over 110 years old, yet China's entire HTS tape market sells only a few hundred million yuan a year. Now fusion brings real orders: one compact tokamak consumes some 10,000 km of REBCO tape. This report dissects the business of selling certainty to a dream: one of the world's only two kilometer-scale tape makers in Shanghai, localization of substrates, targets and equipment, the LTS/HTS accounting traps, and a 2026-2030 outlook set by the fusion calendar.