


Aviation Transport and Airport Sector Research: Post-Pandemic Recovery, Competitive Dynamics, and Supply-Chain Opportunities
China's civil aviation sector climbed from near-total pandemic shutdown to a record 700 million passengers in 2024. This report maps the industry structure, the four key players in the chain, demand cycles, competitive landscape, and risks — and points to upstream opportunities in aviation equipment manufacturing.
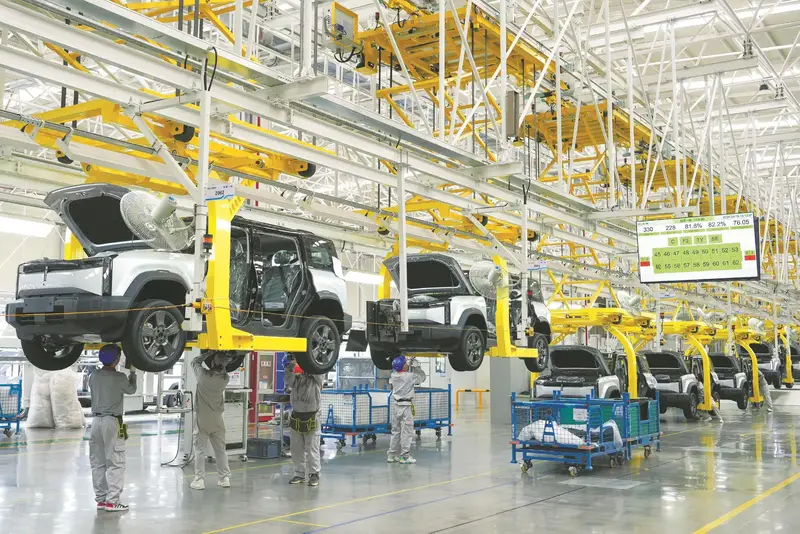
2026 China Automotive OEM Industry: Market Size and Competitive Landscape Deep Research Report
In 2025, China's auto production/sales both exceeded 34 million units. NEV sales hit 16.49 million with ~53-54% retail penetration (Dec. 60%+). Exports of 7.098 million held global No. 1 for a 2nd year. Domestic brands captured ~70% share. Leapmotor achieved first full-year profit; BYD overseas surpassed 1M units. EU 'price undertaking' framework confirmed; US tariffs reached 137.5%. This report presents FY2025 actuals and 2026-2030 projections.
2026 Deep Research Report: China Automotive Parts Market Scale and Competitive Landscape
In 2025, China's automotive parts market reached ~RMB 5 trillion at the crossroads of NEV and intelligent-driving transformation. Five high-growth tracks — thermal management, integrated die-casting, brake-by-wire, air suspension, and robot actuators — grew 30%+ annually. Chinese companies reached 15 seats in the Global Top-100 for the first time; CATL broke into fifth globally. Tuopu, Sanhua, and Yinlun posted combined revenue of nearly CNY 76.3 billion.
China Intelligent Driving (ADAS/AD) Supply Chain: Market Scale and Competitive Landscape 2026 Deep Research Report
China's passenger vehicle intelligent driving penetration exceeded 60% in 2025, with NOA reaching ~22%. First L3 pilots, Tesla FSD entry, and end-to-end large models replacing rule code drove the supply chain into a dual inflection point. This report covers chips (Horizon, Black Sesame, Huawei), domain controllers (Desay SV, JOYSON), algorithms, HD maps, and L4 Robotaxi (Baidu Apollo, Pony.ai, WeRide), forecasting NOA exceeding 50% by 2030.
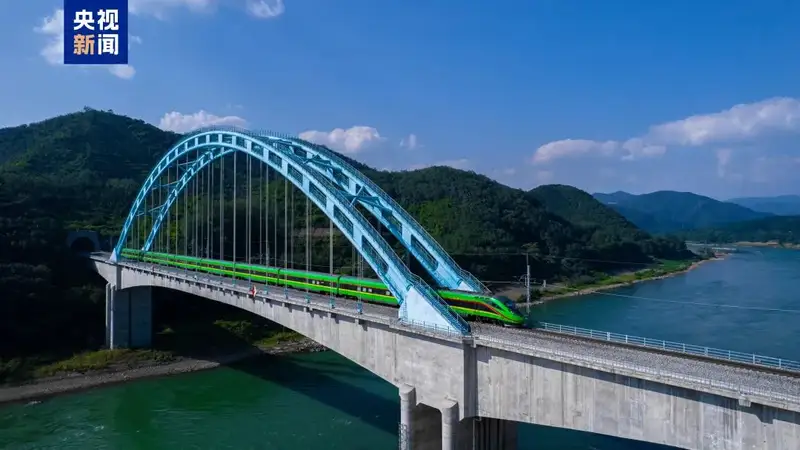
China High-Speed Rail and Rail Transit Equipment: Market Scale and Competitive Landscape 2026
China now operates over 50,000 km of high-speed rail — more than all other countries combined — with 4,500+ EMUs in service and CRRC ranked No. 1 globally in rail transit equipment revenue. This report maps the complete supply chain from rolling stock to traction, signaling, braking and bogies; profiles the major listed companies' FY2025 financials; traces key industrial clusters; and assesses CR450, SiC power devices, and autonomous operation trends through the 2026–2030 forecast horizon.
2026 China Low-Altitude Economy & eVTOL Industry: Market Scale and Competitive Landscape In-Depth Research Report
From China's 2023 'low-altitude economy' policy elevation to EHang's world-first eVTOL four-certificate commercial operations in 2025 — this report reviews market scale (670B yuan in 2024, targeting 3–5T yuan by 2030), the three-track industrial structure (GA/eVTOL/industrial drones), key company profiles, technology evolution, and core risks, with forward projections for the 2026–2030 competitive landscape.
2026 China Aviation Engine & Large Commercial Aircraft Supply Chain: Industry Scale and Competitive Landscape Deep Research Report
Three parallel narratives — C919 mass production, C929 first flight, and CJ-1000A domestic engine breakthrough — simultaneously reached decisive windows in 2026. This report surveys the RMB 800 billion market across 14 chapters.
2026 China Logistics & Express Industry Deep-Dive Report: 175 Billion Parcels, RMB 368 Quadrillion in Total Logistics Value, and Global Expansion
In 2025, China's express delivery reached 175 billion parcels — more than 65% of global volume — with total social logistics value hitting RMB 368 quadrillion. This report examines all five logistics tracks (general logistics, express, cold chain, instant delivery, and cross-border), analyzing SF Express, the Tongda system, J&T, JD Logistics, Cainiao, and the global trio (FedEx/UPS/DHL), projecting the industry's competitive evolution through 2030.
Iron Boxes for the World: A 2026 Deep Report on China's Container Industry — Market Scale and Competitive Landscape
Ninety-six out of every one hundred containers in the world are made in China; CIMC Group alone controls roughly 40% of global production capacity. This is an industry China has won — yet one still being disrupted. The Red Sea crisis pushed prices from $1,800 to $4,500 and back to $2,800; energy storage containers, refrigerated containers, and modular construction are quietly reshaping the competitive map. This report deconstructs every layer of the industry.
2026 China Heavy Truck and Commercial Vehicle Industry: Market Scale and Competitive Landscape — In-Depth Research Report
China's heavy truck sales topped 1 million units in 2025, NEV penetration reached ~23% for the year and 54% in the final month, exports hit a record ~330,000 units. Electrification, overseas expansion, and intelligent driving are reshaping a market long held by SINOTRUK, FAW Jiefang, Shaanxi Auto, Dongfeng, Foton, and Yutong. This report maps the full transformation: market scale, supply chains, enterprise financials, industrial belts, technology, and forecasts to 2030.
2026 China Satellite Internet and Commercial Spaceflight Industry: Market Size and Competitive Landscape In-Depth Research Report
A comprehensive research report mapping the deployment progress of the Qianfan G60 and GW LEO mega-constellations, reusable commercial rocket technology breakthroughs, satellite electronics supply chain ecosystem, and global player dynamics including SpaceX Starlink — covering market size, industry chain, key enterprises, risk matrix, and 2030 development forecasts.
China Port & Shipping 2026: Containers, Dry Bulk, Tankers, LNG, Automated Terminals and BRI Overseas Ports — Deep Research Report
Ningbo-Zhoushan Port logged its 17th straight year as the world's busiest by cargo tonnage; Shanghai led globally in container throughput for the 16th year; COSCO SHIPPING Holdings held the world's 3rd-largest container capacity. This report covers six pillars — container shipping cycles, dry bulk, tankers, LNG, automated terminals, and BRI overseas ports — reviewing FY2025 data and the 2026 outlook.
2026 China Electric Two-Wheeler Industry Market Size and Competitive Landscape Deep Research Report
Focusing on four structural themes — new national standards, lithium electrification, intelligent connectivity, and overseas expansion — this report provides a systematic analysis of China's 55–60 million unit electric two-wheeler market, covering the competitive landscape, supply chain overview, and the 2026–2030 evolution trajectory.
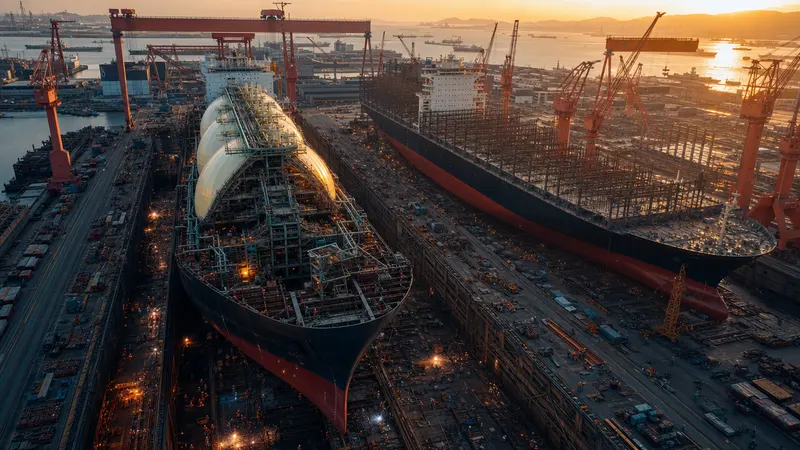
Steel on the Sea: China's Shipbuilding Industry — 2026 Market Scale and Competitive Landscape
In 2025, China completed 53.69 million DWT, received 107.82 million DWT in new orders, and held a record backlog of 274.42 million DWT — world-leading for the sixteenth year. A 55,000-character complete structural analysis across 12 chapters.
China's eVTOL and Low-Altitude Economy Supply Chain (2026): Now That Airframers Have Their Certificates, Which Upstream Factories Are the Orders Flowing To?
The newly revised Civil Aviation Law took effect on July 1, 2026, EHang delivered 221 aircraft in 2025, and AutoFlight won the world's first overseas airworthiness validation for an eVTOL — on the eve of volume production, order opportunities are opening up across four upstream tracks: motors and motor controllers, aerospace-grade carbon fiber, high-rate batteries, and vertiport equipment.
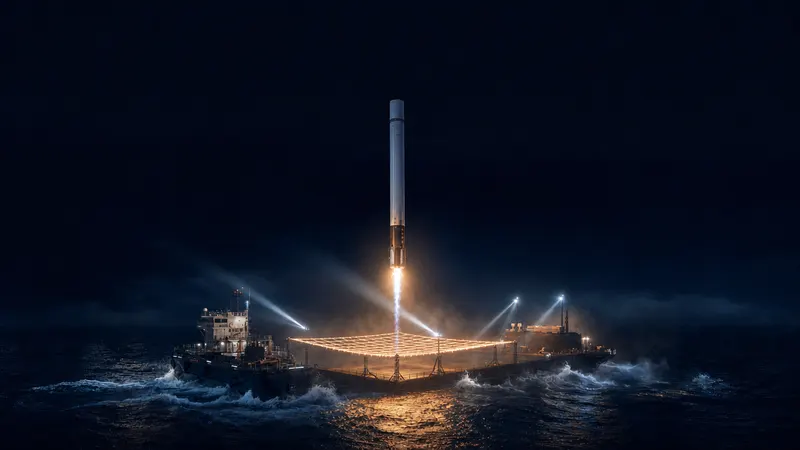
Catching a Rocket: China's Offshore Net-Capture Recovery and the Reusable-Launch Supply Chain
After the world's first offshore net-capture recovery of an orbital booster, this in-depth report dissects the catch mechanics, the global genealogy of recovery routes, the economics of reuse, and the fiber-net-ship supply chain behind Long March 10B - including a sober debunking of a supplier-attribution frenzy - and closes with three testable forecasts.
Catching Itself: Zhuque-3 and the Industrial Chain Behind China's Private Reusable Rockets
In late 2025 Zhuque-3's maiden flight reached orbit but its first-stage recovery failed; the static-fired Y2 now aims for China's first orbital-class first-stage recovery by a private firm. Tracing the rocket from methalox Tianque engines and a stainless-steel airframe to landing control, reuse economics, constellation launch demand, China's two recovery routes and a supply chain opening to Chinese factories, this report argues reusability is at heart a manufacturing question.
China's Tire Industry 2026: Volume Champion, Quality Climb, and a Second Wave of Globalization Under Tariff Siege
China makes roughly half the world's tires yet earns a margin of only about 3%—the starkest picture of being 'big but not strong.' This report dissects how China climbs from volume champion to quality contender: Sailun's Liquid Gold, the NEV OE reversal, Lighthouse factories, near-90% import dependence on natural rubber, and a second wave of globalization from Southeast Asia to Morocco and Egypt.
China's Civilian Drone Industry 2026: Strong Yet Besieged — One Company, One Nation's Sky
In 2026, DJI holds roughly 70% of the global consumer-drone market, China's agricultural drones top 300,000 units and enter the No.1 Central Document, and delivery-drone orders outpace Google's Wing—a technologically dominant, globally leading industry. Yet precisely because it is so strong, DJI faces US category-wide sales bans, customs seizures, and supply-chain warfare. This report dissects the era's defining question of a Chinese industry that is 'strong yet besieged.'
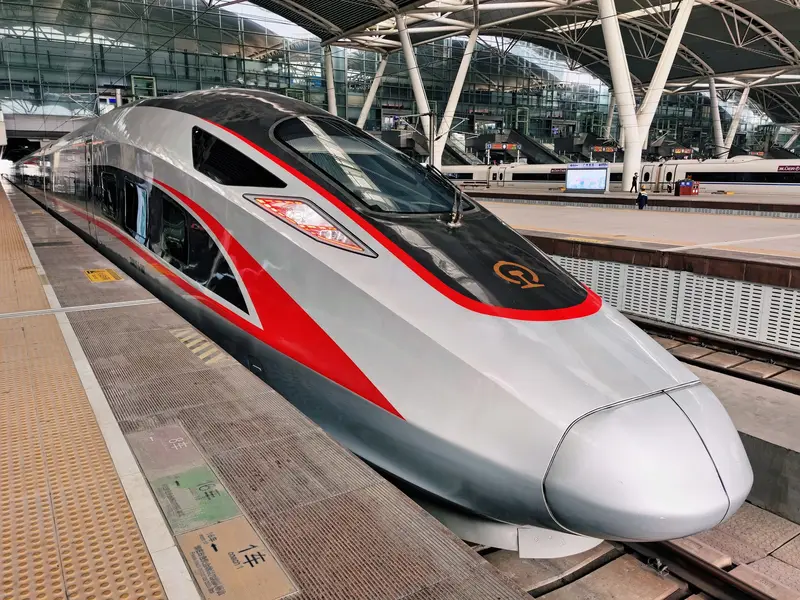
China's High-Speed Rail and Rail Transit Equipment Industry 2026: A National Calling Card's Ascent, and Its 'Smooth South, Blocked North' Overseas Expansion
In 2026, China's high-speed rail in service tops 50,000 km—over 70% of the world's total; CRRC is the world's largest rail-equipment maker at about 53% share; and the CR450 enters uncharted territory at 400 km/h in service. From importing four technology platforms to the fully indigenous Fuxing and leading UIC standards, China completed the full arc of ascent to the summit. Yet this calling card's overseas push is 'smooth in the South, blocked in the North.'