


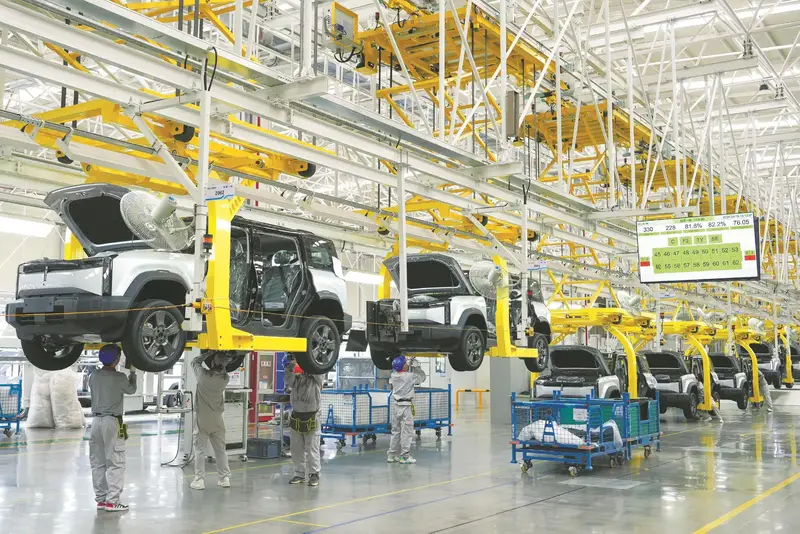
2026 China Automotive OEM Industry: Market Size and Competitive Landscape Deep Research Report
In 2025, China's auto production/sales both exceeded 34 million units. NEV sales hit 16.49 million with ~53-54% retail penetration (Dec. 60%+). Exports of 7.098 million held global No. 1 for a 2nd year. Domestic brands captured ~70% share. Leapmotor achieved first full-year profit; BYD overseas surpassed 1M units. EU 'price undertaking' framework confirmed; US tariffs reached 137.5%. This report presents FY2025 actuals and 2026-2030 projections.
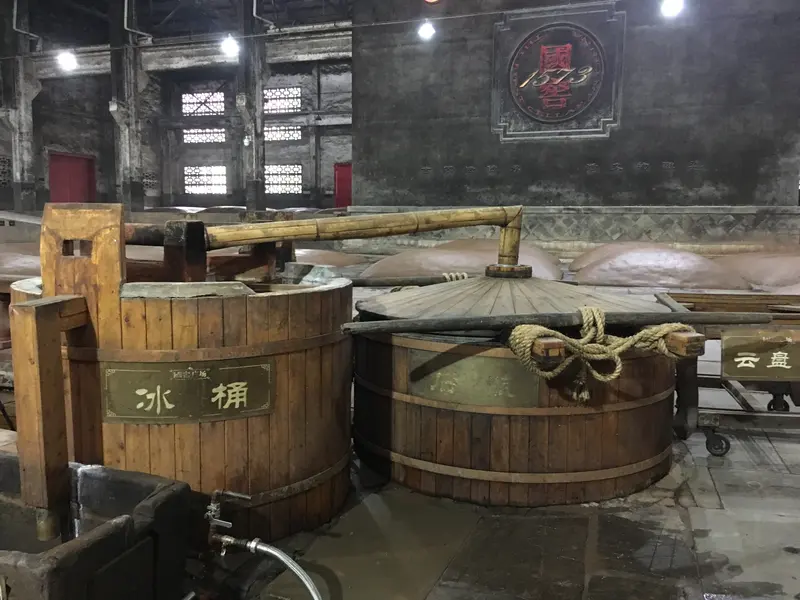
China Baijiu Industry 2026: Market Scale and Competitive Landscape — Deep Research Report
In 2024, China's baijiu sector generated ~RMB 796 billion in output value, with production at 4.145 million kiloliters — seven years of volume decline offset by premiumization. Concentration is extreme: Moutai captures ~40% of industry profits; CR3 at the premium tier exceeds 70%. After the sauce-aroma bubble deflated, the industry faces inventory overhang, Gen Z disengagement, and e-commerce channel disruption. This deep-research report covers 12 aroma types, 19 listed companies' 2024 financ...
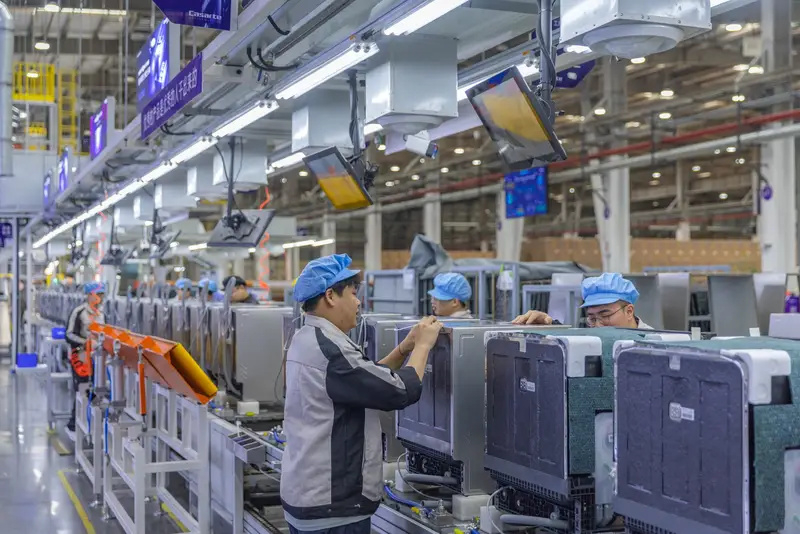
China Home Appliance Industry 2026: Market Scale, Competitive Landscape, and Global Reach
China home appliance sector 2026: domestic retail ~RMB 907bn (+6.4%), exports record USD 112.4bn (+14%). White goods CR3 ~70%+ (Midea+Gree+Haier). Trade-in subsidy stimulated ~RMB 270bn in 2024. Chinese TV brands overtook Samsung+LG globally. Robot vacuums grew 21.9% to ~RMB 21.7bn; Chinese brands dominate all global top-5. BOE+CSOT+HKC hold ~70.6% of global TV LCD panel share. Mini-LED TV: 4.16mn units (+352%). 2030 forecasts: domestic CAGR ~3-5%, export CAGR ~7-10%.
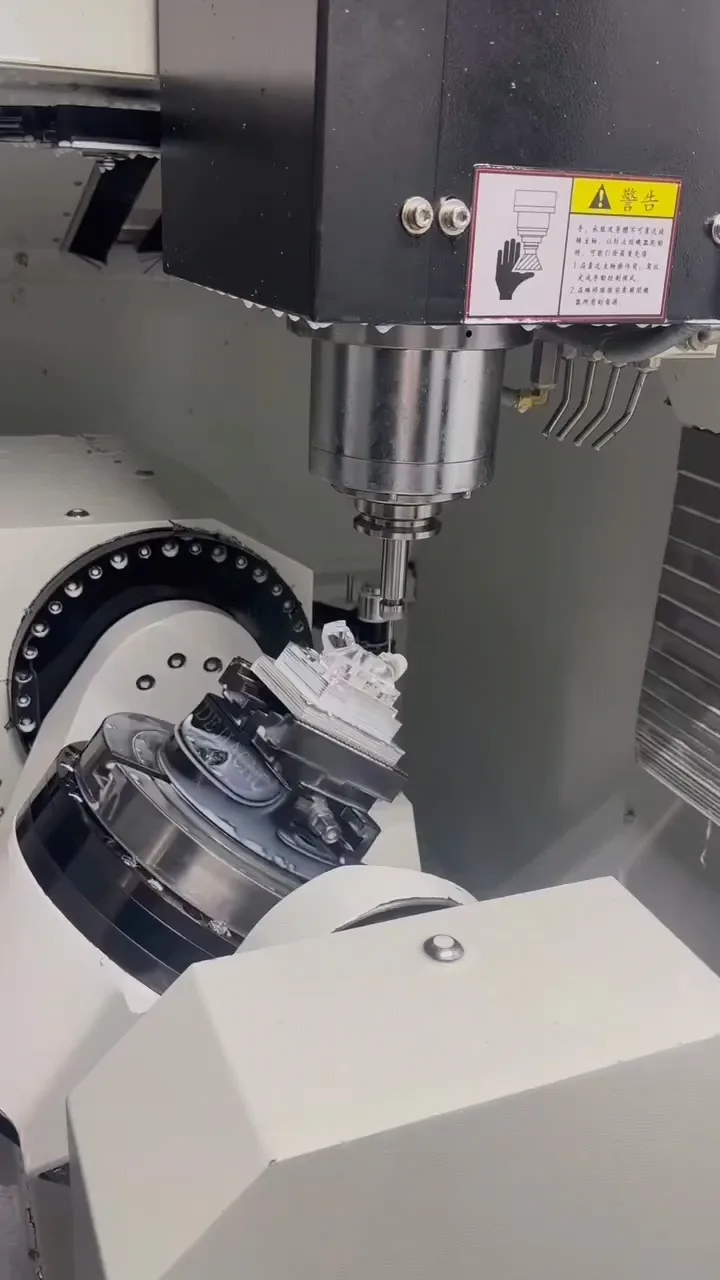
China Machine Tool Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Machine tools are the mother machines of manufacturing — they set the precision ceiling for every factory. This report examines China machine tool industry in 2026: market size, value chain, competition, technology and the 2026-2030 outlook. China leads globally in both output and consumption (about 32% and 33% in 2024), yet localization of high-end five-axis stays around 25% and high-end CNC controllers at just 6%, while Germany and Japan still hold the value peak.
China PCB Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Printed circuit boards are the backbone of electronics. This report examines China PCB industry in 2026 across market size, supply chain, competition, technology and the 2026-2030 outlook. China mainland accounts for about 54% of global PCB output; Zhen Ding Tech leads at around 12% share. Yet IC substrate and Ajinomoto ABF film localization stays at only 4%-10%, dominated by Ibiden, AT&S and Unimicron. AI servers are the biggest 2024 engine, lifting margins at WUS, Victory Giant and Shennan.
China Laser Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Lasers are the optical scissors of industry. This report examines China laser industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. China is the largest laser equipment consumer globally; low-to-mid power fiber laser localization exceeds 99%, with Raycus overtaking IPG at about 27% China share. Yet high-power pump chips, ultrafast lasers and ASML EUV CO2 sources remain held by IPG, TRUMPF and Coherent.
China Reducer Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
The reducer is the joint of manufacturing. This report examines China reducer industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. The industry has two faces: general-purpose reducers are small and scattered with over 90% localization, while precision reducers are the value high ground for domestic substitution. Domestic RV reducers now hold about 60.8% share and harmonic reducers over 80%, yet lifespan and upstream bottlenecks still lag.
China's Modified Plastics Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's modified-plastics industry in 2026. Modified plastics tunes base resins into high-performance materials, where value lies in formulation and additives. China makes about 29.75 million tonnes a year, yet its modification rate is only about 25%, less than half the global level (about 50%) and the core room for growth. The market is highly fragmented: CR3 about 14%, Kingfa only about 7.86%, over 10,000 firms.
China's Beer Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's beer industry in 2026. Output has fallen about 30% from its 2013 peak and the market has entered stock competition, yet revenue and profit keep hitting records as the industry trades volume for value: premiumization is the only growth engine. The sector is unusually concentrated (CR5 about 92%: China Resources, Tsingtao, Budweiser APAC, Yanjing, Chongqing), while craft beer and the upstream supply chain stay highly fragmented.
China's Bearing Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's bearing industry in 2026. Called the joints of industry, bearings see China produce nearly 30 billion units a year (first worldwide for years; 2024 revenue about RMB 231.5 billion), yet it stays a textbook large-industry-of-small-companies: CR10 only about 28%, high-end products just about 5% with roughly 70% import dependence. An import-export unit-price gap of about 74% lays bare the gulf between scale and precision.
China's Coatings Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's coatings industry in 2026: nearly 35 million tonnes produced a year and first worldwide for 15 straight years, yet a textbook large-industry-of-small-companies where the top ten hold only about 21.7% and foreign brands dominate the high end. Raw materials (resins, titanium dioxide) make up 80-90% of cost. Architectural coatings are dragged down by the property downturn and a wave of project bad debt, while industrial coatings have risen to about 66%.
China's Fastener Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's fastener industry in 2026: nearly 10 million tonnes produced a year and first worldwide, yet a fragmented pyramid of low-end overcapacity and high-end imports, where imported high-end fasteners fetch 8-9 times the price of exported standard parts. Demand concentrates in automotive (~58%); wind power, rail, and aerospace are the high-value growth tracks, with aerospace titanium-alloy fasteners the ultimate chokepoint.