China's Fastener Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's fastener industry in 2026: nearly 10 million tonnes produced a year and first worldwide, yet a fragmented pyramid of low-end overcapacity and high-end imports, where imported high-end fasteners fetch 8-9 times the price of exported standard parts. Demand concentrates in automotive (~58%); wind power, rail, and aerospace are the high-value growth tracks, with aerospace titanium-alloy fasteners the ultimate chokepoint.
China's Bearing Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's bearing industry in 2026. Called the joints of industry, bearings see China produce nearly 30 billion units a year (first worldwide for years; 2024 revenue about RMB 231.5 billion), yet it stays a textbook large-industry-of-small-companies: CR10 only about 28%, high-end products just about 5% with roughly 70% import dependence. An import-export unit-price gap of about 74% lays bare the gulf between scale and precision.
China's Injection Molding Industry 2026: Market Size and Competitive Landscape
A systematic analysis of the market size, value chain, and competitive landscape of China's injection molding industry in 2026: a highly concentrated machine segment (Haitian leads at home with 30%+ share, first worldwide) versus an extremely fragmented midstream of roughly 5 million molders. Chinese machines have moved from import substitution to export leadership, yet all-electric, precision, and large-tonnage high-end still belong to Japan and Germany.
China's Coatings Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's coatings industry in 2026: nearly 35 million tonnes produced a year and first worldwide for 15 straight years, yet a textbook large-industry-of-small-companies where the top ten hold only about 21.7% and foreign brands dominate the high end. Raw materials (resins, titanium dioxide) make up 80-90% of cost. Architectural coatings are dragged down by the property downturn and a wave of project bad debt, while industrial coatings have risen to about 66%.
China's Modified Plastics Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's modified-plastics industry in 2026. Modified plastics tunes base resins into high-performance materials, where value lies in formulation and additives. China makes about 29.75 million tonnes a year, yet its modification rate is only about 25%, less than half the global level (about 50%) and the core room for growth. The market is highly fragmented: CR3 about 14%, Kingfa only about 7.86%, over 10,000 firms.
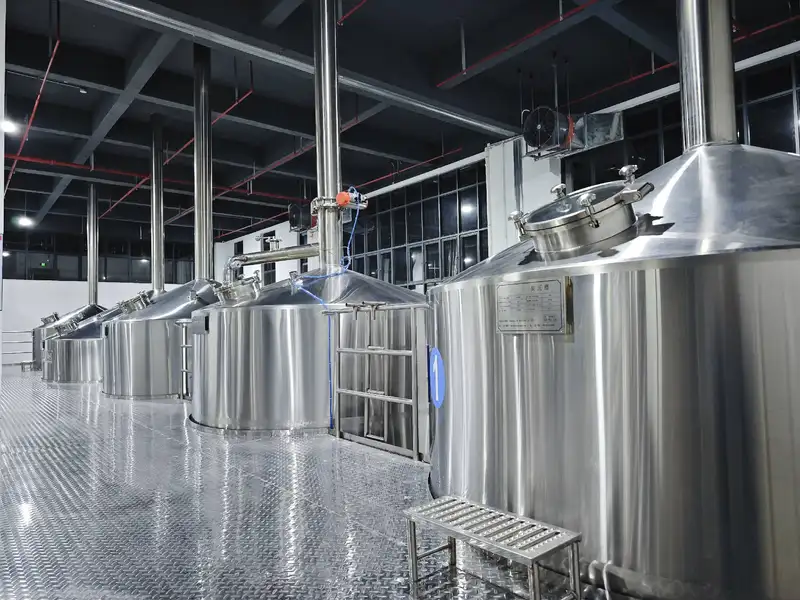
China's Beer Industry 2026: Market Size and Competitive Landscape
A systematic analysis of China's beer industry in 2026. Output has fallen about 30% from its 2013 peak and the market has entered stock competition, yet revenue and profit keep hitting records as the industry trades volume for value: premiumization is the only growth engine. The sector is unusually concentrated (CR5 about 92%: China Resources, Tsingtao, Budweiser APAC, Yanjing, Chongqing), while craft beer and the upstream supply chain stay highly fragmented.
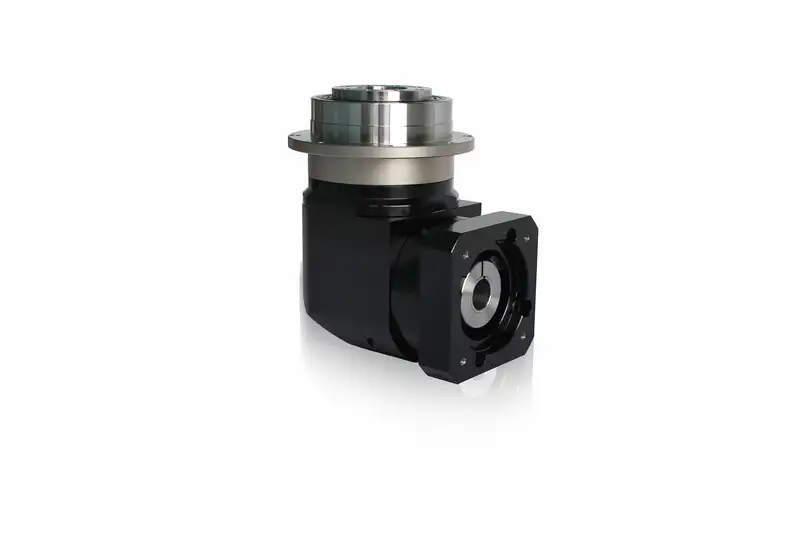
China Reducer Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
The reducer is the joint of manufacturing. This report examines China reducer industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. The industry has two faces: general-purpose reducers are small and scattered with over 90% localization, while precision reducers are the value high ground for domestic substitution. Domestic RV reducers now hold about 60.8% share and harmonic reducers over 80%, yet lifespan and upstream bottlenecks still lag.
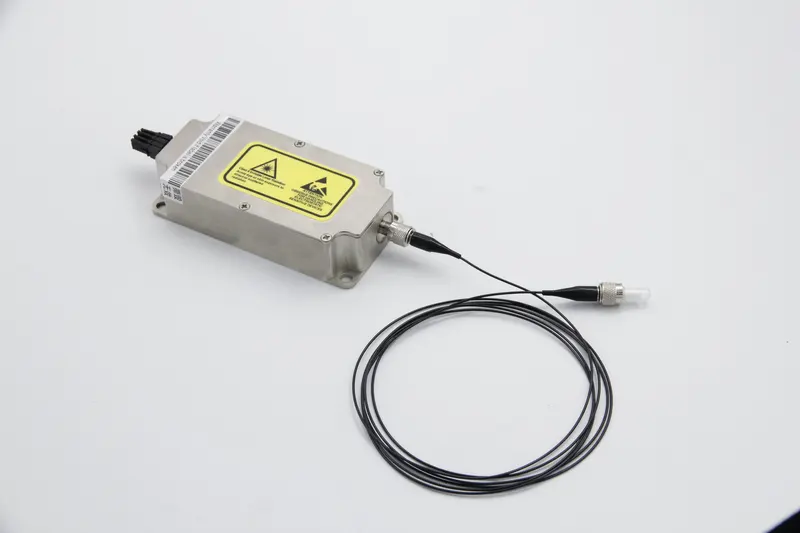
China Laser Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Lasers are the optical scissors of industry. This report examines China laser industry in 2026: market size, value chain, competition, technology, risks and the 2026-2030 outlook. China is the largest laser equipment consumer globally; low-to-mid power fiber laser localization exceeds 99%, with Raycus overtaking IPG at about 27% China share. Yet high-power pump chips, ultrafast lasers and ASML EUV CO2 sources remain held by IPG, TRUMPF and Coherent.
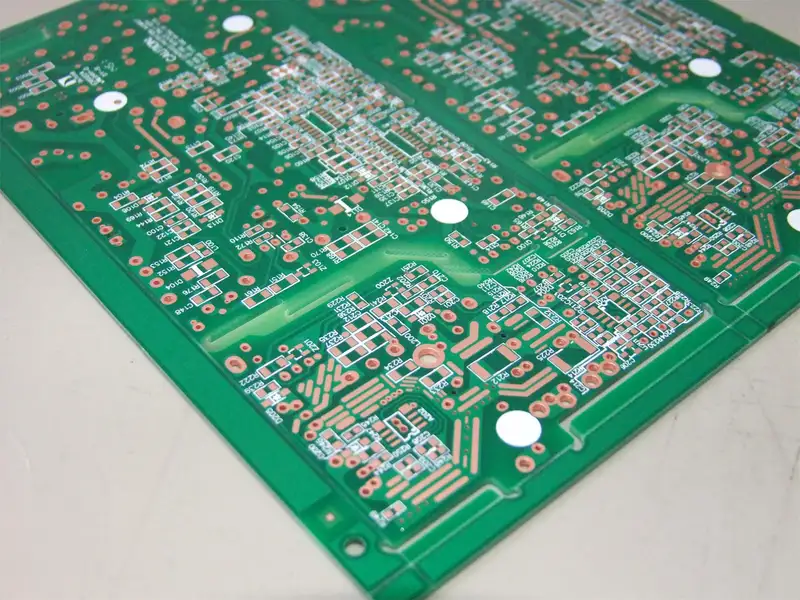
China PCB Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Printed circuit boards are the backbone of electronics. This report examines China PCB industry in 2026 across market size, supply chain, competition, technology and the 2026-2030 outlook. China mainland accounts for about 54% of global PCB output; Zhen Ding Tech leads at around 12% share. Yet IC substrate and Ajinomoto ABF film localization stays at only 4%-10%, dominated by Ibiden, AT&S and Unimicron. AI servers are the biggest 2024 engine, lifting margins at WUS, Victory Giant and Shennan.
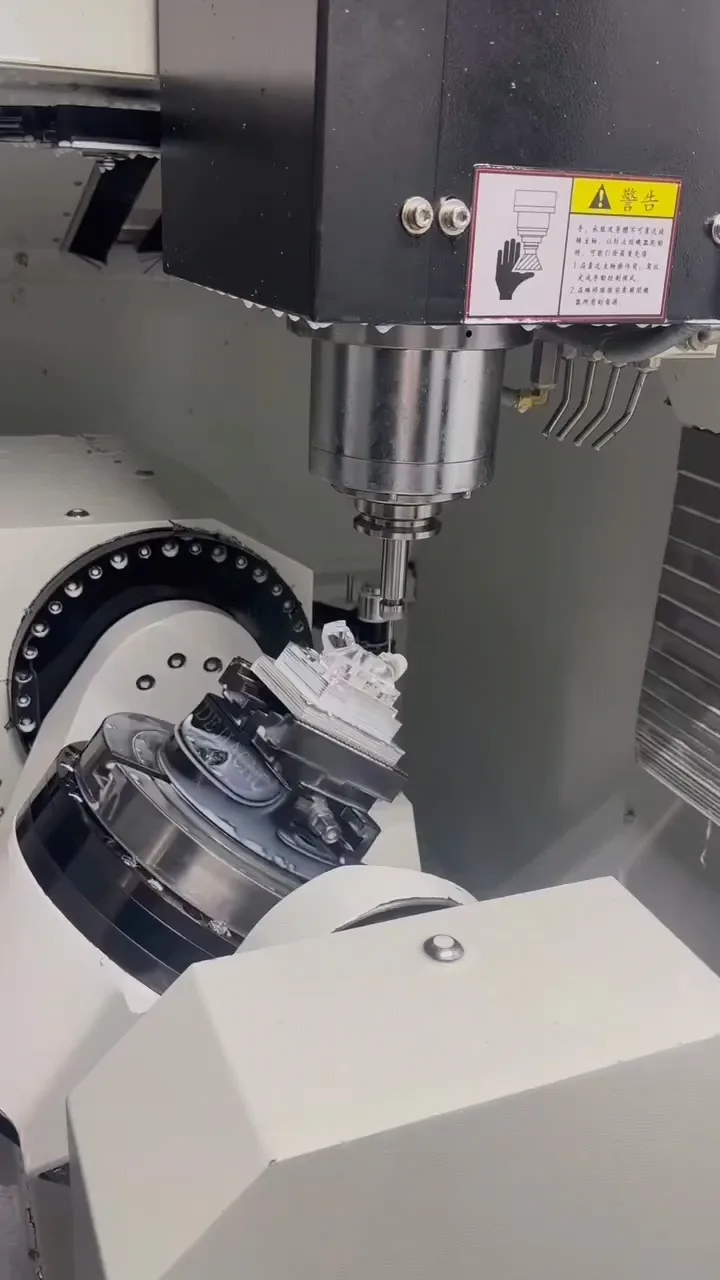
China Machine Tool Industry 2026: Market Size and Competitive Landscape — In-Depth Research Report
Machine tools are the mother machines of manufacturing — they set the precision ceiling for every factory. This report examines China machine tool industry in 2026: market size, value chain, competition, technology and the 2026-2030 outlook. China leads globally in both output and consumption (about 32% and 33% in 2024), yet localization of high-end five-axis stays around 25% and high-end CNC controllers at just 6%, while Germany and Japan still hold the value peak.
China Semiconductor Equipment Market 2026: Scale, Competition, and Localization Roadmap
China is the world's largest semiconductor equipment market (~$40B in 2024, 37% of global demand), yet domestic equipment covers only ~10-12% of total demand. Localization rates span enormously from stripping (65%) to lithography (<5%). This report analyzes ASML, AMAT, Lam, TEL, KLA, thirteen Chinese listed equipment makers, upstream chokepoints, six regional clusters, and forecasts category-level domestic penetration rates through 2030.
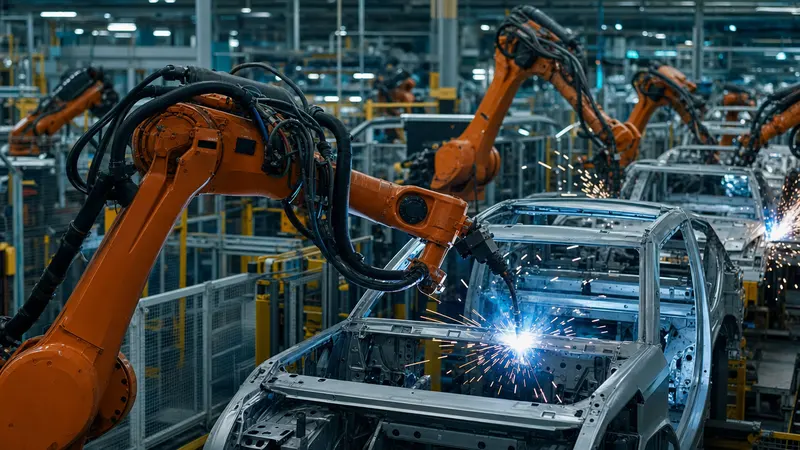
China Industrial Robot Sector: 2026 Market Scale and Competitive Landscape Research Report
In 2024, China added 295,000 newly installed industrial robots (54% of global total), with domestic brands capturing 57% domestic share for the first time—a historic inflection. The Big Four (Fanuc, ABB, KUKA, Yaskawa) still hold the high-end segment with precision-reducer and controller moats, while Estun and Inovance drive domestic breakthroughs. Humanoid robots are the largest upside scenario and the greatest uncertainty through 2030.
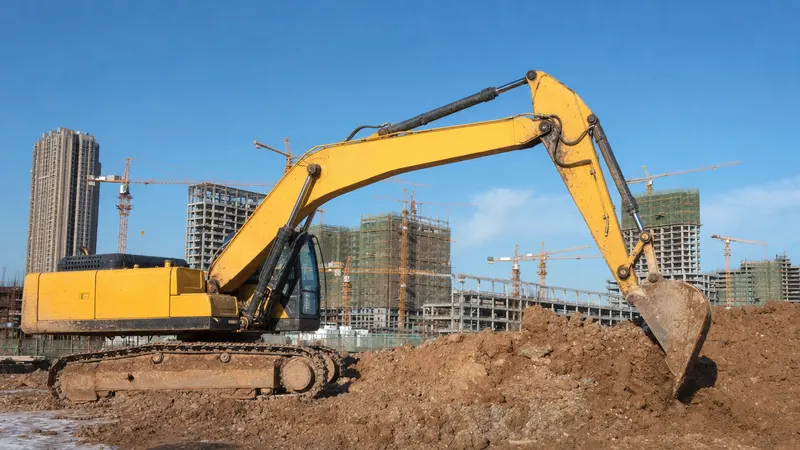
2026 China Construction Machinery Industry: Market Size and Competitive Landscape Deep Research Report
Overseas expansion and electrification define China's construction machinery industry in 2026: domestic real estate contraction drove the four majors toward global markets; excavator domestic/export parity marks a structural shift; electric excavators totaled 86 units in 2024 but loaders crossed 10% penetration. Hengli Hydraulic leads hydraulic localization; SANY, XCMG, Zoomlion, and LiuGong target 58-62% overseas revenue by 2030.
China MLCC and Passive Components: Market Scale and Competitive Landscape Research Report 2026
China consumes 40% of global MLCC output yet mainland producers held only 10% revenue share in 2024. Global MLCC market: USD 140-180B, dominated by Murata (~40%), SEMCO (~24%), Taiyo Yuden, TDK, Yageo (CR5 ~75%). BEVs use 10,000+ MLCCs vs 3,000 in ICE vehicles; automotive localization rate <5%. An Nvidia GB200 rack needs 440,000 MLCCs -- 30x a smartphone. Three-Ring Group leads domestic automotive-grade MLCC. 2030 forecast: USD 230-280B.
2026 China Solar Module Industry: Market Scale and Competitive Landscape Deep Research Report
In 2024, China produced ~600 GW of solar modules — over 80% of global output — while the six major module giants combined for losses exceeding 140 billion RMB. Under the triple pressure of overcapacity, price floors (0.65 RMB/W), and overseas anti-dumping duties, the industry faces a war of attrition. This report analyzes technology route competition (TOPCon vs BC vs HJT), the integration vs. specialization debate, and the 2026-2030 outlook.
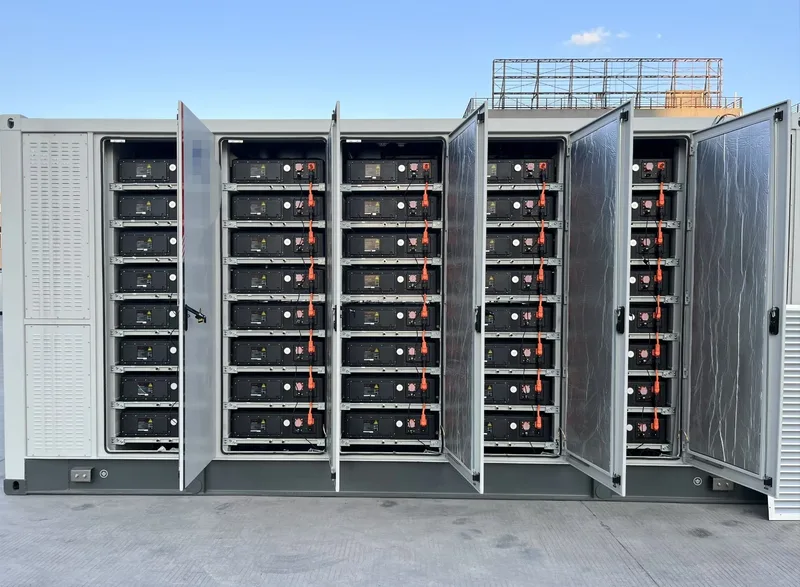
2026 China Energy Storage Industry: Market Size and Competitive Landscape Deep Research Report
China added over 80 GWh of new electrochemical storage in 2024, the most in the world; system prices fell from 1.3 yuan/Wh to 0.6 yuan/Wh; CATL and BYD lead cells while Sungrow and Huawei dominate PCS; standalone storage exceeded co-located for the first time. This report covers China's storage supply chain, competitive landscape, sub-segments, technology trends, and 2026–2030 outlook.
China Lithium Battery Four Key Materials 2026: Market Scale and Competitive Landscape Deep Research Report
Deep-dive on China's four key lithium battery materials, updated through FY2025 annual reports. 2025 cathode ~5.03 million tonnes (+50%), output value ~RMB 274bn (+31%). Yuneng net profit +115%, Tianci net profit +181%, SEMCORP returned to profit. Lithium carbonate ~RMB 170,000/tonne by May 2026. Covers LMFP ramp, sodium-ion, semi-solid milestones, EU battery rules, and 2026-2030 forecasts.
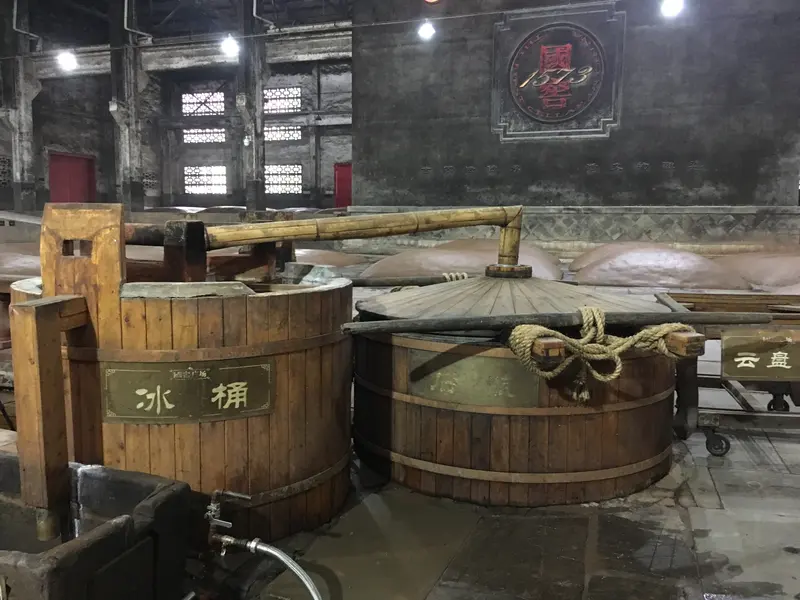
China Baijiu Industry 2026: Market Scale and Competitive Landscape — Deep Research Report
In 2024, China's baijiu sector generated ~RMB 796 billion in output value, with production at 4.145 million kiloliters — seven years of volume decline offset by premiumization. Concentration is extreme: Moutai captures ~40% of industry profits; CR3 at the premium tier exceeds 70%. After the sauce-aroma bubble deflated, the industry faces inventory overhang, Gen Z disengagement, and e-commerce channel disruption. This deep-research report covers 12 aroma types, 19 listed companies' 2024 financ...
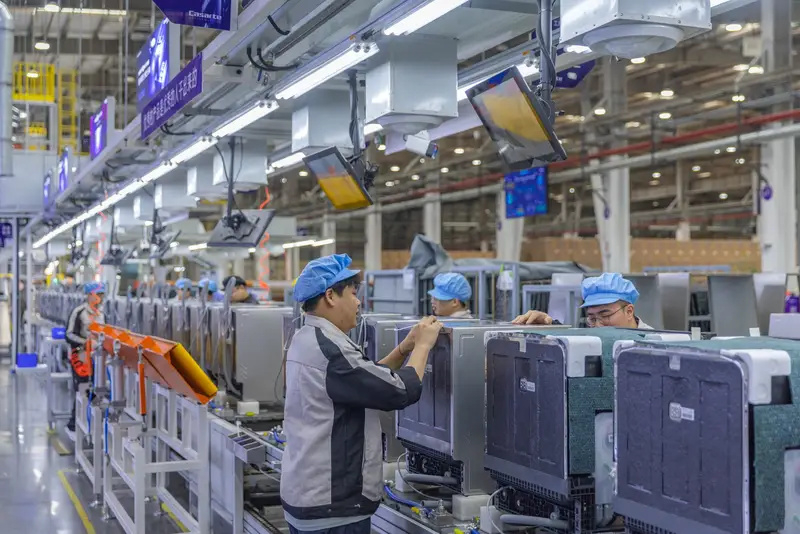
China Home Appliance Industry 2026: Market Scale, Competitive Landscape, and Global Reach
China home appliance sector 2026: domestic retail ~RMB 907bn (+6.4%), exports record USD 112.4bn (+14%). White goods CR3 ~70%+ (Midea+Gree+Haier). Trade-in subsidy stimulated ~RMB 270bn in 2024. Chinese TV brands overtook Samsung+LG globally. Robot vacuums grew 21.9% to ~RMB 21.7bn; Chinese brands dominate all global top-5. BOE+CSOT+HKC hold ~70.6% of global TV LCD panel share. Mini-LED TV: 4.16mn units (+352%). 2030 forecasts: domestic CAGR ~3-5%, export CAGR ~7-10%.
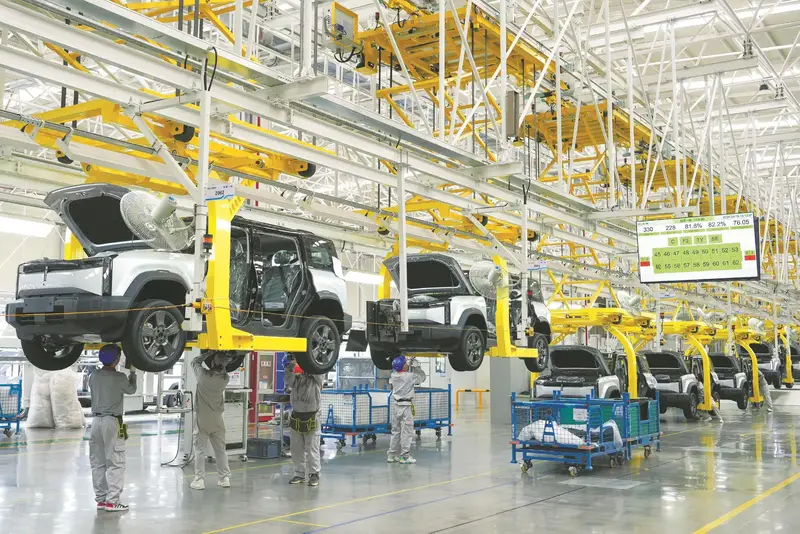
2026 China Automotive OEM Industry: Market Size and Competitive Landscape Deep Research Report
In 2025, China's auto production/sales both exceeded 34 million units. NEV sales hit 16.49 million with ~53-54% retail penetration (Dec. 60%+). Exports of 7.098 million held global No. 1 for a 2nd year. Domestic brands captured ~70% share. Leapmotor achieved first full-year profit; BYD overseas surpassed 1M units. EU 'price undertaking' framework confirmed; US tariffs reached 137.5%. This report presents FY2025 actuals and 2026-2030 projections.

2026 China Innovative Drug Industry: Market Scale, Competitive Structure, and Deep Research Report
2025 China innovative drug License-out totaled ~$135.6B (157 deals, +2.5x YoY), first time surpassing the US at ~49% global share. Hengrui FY2025 revenue RMB 31.6B, net profit RMB 7.7B (records); BeiGene first GAAP annual profit, zanubrutinib global #1 BTK inhibitor; Innovent first GAAP annual profit, mazdutide dual-indication approved; NMPA 2025 record 120 approvals with domestic products >50%. ADC/GLP-1/bispecific/CAR-T all advancing on multiple global Phase 3 fronts.
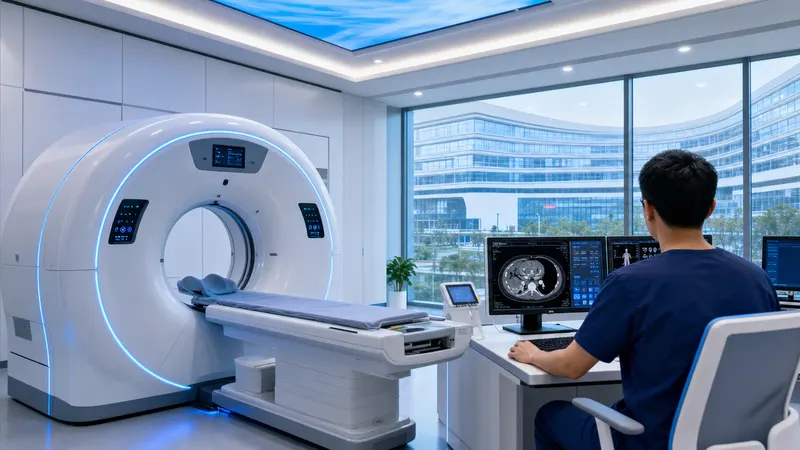
2026 China Medical Device Industry: Market Size and Competitive Landscape Deep Research Report
China's medical device market hit ~RMB 1.3 trillion in 2024 (global #2). UIH broke the GPS imaging monopoly; Mindray leads globally in patient monitor shipments; procurement pressure drives domestic expansion overseas. This 14-chapter report covers global landscape, supply chain, key companies (Mindray/UIH/MicroPort/Weigao/AnTu), segment deep-dives (imaging/IVD/orthopedics/cardiovascular/ophthalmology), technology evolution, and 2026–2030 forecasts.
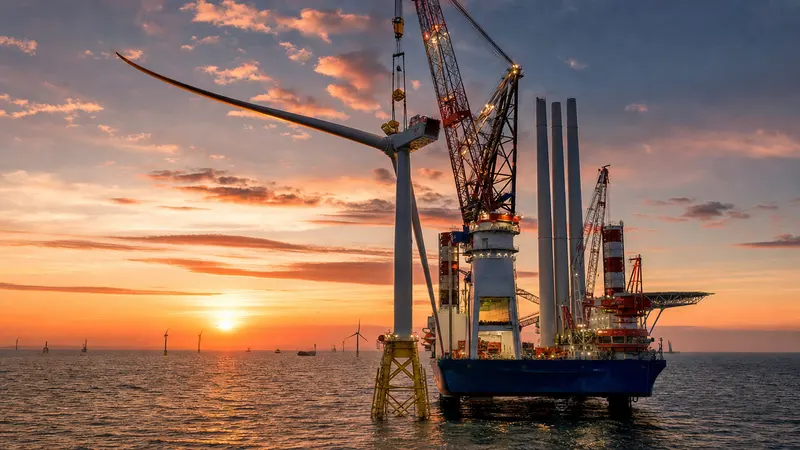
2026 China Wind Turbine Industry Market Scale and Competitive Landscape: An In-Depth Research Report
In 2024, China's newly installed wind power capacity reached approximately 87 GW, with cumulative installations of 520 GW accounting for half the global total. Chinese turbine makers claimed the top four global positions for the first time. Yet average turbine prices fell to a historic low of 1,381 yuan/kW, with turbine gross margins compressed to just 3–8%. This report examines three key variables—the onshore price war, offshore scale-up to 18MW→26MW, and accelerating exports—and maps the in...
2026 China Optical Transceiver Industry: Market Size and Competitive Landscape Research Report
The global optical transceiver market reached approximately USD 17–18 billion in 2024 (+52% YoY), with Chinese vendors holding 7 of the global top 10 positions and CR3 combined share exceeding 50%. This report systematically reviews the optical transceiver supply chain, 800G/1.6T technology roadmaps, key company financials, and a five-year market forecast. Core conclusion: the most certain Chinese advantage segment in the AI compute downstream chain; upstream optical chips are the next domest...
2026 China Display Panel Industry: Market Scale and Competitive Landscape Deep Research Report
Mainland China controls 70%+ of global LCD panel capacity, led by BOE, TCL CSOT, and HKC. Chinese OLED smartphone share surpassed Korea for the first time (50.7%, H1 2024). Gen 8.6 OLED lines — BOE B12 (evaporation) and CSOT t8 (inkjet-printed) — are the biggest technology variable of 2024-2026. This report covers technology taxonomy, global landscape, supply chain, key companies, cluster geography, six application markets, technology roadmap, and 2030 forecasts.
2026 China CMOS Image Sensor (CIS) Industry Market Scale and Competitive Landscape Deep Research Report
CMOS Image Sensors (CIS) are among the most widely deployed visual perception chips today, with a global market of approximately USD 23.7 billion in 2024. Sony leads with ~52% market share. China's domestic localization rate stands at ~30%, with the Big Three (Will/OmniVision, Galaxycore, SmartSens) holding ~23% combined global share and accelerating through automotive ADAS and security tracks. Projected composite localization rate: 45–50% by 2030.
China Steel Industry 2026: Market Scale, Competitive Landscape & Deep Research Report
China produced 1.005 billion tonnes of crude steel in 2024 (53%+ of global output), with steel exports at 110.7 Mt — near-record. Industry profits fell 90%+ from 2021 peak as real estate contraction, overcapacity, and anti-dumping waves collided. Covers Baowu/ArcelorMittal/Nippon Steel competition, supply-demand balance, supply chain, eight companies 2024 financials, rebar/auto-sheet/special-steel segments, EAF and hydrogen decarbonization roadmap, 2026-2030 output and carbon forecasts.
2026 China Chemical New Materials Industry: Market Scale and Competitive Landscape Deep Research Report
China's chemical new materials market is approximately RMB 1 trillion; overall domestic substitution rate is ~70%. Advanced photoresist remains below 5% localised. Wanhua MDI anchors the base while Yake and TongCheng crack open ArF photoresist. Strategic bottleneck materials localisation is entering a new phase.
2026 China Condiment Industry Market Scale and Competitive Landscape — Deep Research Report
China's condiment market approached 600 billion yuan in 2024. The soy sauce duopoly (Haitian 26.9 bn yuan revenue vs. Qianhe's first-ever revenue decline) widened sharply; Hengshun Vinegar net profit surged 46.5%; compound condiment leaders Tianwei, Yihai, and Baoli sustained high growth. This report covers the full supply chain, twelve listed company financials, national industrial cluster geography, and 2030 projections.
2026 China Dairy Industry Market Size and Competitive Landscape: Deep Research Report
Yili and Mengniu hold firm as a duopoly; Feihe and Danone diverge in infant formula; liquid milk suffers volume-price compression in a zero-sum fight for share, while low-temperature pasteurized milk, cheese, and adult nutrition are structural growth channels. Comprehensive deep analysis of China's RMB 520 billion dairy market.
China Auto Industry Watch January-April 2026: The Hot Exports / Cold Domestic Sales Scissors Gap
January-April 2026: China vehicle exports hit 3.12 million units (+61.5% YoY), April alone reaching 901,000 -- a historic record; NEV exports topped 50% for the first time. Meanwhile domestic Q1 sales fell ~6%, dealer inventory climbed to 1.89 months, and OEM net margins hit a near-record low of 3.2%. This report dissects the structural causes of the divergence, five regional export dynamics, four tariff shocks, Q1 earnings from major OEMs, and the outlook through 2027.
Apple Chain Reshaping and the AI Hardware Boom: China Consumer Electronics Foundry Deep Research Report 2026
In 2025, Luxshare surpassed Foxconn in iPhone assembly share; India production reached 25% of global iPhone output, while China's Apple chain share declined to 65–70%. AI servers, AI glasses, and foldables are opening a RMB 1–2 trillion new growth window. This report covers FY2025 data for ten leading companies and forecasts the 2026–2030 landscape.
China IC Design Industry: Market Size, Competitive Landscape, and In-Depth Research Report 2026
In 2025, China's IC design sector posted annual sales of RMB 835.73 billion (~USD 118B), crossing the hundred-billion-dollar threshold for the first time; 3,901 IC design firms — most globally. Domestic AI chip share rose from ~5% (2022) to 42% (2025); automotive analog IC substitution is accelerating; Montage Technology co-leads DDR5 RCD globally with Rambus. Full 12-chapter report covering FY2025 financials of 20+ companies.
2026 Deep Research Report: China Automotive Parts Market Scale and Competitive Landscape
In 2025, China's automotive parts market reached ~RMB 5 trillion at the crossroads of NEV and intelligent-driving transformation. Five high-growth tracks — thermal management, integrated die-casting, brake-by-wire, air suspension, and robot actuators — grew 30%+ annually. Chinese companies reached 15 seats in the Global Top-100 for the first time; CATL broke into fifth globally. Tuopu, Sanhua, and Yinlun posted combined revenue of nearly CNY 76.3 billion.
China Intelligent Driving (ADAS/AD) Supply Chain: Market Scale and Competitive Landscape 2026 Deep Research Report
China's passenger vehicle intelligent driving penetration exceeded 60% in 2025, with NOA reaching ~22%. First L3 pilots, Tesla FSD entry, and end-to-end large models replacing rule code drove the supply chain into a dual inflection point. This report covers chips (Horizon, Black Sesame, Huawei), domain controllers (Desay SV, JOYSON), algorithms, HD maps, and L4 Robotaxi (Baidu Apollo, Pony.ai, WeRide), forecasting NOA exceeding 50% by 2030.
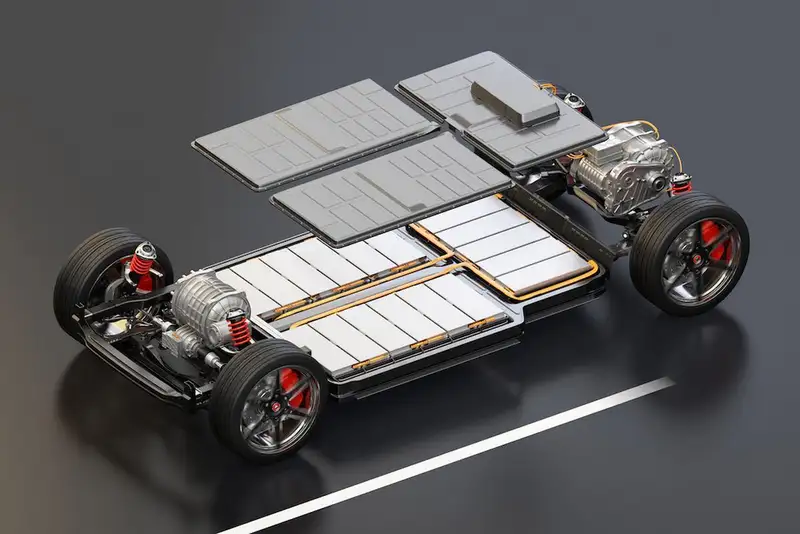
2026 China Power Battery Industry: Market Scale and Competitive Landscape Deep Research Report
In 2025, China EV power battery installation reached 769.7 GWh (world #1), LFP share 81.2%; CATL + BYD hold ~65% domestic share; Chinese firms surpassed 70% global share for the first time. This report covers the cell/module/Pack value chain, key company financials and technology, six major industrial clusters, semi-solid/sodium-ion/large-format cylindrical/CTC frontier topics, and a 2026-2030 five-year forecast.
2026 China Athletic Footwear & Apparel Industry: Market Size and Competitive Landscape Deep Research Report
China's athletic footwear and apparel market reached approximately RMB 598.9 billion in 2025. Anta crossed RMB 80 billion, domestic brands surpassed 50% market share, and Arc'teryx Greater China grew nearly 50%. This is a historic migration from manufacturing exporter to brand exporter. This report analyzes domestic brand ascendance, Nike Greater China's decline, sub-category explosions, and supply chain realignment.
The Sub-RMB-1500 Inflection: 2026 Deep Research Report on China LiDAR Industry Market Size and Competitive Landscape
In 2025, global automotive LiDAR shipments surpassed 2.5 million units with Chinese vendors capturing 80%+; RoboSense MX achieved the historic sub-RMB 1,500 mass-production price point; Luminar filed for bankruptcy; and robot LiDAR materialized as current-quarter revenue. This report uses 2026 as its observation point to systematically review China LiDAR technology routes, supply chain, market size, key companies, and 2026-2030 forecasts.
Smartphones: China's Global Contest for the Palm of Your Hand (2026 Deep Research Report)
In 2025, more than one in every two smartphones sold globally came from a Chinese brand. Huawei reclaimed China's top shipment position for the first time in five years; Apple set an all-time iPhone shipment record; foldable screen penetration surpassed 3%; and on-device AI large language models became the new standard on flagship handsets. This is a systematic study of the structure, technology, and future trajectory of China's smartphone industry.
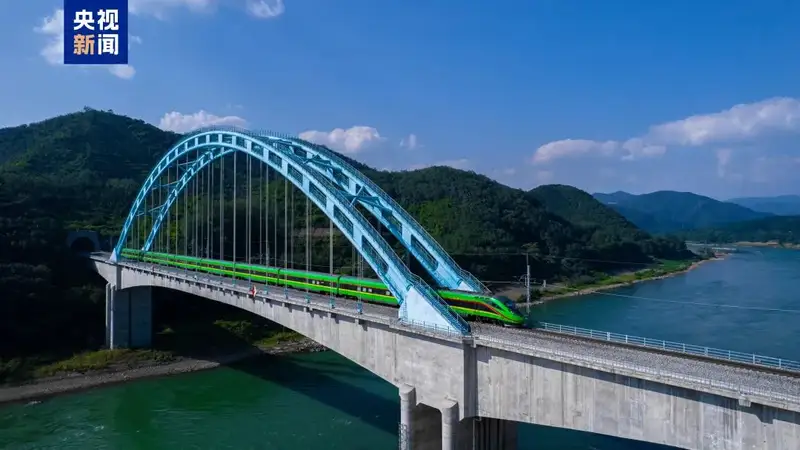
China High-Speed Rail and Rail Transit Equipment: Market Scale and Competitive Landscape 2026
China now operates over 50,000 km of high-speed rail — more than all other countries combined — with 4,500+ EMUs in service and CRRC ranked No. 1 globally in rail transit equipment revenue. This report maps the complete supply chain from rolling stock to traction, signaling, braking and bogies; profiles the major listed companies' FY2025 financials; traces key industrial clusters; and assesses CR450, SiC power devices, and autonomous operation trends through the 2026–2030 forecast horizon.
2026 China Third-Generation Semiconductor (SiC/GaN) Substrate and Device Industry: Market Size and Competitive Landscape Deep Research Report
In 2025, China's SiC substrate capacity ranks No.1 globally; Tianyue Advanced leads conductive SiC substrates with 27.6% global share and 51.3% of 8-inch SiC; Innoscience's GaN power devices turn gross-margin positive for the first time; and Wolfspeed's bankruptcy restructuring reshapes global supply. This deep-dive covers China's complete third-generation semiconductor supply chain, FY2025 enterprise data, the 8-inch SiC technology roadmap, and 2026-2030 market forecasts.
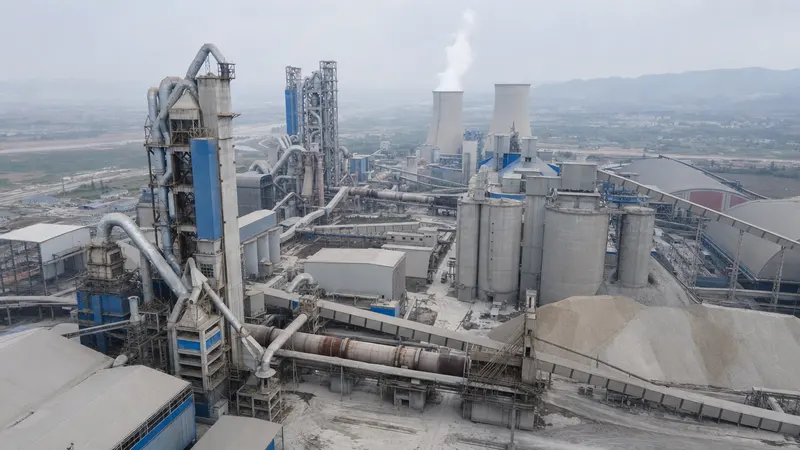
China Cement Industry 2026: Market Size and Competitive Landscape Deep Research Report
China's cement output reached approximately 1.69 billion tonnes in 2025, down over 30% from the 2014 peak of 2.495 billion tonnes. This report systematically covers the global landscape, China market scale, full value chain, and key companies (Conch Cement, Huaxin Cement, Tianshan Shares, China Resources Building Materials, Jinyun Jidong), with analysis of the 2026–2030 consolidation, overseas expansion, and carbon neutrality themes.
2026 China Semiconductor Packaging and Test (OSAT) Industry: Market Size and Competitive Landscape Deep Research Report
The global OSAT market reached ~USD 48B in 2025. Mainland China holds ~30% of global capacity, forming the "Second Pole" alongside Taiwan. JCET ranks global 3rd, Tongfu 4th, Huatian 6th — together ~22-24% of global OSAT. Yet in CoWoS/HBM advanced packaging, mainland localization is under 5%. This report maps the global OSAT landscape, sub-segment localization rates, advanced packaging gaps, and equipment controls, with a 2026-2030 forecast.
Copper vs. Aluminium: 2026 Deep-Dive Research Report on China's Non-Ferrous Metals Industry
In 2025, LME copper peaked above USD 12,000/tonne — best year since 2009 — while China's refined copper broke 14 million tonnes and electrolytic aluminium held near the 45-million-tonne policy ceiling. Against the triple overlay of AI infrastructure, grid upgrades, and EV acceleration, non-ferrous metals face structural demand revolution. This report covers copper, aluminium, lead-zinc, nickel, tungsten, molybdenum, and rare earths through a 2026–2030 outlook.
Supercharging Arms Race: 2026 China EV Charging Infrastructure Market Size and Competitive Landscape Deep Research Report
By end-2025, China's EV charging infrastructure installed base surpassed 20.09 million units — the world's largest. The supercharging arms race has restructured the value chain: Huawei launched a 1,440kW megawatt supercharger, and liquid-cooled modules have become the gating component for supercharger deployment. This report systematically covers the 2025–2026 China EV charging market: size, competitive landscape, industrial clusters, and 2030 outlook.
Battery Equipment: The Hidden Backbone of Chinese Manufacturing (2026 Deep Research Report)
China's lithium battery equipment market reached approximately RMB 800–900 billion in 2025. After the 2024–2025 trough, recovery is now underway in 2026. Pioneer Intelligent leads globally; Hymson Laser holds the high ground in laser welding; Hangke Technology anchors the back-end formation and grading segment. Solid-state battery pilot lines and overseas factory orders are reshaping this sector's competitive landscape.
2026 China MCU Microcontroller Industry: Market Size and Competitive Landscape Deep Research Report
Global MCU market in 2025 approximately US8 billion; ST/NXP/Microchip/Renesas/Infineon/TI six giants hold 80% globally. China MCU market approximately RMB 35 billion, 32-bit exceeding 70% share, domestic localization rate approximately 20%, automotive-grade under 5%. GigaDevice GD32 cumulative shipments exceed 2 billion units, Espressif ESP32 global Wi-Fi MCU share over 30%; automotive-grade localization is the deepest moat, RISC-V + AI MCU is the next battle.
Four Faces of Glass: Solar Overcapacity, Float Bottoming, Fuyao's Monopoly, and Electronic Breakthrough (2026 Deep Report)
China produces enough glass each year to cover the entire island of Hainan. But behind the word 'glass' lie four completely different stories: solar glass trapped in the most brutal price war in its history; float glass bottoming out alongside real estate; a Fujian company quietly capturing one-third of the global automotive glass market; and electronic glass substitution, inch by inch prying open an iron curtain long held by Corning and AGC.
The Power of the Contract: A 2026 Deep-Dive Research Report on China's CXO (CRO + CDMO) Pharmaceutical Outsourcing Industry
The global CXO market has surpassed USD 150 billion, with China accounting for 25–30%. The BIOSECURE Act became law in December 2025; GLP-1 peptides and ADC drugs are driving order recovery; AI is reshaping the model. This report tracks China CXO's structural shift from low-cost labor to technology-barrier differentiation.
2026 China Power Semiconductor Market Scale and Competitive Landscape: Deep Research Report
2025 global power semiconductor market ~USD 60B; China ~USD 25B (42%). Automotive IGBT domestic rate ~67%; Tianyue Advanced SiC substrates global #1 (27.6%); Wolfspeed bankruptcy; Starpower revenue RMB 4B; Innoscience GaN enters Nvidia supply chain. Triple drivers: NEV 800V SiC + PV IGBT + energy storage PCS.
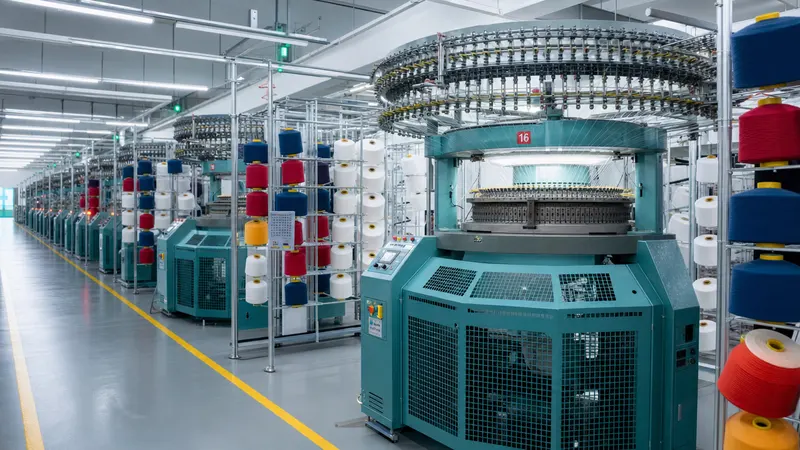
Five Trillion Yuan Output · 300 Billion Dollar Exports: 2026 In-Depth Research Report on China's Full Textile and Apparel Industry Chain
China's textile and apparel industry generates approximately five trillion yuan in annual output and nearly 300 billion dollars in exports, with chemical fiber capacity exceeding 70% of the global total. This report covers the complete industry chain from upstream chemical fibers to cross-border e-commerce, analyzing Tongkun, Shenzhou International, Hailan House, Bosideng, and SHEIN, with projections for 2026 to 2030.
2026 China Industrial Gas Industry In-Depth Report: Bulk Gases, Electronic Specialty Gases and On-Site Production in a Three-Track Race
China's industrial gas market exceeded RMB 200 billion in 2025, with electronic specialty gas localization rising from ~5% in 2020 to ~25%; semiconductor fab expansion, hydrogen energy supply chains and CCUS pilots form three demand engines. The global triad of Linde, Air Liquide and Air Products still controls over 60% of the China market, while domestic four horsemen — Hangyang, Guanggang Gas, Huate Gas and Nanda Optoelectronics — press forward on systematic catch-up.
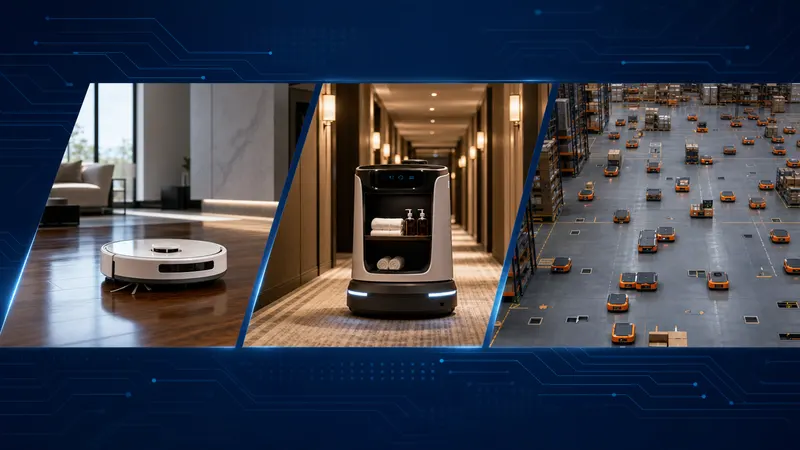
2026 China Service Robots Industry Report: Market Scale, Competitive Landscape and Forecasts (Robotic Vacuums, Commercial Delivery & Warehouse AMR)
China service robot market reached approximately ¥200 billion in 2025, capturing 40%+ of the global market. Roborock revenue hits ¥18.7B, Geek+ IPO at HK1B, iRobot bankrupt and taken over by Shenzhen OEM — this deep-dive report analyzes market scale, competitive dynamics, supply chain and 2030 forecasts across household cleaning, commercial delivery, and warehouse AMR segments.
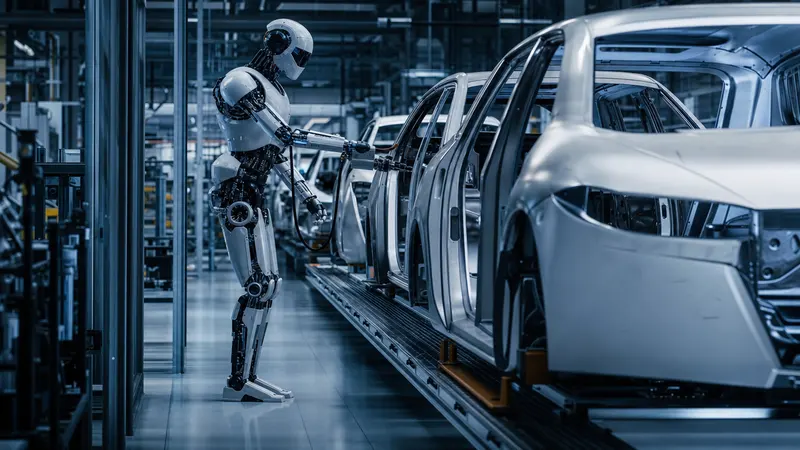
2026 China Humanoid Robot Industry Market Scale and Competitive Landscape Deep Research Report
2026 mass-production year panorama: China accounts for 84.7% of global shipments, Unitree holds 32.4% global market share, embodied AI models GR00T/Helix/GO-1 drive intelligence leap, harmonic reducer localisation accelerates — systematic overview of global landscape, supply chain deep dive, key companies and 2026–2030 market forecast.
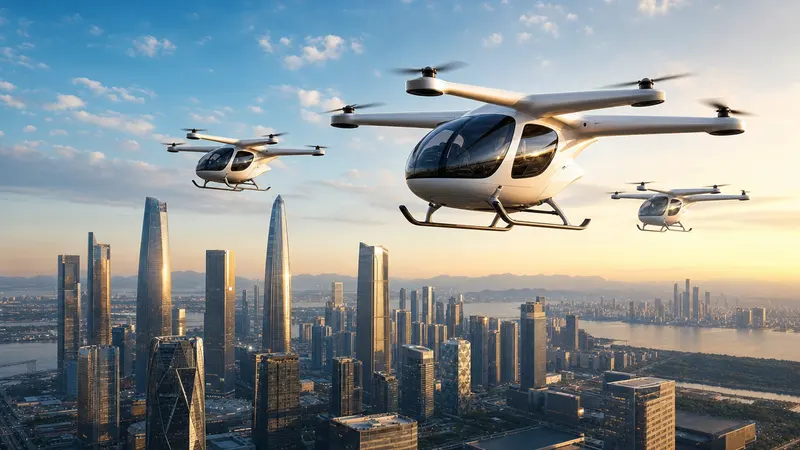
2026 China Low-Altitude Economy & eVTOL Industry: Market Scale and Competitive Landscape In-Depth Research Report
From China's 2023 'low-altitude economy' policy elevation to EHang's world-first eVTOL four-certificate commercial operations in 2025 — this report reviews market scale (670B yuan in 2024, targeting 3–5T yuan by 2030), the three-track industrial structure (GA/eVTOL/industrial drones), key company profiles, technology evolution, and core risks, with forward projections for the 2026–2030 competitive landscape.
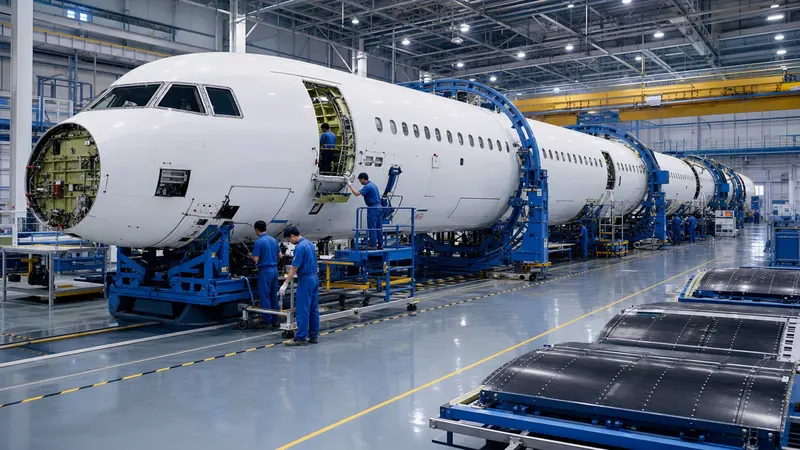
2026 China Aviation Engine & Large Commercial Aircraft Supply Chain: Industry Scale and Competitive Landscape Deep Research Report
Three parallel narratives — C919 mass production, C929 first flight, and CJ-1000A domestic engine breakthrough — simultaneously reached decisive windows in 2026. This report surveys the RMB 800 billion market across 14 chapters.
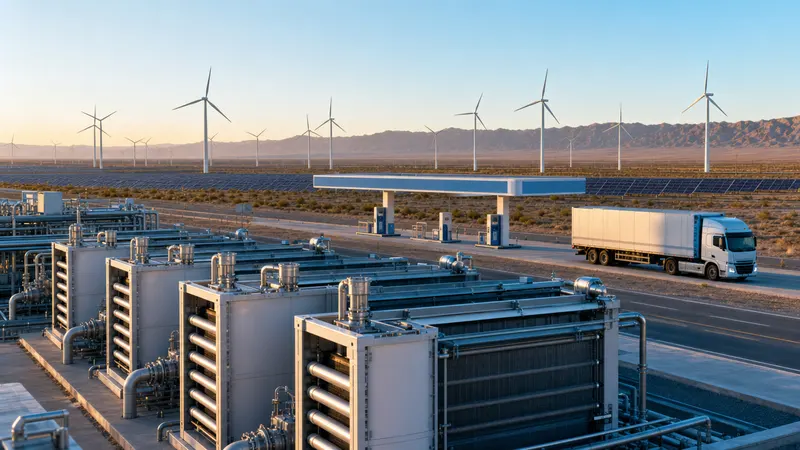
2026 China Hydrogen Energy Deep Research Report: Green Hydrogen, Fuel Cells, and Storage-Transport Full Landscape
China is the world's largest hydrogen producer at ~35 million tonnes/year, but 97%+ is grey hydrogen. In 2025, renewable green hydrogen in operation reached ~250,000 tonnes/year, fuel cell vehicle fleet stood at ~30,000, and 560 hydrogen refuelling stations were built. Cost, infrastructure, and commercial loops — three gateway bottlenecks — are determining the pace of China's journey from planning powerhouse to industrial leader.
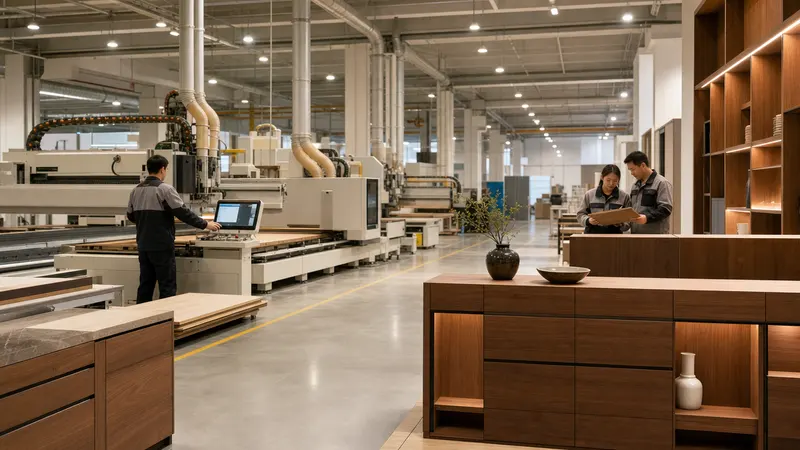
China Home Furnishing Industry 2026: Market Scale and Competitive Landscape — Custom Cabinetry, Finished Furniture, Upholstered Bedding & Smart Home
As the property-market tailwind fades, four new growth drivers emerge: whole-home fit-out, overseas manufacturing, livestream commerce, and IoT integration. Full-year 2025 data for Oppein, Kuka, Mengshen, Mousse, IKEA, and all major players — with a deep dive from panel supply chains to the global relocation of furniture clusters.
2026 China Kitchen Appliance Industry: Market Size and Competitive Landscape Deep Research Report
A comprehensive analysis of China kitchen appliance industry in 2026: panoramic scan of range hoods, gas cooktops, dishwashers, integrated cookers, built-in steam-ovens, and water purifiers; deep financial analysis of Boss, Fotile, Vatti, Marssenger and peers; multi-scenario 2030 outlook.
2026 In-Depth Research Report on China Paper Industry Market Scale and Competitive Landscape (Pulp + Paper Products + Packaging + Specialty Paper)
Based on FY2025 annual reports and 2026 Q1 data, this report comprehensively analyzes China paper industry capacity of 121.05 million tonnes, competitive dynamics among leaders Nine Dragons/Sun Paper/APP, specialty paper import substitution progress, and 2030 strategic outlook.
China Industrial Automation 2026: Servo Systems, PLC, VFD, Motion Control & Sensors — Market Size and Competitive Landscape Deep Research Report
A comprehensive deep-research report covering China's industrial automation core components market (2025–2026): servo systems, variable frequency drives, PLCs, DCS, machine vision, industrial sensors, and industrial software. Includes full competitive landscape of 14 key domestic and international companies, industry belt geography, technology roadmap, localization rates, and 2026–2030 forecasts.
2026 China Logistics & Express Industry Deep-Dive Report: 175 Billion Parcels, RMB 368 Quadrillion in Total Logistics Value, and Global Expansion
In 2025, China's express delivery reached 175 billion parcels — more than 65% of global volume — with total social logistics value hitting RMB 368 quadrillion. This report examines all five logistics tracks (general logistics, express, cold chain, instant delivery, and cross-border), analyzing SF Express, the Tongda system, J&T, JD Logistics, Cainiao, and the global trio (FedEx/UPS/DHL), projecting the industry's competitive evolution through 2030.
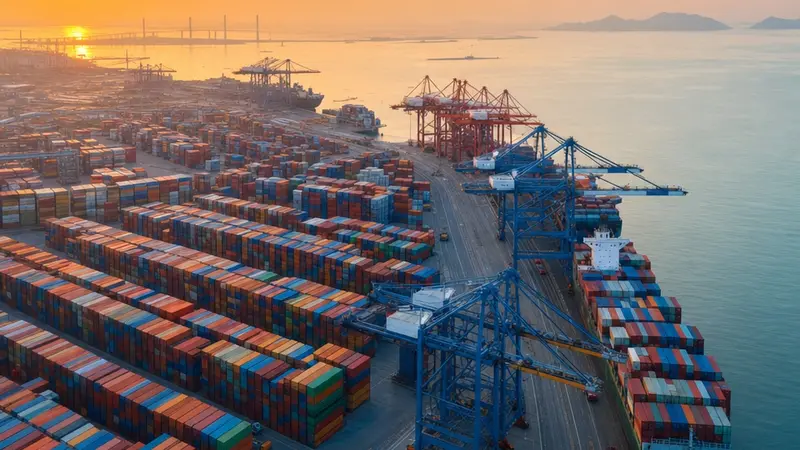
Iron Boxes for the World: A 2026 Deep Report on China's Container Industry — Market Scale and Competitive Landscape
Ninety-six out of every one hundred containers in the world are made in China; CIMC Group alone controls roughly 40% of global production capacity. This is an industry China has won — yet one still being disrupted. The Red Sea crisis pushed prices from $1,800 to $4,500 and back to $2,800; energy storage containers, refrigerated containers, and modular construction are quietly reshaping the competitive map. This report deconstructs every layer of the industry.
The Great Reversal: China Cosmetics & Daily Chemical Industry — Market Scale and Competitive Landscape Deep Research Report 2026
In 2025, China's cosmetics market reached RMB 1,004.2 billion (+2.83% YoY), with domestic brands capturing 57.37% market share — up 22 points from 2020. Proya crossed 10 billion yuan, Mao Geping delivered 84.4% gross margins, and Giant Biogene's recombinant collagen ignited a new ingredient race. This report documents how China's domestic brands achieved a historic reversal across functional skincare, livestream commerce, and emerging male and silver-age consumer segments.
2026 China Semiconductor Materials Industry (Silicon Wafers + Photoresist + Electronic Chemicals + Targets + CMP + Photomasks): Market Size and Competitive Landscape Deep Research Report
Semiconductors are called the "oil" of modern industry, yet the true bottleneck rarely sits with the chips themselves — it lies in the ultra-pure materials that make chip fabrication possible. Silicon wafers, photoresists, electronic chemicals, sputtering targets, CMP polishing materials, photomasks, and packaging substrates: each of these sub-sectors has its own technological barriers, and each is a battlefield where Chinese industry is pushing hard for domestic substitution.
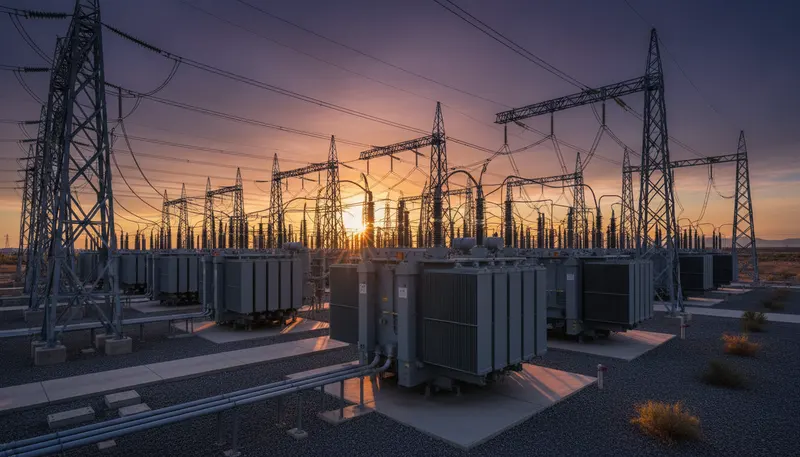
2026 China Power Transmission & Distribution Equipment Industry Report: UHV · Transformers · Switchgear · Cables · Smart Meters
State Grid and Southern Power Grid recorded combined capital expenditure exceeding RMB 800 billion in 2025 — an all-time high. Multiple ±800 kV/±1100 kV UHV lines are under concurrent construction. Transformer, switchgear, and cable exports have surged, lifting China's global market share to new peaks. This report systematically reviews the market size, competitive landscape, and technology trajectory of China's power T&D equipment sector in 2025–2026.
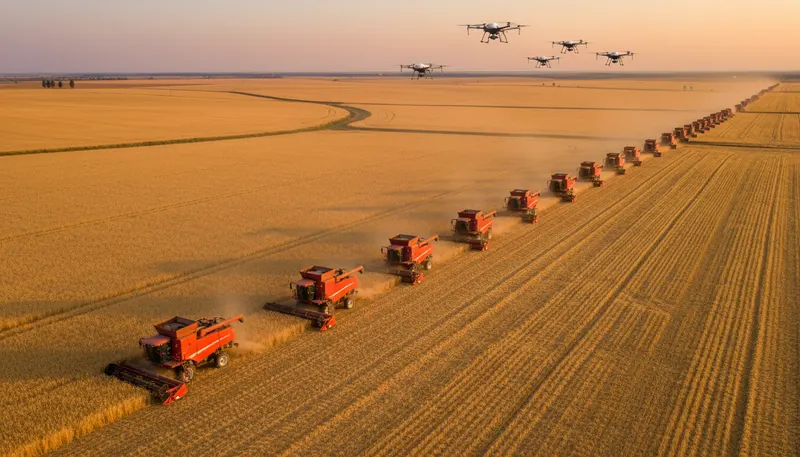
National Fortune in the Harvest Machine: The Rise and Future of Chinese Agricultural Machinery (2025-2030)
In the first half of 2025, China's agricultural machinery exports reached RMB 34.9 billion, up 37% year on year; cumulative agricultural drone holdings surpassed 500,000 units. Chinese-made combine harvesters work in Southeast Asian rice paddies, and Dongfanghong tractor orders extend to the black soil of Africa. This is the complete puzzle of Chinese agricultural machinery: a RMB 450 billion market, four narrative threads, and the restructuring of the global competitive landscape.
2026 China In Vitro Diagnostics (IVD) Industry Deep Research Report: Domestic Breakthroughs in Chemiluminescence, Molecular Diagnostics, POCT, and Sequencing
China's IVD market reached ~RMB 150–180 billion in 2025 (CAGR >12%). VBP price cuts and post-COVID consolidation are accelerating domestic substitution: chemiluminescence domestic share surpassed 40%, MGI Tech sequencer global new-unit share rose to 28%, and POCT leaders like Wondfo expanded to 150+ countries. This report covers six sub-segments — chemiluminescence, biochemistry, molecular, POCT, NGS sequencing, and pathology — with deep analysis of 30+ companies and 2026–2030 forecasts.
2026 China Heavy Truck and Commercial Vehicle Industry: Market Scale and Competitive Landscape — In-Depth Research Report
China's heavy truck sales topped 1 million units in 2025, NEV penetration reached ~23% for the year and 54% in the final month, exports hit a record ~330,000 units. Electrification, overseas expansion, and intelligent driving are reshaping a market long held by SINOTRUK, FAW Jiefang, Shaanxi Auto, Dongfeng, Foton, and Yutong. This report maps the full transformation: market scale, supply chains, enterprise financials, industrial belts, technology, and forecasts to 2030.
2026 China Building Ceramics and Sanitary Ware Deep Research: Competitive Landscape of Tiles, Sanitary Ceramics, Bathroom Hardware, and Smart Toilets
China is the world's largest building ceramics producer, with annual tile output of approximately 5.91 billion square meters — over half of global production — and a full sanitary ware value chain of approximately 600–700 billion RMB. Overseas expansion, rock slab premiumization, and smart toilet adoption are the three new growth engines. Dongpeng, Marco Polo, JOMOO, and HEGII lead domestically; Kohler, TOTO, and Geberit mine China's premium segment.
2026 China Data Center IDC & AI Computing Market: Scale, Competitive Landscape, and Industry Deep Research Report
A comprehensive analysis of China’s data center and AI computing industry (IDC operations, AI computing services, AI chips, liquid cooling infrastructure) covering market sizing, competitive dynamics, supply chain structure, and technology evolution through FY2025 and Q1 2026, with projections to 2030.
Software for a Nation: A Deep Research Report on China's Industrial Software Industry 2026
China's industrial software sector is undergoing a historic inflection point. From a domestic substitution rate below 25% in 2020 to crossing the 50% threshold in 2025, the industry has achieved a broad capability leap in five years. Yet EDA and high-end CAE remain the deepest bottlenecks, domestic ERP has begun genuine displacement of SAP and Oracle at large enterprises, and industrial AI large models are redrawing the boundaries of every industrial software category.
China Nuclear Power Industry 2026: Market Scale, Technology Routes, and Competitive Landscape — HPR1000, Guohe One, ACP100 SMR, and Generation IV
China's nuclear installed capacity reached 62.48 GW (59 units) by end-2025, surpassing the US and France combined for global No.1 in total operating+approved+under-construction capacity. HPR1000 serial construction, CAP1400 demonstration, Linglong One global first SMR, and Shidaowan Generation IV commercial operation mark five simultaneous technology milestones. This report covers technology generations, full supply chain, key enterprise FY2025 financials, and 2026–2030 market forecasts.
2026 China Satellite Internet and Commercial Spaceflight Industry: Market Size and Competitive Landscape In-Depth Research Report
A comprehensive research report mapping the deployment progress of the Qianfan G60 and GW LEO mega-constellations, reusable commercial rocket technology breakthroughs, satellite electronics supply chain ecosystem, and global player dynamics including SpaceX Starlink — covering market size, industry chain, key enterprises, risk matrix, and 2030 development forecasts.
China Testing, Inspection and Certification Industry 2026: Market Size and Competitive Landscape Deep Research Report
In 2025, China's TIC market revenue approached RMB 530 billion, ranking second globally. Over 53,000 licensed institutions issue 551 million test reports annually. This report covers the Big Four (SGS/BV/Intertek/Eurofins) FY2025 data, China sub-segment sizing, financial analysis of CTI Testing and four other listed companies, industrial-belt geography, LIMS and AI technology evolution, and 2026–2030 landscape forecasts.
2026 China Cybersecurity Industry Deep Report: Xinchuang, AI Security, Critical Infrastructure & Data Security in the Era of Domestic Substitution
China's cybersecurity market is undergoing structural transformation driven by CP 2.0 compliance, Xinchuang domestic substitution, AI-native threats, and Critical Infrastructure Protection Regulations. This report examines China's cybersecurity market scale (~RMB 135 billion, CAGR 15%), competitive dynamics, industry chain, segment evolution, and technology frontiers across FY2025 and H1 2026.
State Will in Every Seed: A 2026 Deep Research Report on China's Seed Industry
From the first commercial GMO corn deployment in 2024 to 30 million mu coverage in 2025, China's seed industry is undergoing its most profound structural transformation in a century. This report analyzes five major tracks—corn, rice, soybean, vegetable seed, and livestock/poultry breeding—and forecasts 2026–2030 market scale, consolidation paths, and competitive dynamics.
2026 China Feed and Livestock Industry Report: Market Size and Competitive Landscape (Pigs, Poultry, Aquaculture, Ruminants)
342 million tonnes of industrial feed, 4 trillion RMB in livestock output value, Muyuan at 77.98 million pigs, Haid feed sales exceeding 32.08 million tonnes — this report systematically covers China's full feed and livestock value chain scale, global competitive landscape, key enterprise 2025 financials, technology roadmap, and 2026-2030 forecasts.
China Port & Shipping 2026: Containers, Dry Bulk, Tankers, LNG, Automated Terminals and BRI Overseas Ports — Deep Research Report
Ningbo-Zhoushan Port logged its 17th straight year as the world's busiest by cargo tonnage; Shanghai led globally in container throughput for the 16th year; COSCO SHIPPING Holdings held the world's 3rd-largest container capacity. This report covers six pillars — container shipping cycles, dry bulk, tankers, LNG, automated terminals, and BRI overseas ports — reviewing FY2025 data and the 2026 outlook.
2026 China Traditional Chinese Medicine Industry Deep Research Report: Classical OTC Brands, Innovative TCM, Formula Granules and TCM Health & Wellness
China TCM industry approaches the trillion-RMB threshold, but structural polarization defines the real story: Pien Tze Huang 31% net margin alongside BuZhang losses, formula granule centralized procurement with 50% price cuts alongside Yunnan Baiyao steady growth. This report maps six TCM sub-segments (classical OTC brands, innovative TCM, formula granules, decoction pieces, TCM health and beauty, overseas expansion) and the 2025-2030 competitive landscape evolution.
The Rare Earth Chain: 2026 Deep-Dive Research Report on China's Rare Earth Permanent Magnets and Permanent Magnet Motors
China's April 2025 export controls on seven heavy rare earths and Tb/Dy-containing NdFeB magnets triggered a 40%+ PrNd price rebound. JL MAG net profit +142%, Zhongke Sanhuan +661%. This FY2025 report covers NdFeB and SmCo magnets plus permanent magnet motors across NEVs, wind, servo, appliances, and humanoid robots — analysing market size, competition, technology evolution, risks, and a 2026–2030 outlook.
2026 China Electric Two-Wheeler Industry Market Size and Competitive Landscape Deep Research Report
Focusing on four structural themes — new national standards, lithium electrification, intelligent connectivity, and overseas expansion — this report provides a systematic analysis of China's 55–60 million unit electric two-wheeler market, covering the competitive landscape, supply chain overview, and the 2026–2030 evolution trajectory.
Black Energy: 2026 China Coal Industry Market Size and Competitive Landscape Research Report
China digs enough coal in one year to stack a black mountain hundreds of times the height of Everest. This is a system that powers a quarter of the world's electricity — and its future hangs between energy security and climate commitment.
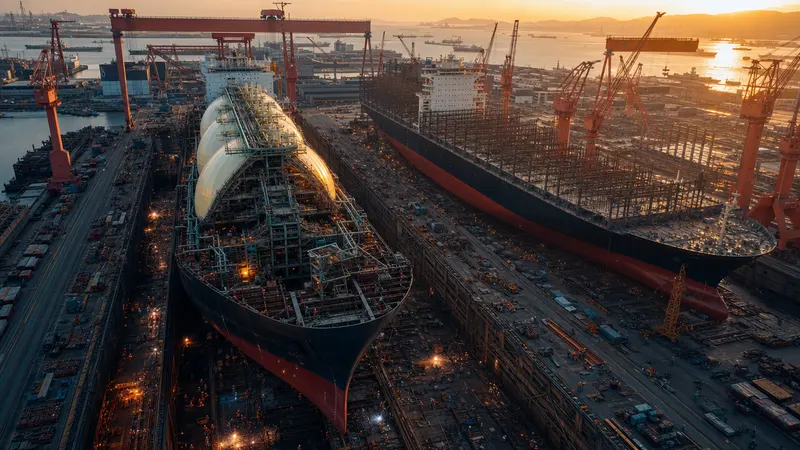
Steel on the Sea: China's Shipbuilding Industry — 2026 Market Scale and Competitive Landscape
In 2025, China completed 53.69 million DWT, received 107.82 million DWT in new orders, and held a record backlog of 274.42 million DWT — world-leading for the sixteenth year. A 55,000-character complete structural analysis across 12 chapters.
China Cross-Border E-Commerce 2026: SHEIN, Temu & TikTok Shop Reshape Global Trade - Overseas Warehouses, Logistics & Payments Deep Research Report
In 2025, China's cross-border e-commerce import and export volume reached 2.75 trillion yuan, with exports surpassing 2 trillion yuan. SHEIN pursued a Hong Kong IPO, Temu expanded into 80 countries, and TikTok Shop's global GMV doubled to USD 64.3 billion. Meanwhile, America's De Minimis exemption was eliminated in 2025, EU digital regulation tightened, and cross-border payment unicorn Airwallex surpassed a USD 6.2 billion valuation.
2026 China Infant Formula Industry (Cow Milk + Goat Milk + Organic + Cross-Border) Market Size and Competitive Landscape Deep Research Report
Declining birth rates do not prevent demand upgrading — Feihe FY2025 revenue RMB 18.11bn, domestic brands hold 80% of new national-standard registered formulas, CR10 concentration rises to 92%; goat formula market surpasses RMB 20bn, organic formula global CAGR reaches 7.6%, ultra-premium cross-border imports continue to grow. This report comprehensively analyzes China's RMB 120bn infant formula market — its competitive landscape, growth drivers, and outlook to 2030.
2026 China Beverage Industry Deep Research Report: Packaged Water, Ready-to-Drink Tea, Functional, Carbonated, Coffee and Made-to-Order Segments
A systematic overview of China's beverage market scale, competitive landscape, and industrial chain mapping for 2025–2026, covering eight major segments: packaged water, RTD tea, functional drinks, carbonated beverages, juice, herbal drinks, RTD coffee, and made-to-order coffee/tea. Includes FY2025 financials for Nongfu Spring, Dongpeng Beverage, Luckin Coffee, Mixue Group and other key players.
2026 China Agrochemical Industry (Herbicides + Insecticides + Fungicides + Biopesticides + Digital Plant Protection) Market Size and Competitive Landscape Deep Research Report
Deep research on China agrochemical industry: 2025 market ~RMB 150-180B, glyphosate recovering to RMB 26,000/t, exports hitting record highs, transgenic commercialization reshaping herbicide demand, biopesticide penetration accelerating, drone operations surpassing 2.6B mu/year. Covers FY2025 multinational performance, 14 Chinese listed companies, industrial belt geography, technology frontiers, 2026-2030 outlook.
2026 China Chemical Fertilizer Industry (Nitrogen + Phosphate + Potash + Compound + Controlled-Release) Market Size and Competitive Landscape Research Report
2026 in-depth research on China's chemical fertilizer industry: five major categories (nitrogen, phosphate, potash, compound, controlled-release), FY2025 results for global majors (Nutrien, Mosaic, CF Industries, Yara, ICL) and domestic leaders (Hualu Hengsheng, Salt Lake, Xingfa, Shidanli, Xinyangfeng, Kingenta, Yuntianhua), market size quantification, industrial belt atlas, and 2026-2030 structural transformation forecasts.
2026 China Vaccine Industry Deep Research Report: Domestic HPV Breakthrough, mRNA Transition, and Global Competitive Landscape
China's vaccine market exceeded 100 billion CNY in 2025. The launch of the first domestic 9-valent HPV vaccine, expansion of pneumococcal conjugate vaccines, mRNA platform transition, and accelerated BRI overseas expansion are deeply reshaping the entire industry chain. This report covers technology classification, global competitive landscape, PEST analysis, key company FY2025 data, industrial belt mapping, subsector deep dives, technology evolution, and 2030 forecasts.
China Frozen Food & Prepared Meal Market Size and Competitive Landscape Deep Research Report 2026
Covering two major tracks — frozen food (~CNY 213 billion in 2025) and prepared meals (>CNY 600 billion) — this report deep-dives into the financials of 11 listed companies including Anwell, Sanquan, Qianwei, Yihai International, and Shuanghui, mapping B2B central kitchen vs. C2C retail competitive logic, and forecasting the CNY 1 trillion prepared meal milestone around 2027–2028.
China AI Large Language Models and Applications (Foundation Models + Compute + ToB + ToC + Agent + Overseas Expansion): 2026 In-Depth Industry Market Size and Competitive Landscape Research Report
Anchored to June 2026, this report systematically surveys China's AI large-model full value chain — covering foundation models, MaaS cloud services, vertical industry models, ToB/ToC applications, AI Agents and overseas expansion — integrating FY2025 financial data and latest 2026 Q1 developments to present a panoramic picture of China's AI industry transitioning from the experimental period to the realization period.
2026 China Pet Food & Products Deep Research Report: Domestic Brands Surging, Fresh Food Upgrading, and Cross-Border Expansion
China's pet economy surpassed RMB 350 billion in 2025, ranking second globally. Domestic pet food brands overtook imported giants on e-commerce GMV for the first time. Three premium segments — baked food, freeze-dried main meals, and fresh food — are booming simultaneously. Five listed companies (ZooFestive, Petty, Goodwell, Yiyi, Yuanfei) anchor China's export supply chain. Smart pet products and cross-border sales are the next major growth frontiers.
2026 China Flexible Packaging Materials (BOPET + BOPP + Laminated Film + Food-Grade Aluminum Foil + Lithium Battery Aluminum-Plastic Film): Market Size and Competitive Landscape Deep Research Report
Deep research on China's flexible packaging materials: 2025 market size approx. RMB 500-550 billion, BOPET capacity near 7 million tons, BOPP over 4.5 million tons, lithium battery aluminum-plastic film domestic production exceeding 60%, Amcor-Berry Global merger reshaping global dynamics. Analysis of 11 Chinese listed companies and global giants' FY2025 results, covering five sub-tracks and 2030 outlook.
2026 China Refractory Materials Industry Deep Research Report (FY2025-2026H1)
A systematic analysis of China's refractory materials industry covering market scale, competitive landscape, supply chain structure, and global dynamics: 2025 output of 21-22 million tonnes, product-side revenue of approximately 56.3 billion yuan; the industry's core logic is shifting from 'selling products' to 'selling capabilities,' with ICM integrated contracting accelerating penetration and leading companies diverging sharply.
2026 China Water Treatment Industry Research Report: Municipal Water, Industrial Wastewater, Membrane Technology, Desalination and Smart Water Management
Water is the source of life, the foundation of production, and the bedrock of ecosystems. China sustains 22% of the world's population and the largest manufacturing sector on the planet with just 6% of global freshwater resources. The efficient use of water resources and systematic management of water environments have always been central to national ecological civilization. As China moves from the conclusion of its "14th Five-Year Plan" into the opening phase of the "15th Five-Year Plan," the w
2026 China Additive Manufacturing and 3D Printing: Market Scale, Competitive Landscape & 5-Year Outlook
A comprehensive analysis of the global USD 30.5B and China RMB 52B additive manufacturing market in 2025, featuring in-depth financials on BLT, Farsoon, 3D Systems, Stratasys, and Desktop Metal bankruptcy, with vertical application deep-dives and 2026–2030 forecasts at 24% CAGR.
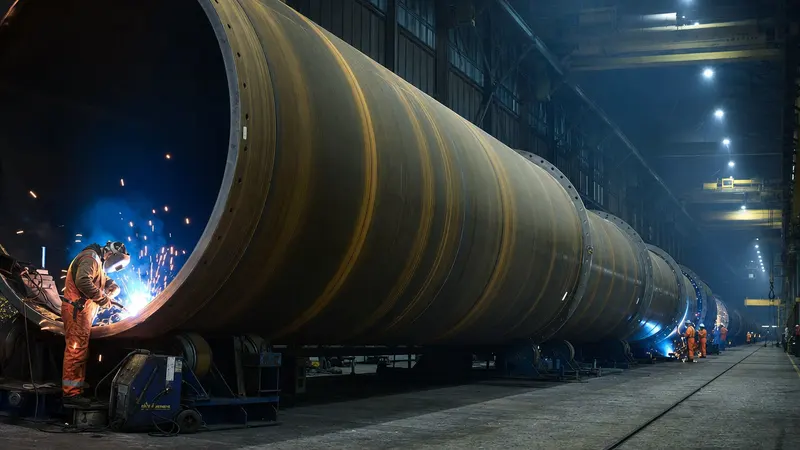
China Wind Power Components Deep Report 2026: Blades · Towers · Main Shafts · Flanges · Gearboxes · Offshore Monopiles · Wind Power Castings
A comprehensive analysis of China's seven core wind power component segments (blades, towers, main shafts, flanges, gearboxes, offshore monopiles, and castings) covering 2025 market size, technology evolution, and competitive landscape of leading enterprises including SINOMA, Riyue, and Oriental Cable, with a 2026-2030 outlook.
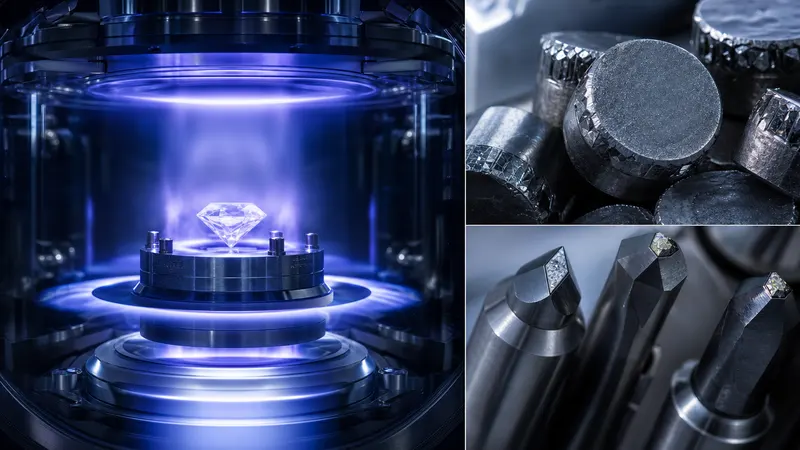
China Superhard Materials 2026: A Full-Spectrum Analysis of Synthetic Diamond, Lab-Grown Diamond, CBN and Industrial Coatings
A comprehensive analysis of China's superhard materials industry: from the price cycle of industrial diamond and lab-grown diamond to the rise of CVD diamond heat spreaders and quantum materials, covering market scale, FY2024 financials of leading companies, a nine-stage value chain breakdown, and five structural forecasts for 2026–2030.
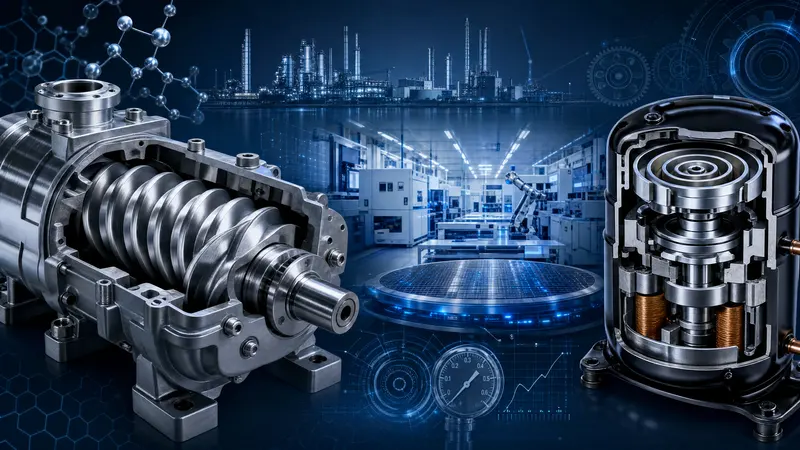
2026 China Vacuum Pump & Compressor Industry Deep Research Report
Comprehensive analysis of industrial vacuum pumps, semiconductor dry pumps, refrigeration compressors: market scale CNY 11.7B, localization progress, refrigerant transition, and 2026-2030 strategic outlook.
China Machine Vision Industry 2026 — From 3C Inspection to AI-Driven Visual Intelligence Across Manufacturing
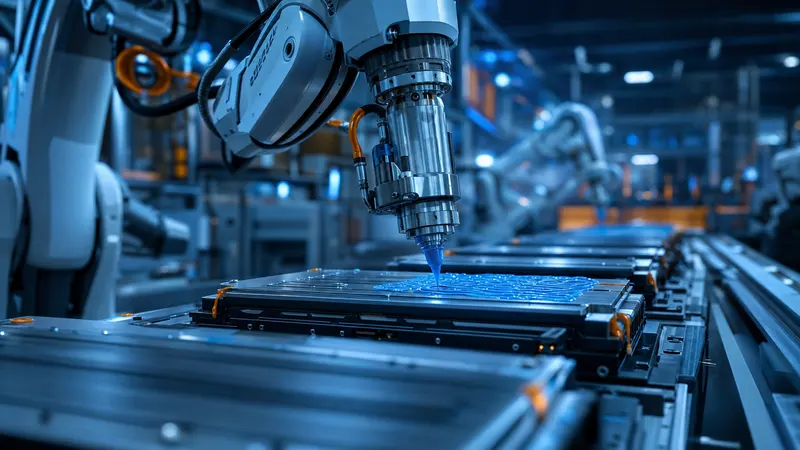
China Industrial Adhesives Industry 2026 — Sub-Segment Localization from Silicones to Lithium Battery Structural Adhesives
A systematic overview of China's industrial adhesives industry in 2026: seven chemical systems, six functional categories, and a domestic substitution matrix across all sub-segments, with focus on the three frontier areas — lithium-battery thermal adhesives, automotive BIW structural adhesives, and OCA optical adhesives. Includes financial and strategic analysis of Huitian New Materials, Guibao Technology, and other leading domestic players.
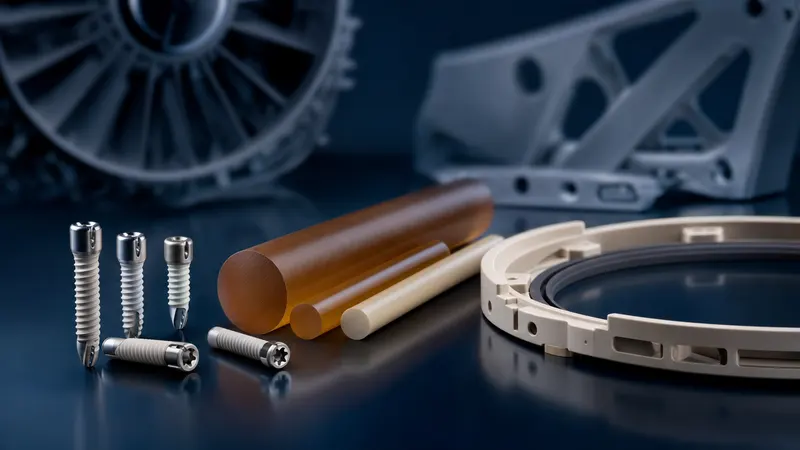
China PEEK & High-Performance Engineering Plastics 2026 — From Victrex Dominance to a Three-Pillar Domestic Breakthrough
From ICI's 1978 PEEK synthesis to China's 2026 thousand-tonne domestic production, this report maps the global competitive landscape, industrial chain value distribution, player financials, and domestic substitution progress across PEEK, PI, PPS, LCP, and PEI.
China Electronic Specialty Gases 2026 — Semiconductor Localization Breakthrough at the Critical Chokepoint
Electronic specialty gases are strategic consumables in semiconductor manufacturing, with prices multiples of gold by weight. In 2026, two major Japanese WF6 suppliers permanently exited due to China's tungsten export controls, handing China the fastest single-category global share restructuring in ESG history. This report covers NF3/WF6/SiH4 category dynamics, 8 A-share listed companies, three-tier localization progress, and a 5-year trend analysis anchored to June 18, 2026.
China Machine Vision Core Components 2026 — Localization Map for Industrial Cameras, Lenses, Light Sources, and Frame Grabbers
A comprehensive 2026 analysis of China machine vision core components—industrial cameras, optical lenses, LED light sources, frame grabbers, and 3D vision modules—covering market sizing, a four-tier localization map, key players, and technology trends across the full supply chain.
China Precision Bearing and Ball Screw Industry 2026 — The Precision Lifeline of Machine Tools, Robots and EV Powertrains
A panoramic 2026 report on China's precision bearing and ball screw industry: domestic substitution tiers, upstream bearing steel, precision grinding, six downstream battlefields (machine tools, robots, wind power, high-speed rail, EV, semiconductors), planetary roller screws in humanoid robots, and supply-chain insights from 4.8 million verified factory records.
China Semiconductor Photoresist 2026 — A Five-Generation Climb from i-line, KrF, ArF to EUV
A comprehensive deep dive into China's semiconductor photoresist industry: five-generation technology evolution (g-line/i-line/KrF/ArF/EUV), Japan's global monopoly, domestic breakthroughs by Nanda Optoelectronics, Tongcheng/Beijing Kechuang, and peers, plus the 2026 localization roadmap and risk assessment.
China EDA Software Industry 2026 — From Synopsys Triopoly to the Domestic Trio of Empyrean, Primarius & Broadway Tech
A comprehensive analysis of the global EDA triopoly's dominance, the technical roadmaps and financials of China's leading domestic EDA companies (Empyrean, Primarius, Broadway Tech, Xinyuazhang), the impact of US export controls, Big Fund III catalysis, AI-EDA trends, and the realistic progress of domestic substitution with a 2030 outlook.
China's Industrial Tape 2026 — The Localization Climb from Release Films to High-End OLED Membrane Materials
A systematic review of China's industrial tape industry covering PSA tape, release films, OCA optical adhesives, and OLED process films — mapping the supply chain, competitive landscape, domestic substitution trajectory, and structural opportunities through 2028.
China PCB Substrate CCL Copper Clad Laminate 2026 — From General FR-4 to High-Frequency, High-Speed and Package Substrate Breakthroughs
Deep research on the global CCL copper clad laminate market in 2026: AI server-driven high-speed CCL boom, Shengyi M9 NVIDIA certification breakthrough, ABF substrate supply gaps, domestic substitution tiers and M&A landscape.
China MEMS Sensors 2026 — From Consumer Acoustics to Industrial Inertia: A Dual-Track Domestic Breakthrough
An in-depth analysis of China's MEMS sensor industry covering acoustic, inertial, pressure, RF, optical, and bio-MEMS categories: global competitive landscape, domestic substitution tiers, supply chain depth, key player profiles, investment trends, and 2026–2030 forecasts grounded in data from 4.8 million factories.
China Industrial Ceramics 2026 — From Alumina and Silicon Nitride to Semiconductor Wafer Carrier Breakthroughs
A comprehensive 2026 research report on China's advanced ceramics industry, covering alumina, silicon nitride, aluminum nitride, silicon carbide, and sapphire material systems; semiconductor electrostatic chucks and wafer carriers; power module substrates; 5G filter ceramics; domestic substitution progress; and Tianxia Gongchang factory database insights.
China Electronic-Grade High-Purity Silicon Chemicals 2026 — Closing the Loop on TEOS, HMDS and Polysilicon Precursors
A comprehensive deep dive into China's electronic-grade silicon-based chemicals industry across eight product categories (TEOS, HMDS, high-purity polysilicon, silane coupling agents, D4, high-purity quartz sand, electronic-grade SiO2, and silicone gels): global landscape, supply chain structure, investment analysis, domestic-substitution profiles, and future trends.
China Machine Vision Algorithm SDK 2026 — From HALCON Dominance to VisionMaster's Domestic Rise
An in-depth analysis of China's industrial machine vision SDK market: from HALCON's historical dominance to the rise of domestic SDKs like VisionMaster and VisionWARE, covering FY2025 financial data, AI vision emerging scenarios, business model evolution, and 2030 forecasts.
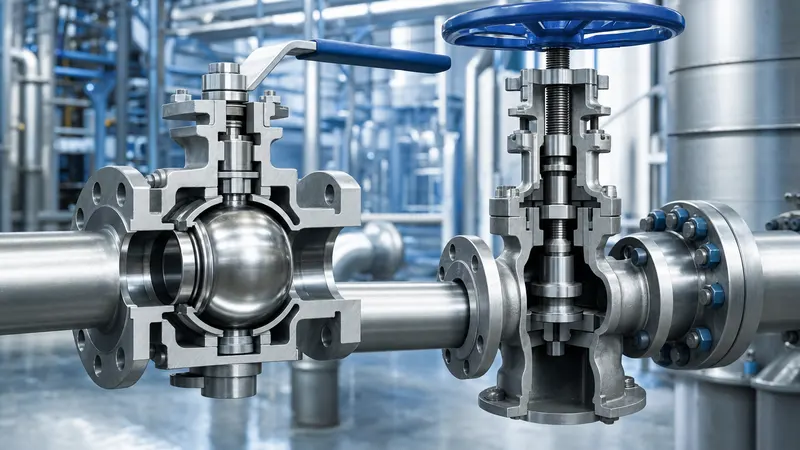
China Industrial Valve 2026 — Breaking Through in Nuclear Ball Valves and LNG Cryogenic Valves
Driven by batch nuclear power construction, rapid LNG expansion, hydrogen energy development, and semiconductor capacity growth, China's industrial valve industry is accelerating its transformation from mid- to low-end general components toward high-end categories such as nuclear-grade ball valves, LNG cryogenic valves, hydrogen-station valves and semiconductor specialty valves.
China Industrial Pump Industry 2026: Full-Spectrum Localization from Chemical Process Pumps to Nuclear Reactor Coolant Pumps
Industrial pumps are the most widely used fluid machinery in manufacturing. This report covers centrifugal pumps, magnetic drive pumps, canned motor pumps, reactor coolant pumps, slurry pumps, and metering pumps—providing a comprehensive 2026 outlook on China's industrial pump industry including global market structure, technology barriers, supply chain analysis, localization progress, and future trends.
China Industrial Metrology 2026 — Domestic Breakthrough from CMM to Laser Trackers
A comprehensive analysis of China's industrial metrology industry — from CMM, structured-light scanning, and laser trackers to industrial CT — covering market structure, four-tier domestic substitution framework, key players, and strategic outlook for 2026–2030.
China Mobile Robots AGV/AMR 2026 — Collaborative Vehicle Intelligence from Warehouse Logistics to Flexible Production Lines
China's AGV/AMR market reached RMB 19.665 billion and 158,300 units in 2024, covering e-commerce warehousing, new energy vehicles, lithium batteries, and 3C electronics. This report analyzes the AGV vs AMR technology divide, competitive landscape, key technology trends, typical industry applications, export competitiveness, supply chain value distribution, and lifecycle ROI.
China Collaborative Robot 2026 — From JAKA and Dobot to ABB Yumi, A New Human-Robot Co-Line Industrial Order
A comprehensive 2026 research report on China's collaborative robot industry. Covering market landscape, core technologies, supply chain, applications, key players, domestic substitution trends, investment, and research judgments based on data from 4.8 million verified factories.
China Semiconductor CMP Pad and Slurry 2026 — From DuPont Monopoly to Dual Domestic Substitution by Dinglong and Anji
A comprehensive 2026 analysis of China's semiconductor CMP polishing pad and slurry industry: DuPont's global dominance, Dinglong and Anji Microelectronics' domestic substitution progress, SiC CMP emerging markets, policy tailwinds, and investment outlook. Data current through June 20, 2026.
China High-Purity Metal Sputtering Targets 2026 — Domestic Breakthrough from Semiconductor Cu/Al Targets to Display ITO
Sputtering targets are the core PVD consumables for semiconductor, display, and photovoltaic manufacturing. This report systematically analyzes the global landscape, domestic substitution progress, and competitive positioning of key players across Cu, Al, Ta, W, Ru, and ITO categories, anchored to the latest 2026 data.
China Superalloys and Single-Crystal Turbine Blades 2026 — The Last Mile of Aero-Engine Localisation
A full-spectrum analysis of China's superalloy and single-crystal turbine blade industry in 2026: localisation milestones from DD6 to DD9, powder metallurgy turbine discs, thermal barrier coatings, and structural opportunities across the five-year outlook.
China CNC Controller 2026 — The Domestic Substitution Battle for the Industrial Mother Machine Brain
An in-depth analysis of China CNC system market in 2026: technology tiers, leading players, domestic substitution progress, AI-enabling trends across 14 key themes.
China High-End Connectors 2026 — Domestic Breakthrough Driven by AI Servers and EV Powertrains
In 2026, China's high-end connector industry stands at a historic inflection point: NVIDIA GB200/GB300 AI computing rack 224G high-speed interconnect demand, 800V EV liquid-cooled high-voltage connector deployment at scale, and defense procurement recovery are collectively accelerating domestic substitution from consumer electronics into premium connector segments. This report covers 14 dimensions and presents three core judgments and a systemic risk framework.
China Carbon Fiber 2026: From Wind Blades to Large-Tow, Localization at the Crossroads
China's carbon fiber industry in 2025: 162,000 tonnes capacity, 96,400 tonnes consumption, over 80% localization, 60%+ global share in large-tow, profit per tonne at just 330 RMB. A 14-chapter map from precursor to wind blades, hydrogen tanks, aerospace, low-altitude, and robotics—analyzing the three-year high-end localization window and five-year competitive evolution.
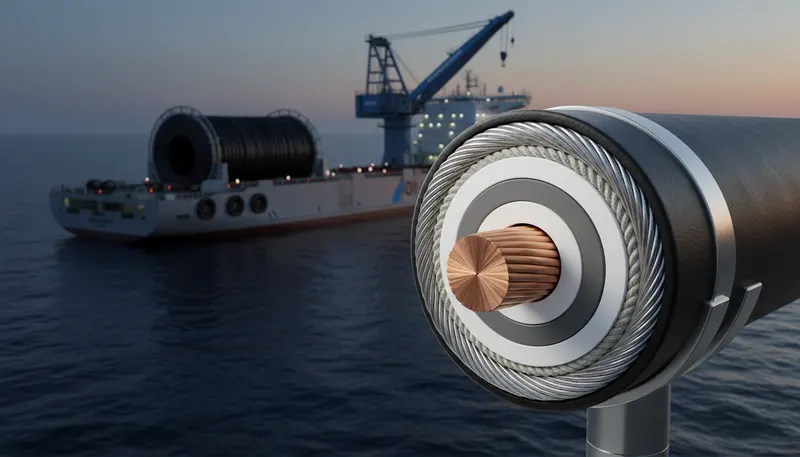
China Submarine Cable 2026: Dual Drivers from Offshore Wind and Cross-Sea Interconnection
China Fluorochemicals 2026 — Refrigerant Quotas Capped and the Fluorinated New-Materials Breakthrough
Fluorochemicals connects fluorspar mines to new-energy, semiconductors, hydrogen, and home appliances. After China's 2024 HFC quota system, R32 rose 4x to 110,000 yuan/ton; meanwhile fluoropolymers (PTFE/PVDF/FKM) and electronic fluorochemicals (LiPF6, EG-HF, PFSA membrane) are breaking through. Covers fluorspar resources, refrigerant generations, eight players, quota dynamics, new materials, policy, and 3-5 year outlook.
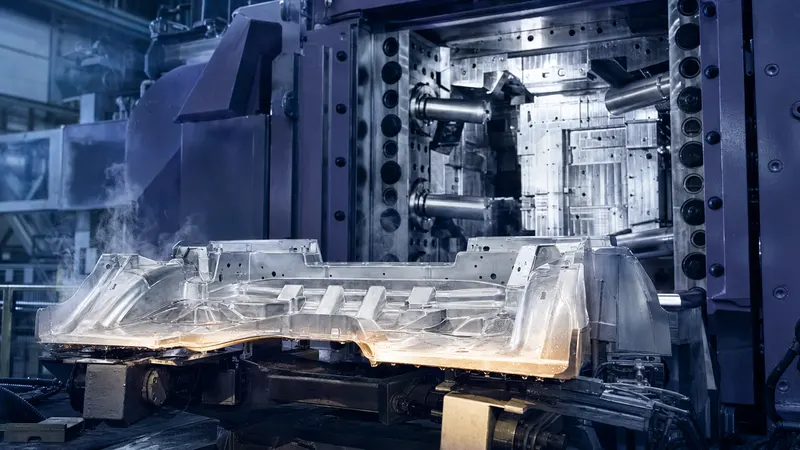
China Integrated Die-Casting 2026: The 9000T Mega-Press Wave and NEV Body Reconstruction
In 2025 China integrated die-casting structural-parts market crossed thirty billion yuan; close to twenty 9,000-ton mega presses now installed; 16,000-ton class running at XPeng P7+ and Hongtu Guangzhou. A 14-chapter picture from heat-treatment-free alloy, mega molds, mega presses to Tier1 casters and OEM programs — localization milestones, the economic argument, insurance and crash dynamics, and the five-year landscape evolution.
China Glass Fiber 2026: The Dual Front of Wind Yarn and Electronic Yarn
In 2026 Owens Corning formally completes its global Glass Reinforcements divestiture; the industry enters a China-dominant, Japan-specialty two-pole era. China's yarn output reaches 8.43M tons (~70 percent global). Wind yarn is pulled by offshore scale-up; electronic yarn and cloth enter a decade-tightest shortage on AI compute demand. This report covers furnace scale-up, generations, corporate landscape, substitution, cycles, policy, and risks.
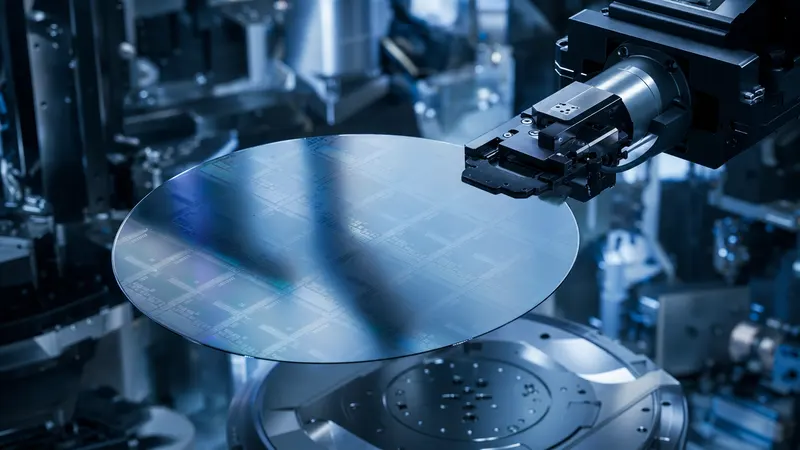
China Wafer Foundry 2026: Mature-Node Expansion Wave and Advanced-Node Breakthrough
In 2025 mainland China wafer foundry approached RMB 200B revenue, 1.2M 12-inch wpm, utilization 90%+; SMIC's USD 9.3B revenue lifted it to global #2; N+2/N+3 serves Huawei Kirin and Ascend. This 14-chapter report covers industry overview, node breakdown, process barriers, key players, capacity, advanced-node breakthrough, supply chain, price war, capex, policy, customer structure, scenarios and risks.
China Titanium Alloy 2026 — Domestic Breakthrough in Aerospace High-End Materials
Sponge titanium capacity 75% of global; aerospace titanium share jumped from <5% (2020) to 22% (2025); ~7 tons titanium per COMAC C919. But highest-end grades TC21, Ti60 still in engineering ramp; process database gap to VSMPO remains the core unfinished work. From midstream processing lens, this report unpacks Chinese titanium capacity, price cycle, process barriers, downstream map, import substitution, industry belt, and five-year key nodes.
2026 China High-Purity Quartz Sand: Twin-Track Battle in PV Crucibles and Semiconductor Quartz
From RMB 300,000 to 50,000 per tonne in three years — the price cliff masks a twin-track divergence: PV-grade 4N8 has cleared substitution while 5N semiconductor-grade remains 95% import-dependent. This research institute report dissects ore sources, processing barriers, manufacturers, pricing, policy and risks for a 3-to-5 year industry framework.
China Polysilicon 2026 — Top-Tier Cost Discipline and the N-Type Granular Breakthrough
Deep 2026 research on China polysilicon: 3.2M tonnes capacity vs 1.1M demand (2.9x oversupply); prices crashed from RMB 300K to 40K/tonne; Tongwei, GCL, Daqo, Xinte, Asia Silicon vs Wacker, Hemlock, OCI in N-type era; granular share rises to 24%; USD 5B integration fund; Oman/Indonesia/Malaysia overseas bases; EU CBAM and green silicon; 'four-plus-two' 2030 forecast.
2026 China Phosphate Chemicals: From Phosphate Rock to LFP Cathode — Industrial Chain Integration
Deep research on the 2026 China phosphate chemicals industry: covering rock, yellow phosphorus, industrial phosphoric acid, iron phosphate, LFP cathode, glyphosate, and fertilizer; analyzing Yuntianhua, Xingfa, Hubei Yihua, Chuanfa Longmang, Chuanheng vs OCP, Mosaic, Nutrien, PhosAgro, EuroChem; five structural shifts 2026-2030: integration, mining rights, new energy, green low-carbon, China-Morocco duality.
China Tungsten and Molybdenum Alloys 2026: Strategic Metals Across Cemented Carbide, Photovoltaic Tungsten Wire and High-end Equipment
A comprehensive analysis of China's tungsten-molybdenum alloys chain — from Jiangxi-Hunan tungsten and Henan-Shaanxi molybdenum, through APT/W-powder/cemented-carbide midstream, covering FY2025 results of China Tungsten & Hightech, Xiamen Tungsten, CMOC, Jinduicheng Molybdenum, Zhangyuan Tungsten with Sandvik/Plansee/Kennametal benchmarks, the APT price doubling to RMB 780K/ton, the Feb 2025 export controls, four emerging downstream applications, and five structural judgments for 2026-2030.
China Memory Chip 2026: DRAM, NAND Twin Breakthrough and HBM On-Board
A full-landscape research on China memory chip industry 2026 — YMTC NAND, CXMT DRAM, domestic HBM, and module ecosystem advancing in parallel; generation gap and breakthrough paths versus SK Hynix, Samsung, Micron, Kioxia. Fourteen chapters of in-depth analysis.
2026 China Polyurethane MDI Industry Research Report: Wanhua Integration and Global Pricing Power
2026 China Polyurethane MDI industry report. From 2025 global MDI/TDI oligopoly, Wanhua integration, upstream aniline and PO chain, downstream rigid/flexible foam and CASE TPU, to 2024-2026 price cycle, policy, and 2026-2030 outlook with risks.
China Semiconductor Silicon Wafer 2026 — The 300mm Localization Push
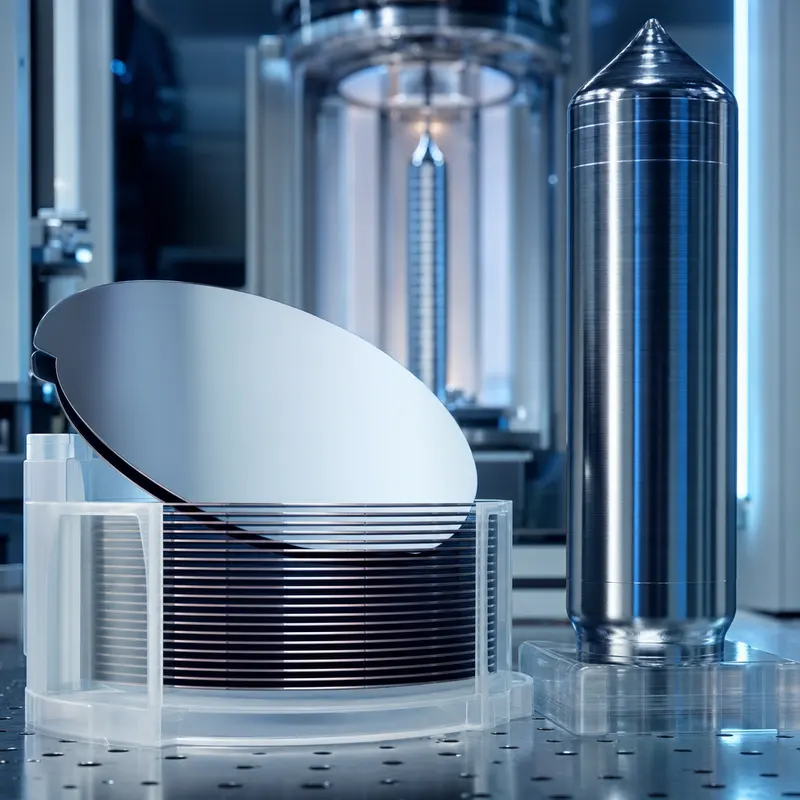
2026 China semiconductor silicon wafer deep research: USD 13.6B global market with five oligopolies at 90% share; Shin-Etsu/SUMCO/GlobalWafers/Siltronic/SK Siltron vs NSIG/Sien/TCL Zhonghuan Lingxian/GlobalWafers-China/Beijing Yanyu Semiconductor; 300mm polished localization 35%, epi only 15% still bottleneck; electronic-grade 11N polysilicon, 72-hour CZ pull, zero-tolerance CMP; SUMCO 15% epi hike in 2026; Big Fund Phase III RMB 344B; 2030 55% composite localization path.
China Titanium Dioxide 2026 — Chloride Route Replacing Sulfate and Global Export Pricing Power
Deep 2026 research on China TiO₂: 9.4M t global capacity vs 7.45M demand; China 64% of output, 51% of exports; CR5 58%, chloride 31%; Longbai Jiaozuo 500K-t chloride line pushes cash cost to RMB 10800/t; 2.07M t exports vs global AD encirclement; ilmenite Africanization accelerates; EU PFAS+CBAM + China dual-control; industry margin recovers from 20.1% to 27% by 2030.
China Electrolytic Copper Foil 2026: The 4.5μm Ultra-Thin and HVLP High-Frequency Dual-Track Breakthrough
China's electrolytic copper foil industry enters 2026 recovery: 2.07 million tons capacity; Jiayuan hit a record 9.64 billion yuan in 2025 while Norde posted a second 260 million yuan loss; 4.5μm lithium foil 100% localized, 4μm under attack, HVLP-3/4 still choked. This report maps the process chain, six Chinese leaders vs four overseas giants, power battery + AI server dual downstream, the composite foil threat, and 2026-2030 supply-demand projections.
China PV Encapsulation Film 2026 — From Transparent EVA to POE Co-Extrusion for the N-Type Upgrade
Deep 2026 research on China PV encapsulant: 8B m² global demand vs 5.2B m² China capacity; EVA transparent prices fell from RMB 22 to 8.8/m²; Foster, Hiuv, Cybrid, Sveck vs Mitsui, Bridgestone, 3M; EPE co-extruded share from 3% to 30%; N-type TOPCon and HJT drive POE/EPE adoption; POE 75% controlled by Dow, ExxonMobil, Mitsui with Wanhua, Satellite breaking through; CBAM, UFLPA, IRA triple policy battle; 2030 ten-trend outlook.
China Industrial Power Supply 2026 — Server PSU, Storage PCS, and Industrial Control Power as the Three Main Battlegrounds
Comprehensive analysis of China's industrial power supply sector in 2026: AI server PSU, storage PCS, UPS, HVDC, specialty power; upstream SiC/GaN/IGBT/magnetics/capacitor supply chains; major players; price cycles and policy; strategic outlook through 2030.
China's Environmental Protection Equipment 2026: Full-Chain EPC and O&M Transition for Industrial Flue-Gas, Wastewater and Hazardous Waste
Anchored to FY2025 annual reports and H1 2026, the report covers four main lines (atmospheric treatment, industrial VOCs, solid and hazardous waste, flue-gas treatment), conducts deep dives on the six listed leaders — Qingxin Environment, Longking, Feida, Fulongma, Jingjin Equipment and Yongqing — and benchmarks them against Veolia, SUEZ, Xylem and Evoqua to systematically interpret import substitution, capacity expansion, pricing cycles and policy roadmap.
China Industrial Welding 2026
2026 China industrial welding research report.
China Data Center Liquid Cooling 2026 – AI Compute Demand from Cold Plate to Immersion
AI compute drives liquid cooling to the data center main stage: China's 2025 liquid cooling market reaches RMB 14.9-16 billion with about 33% penetration.
China Food Packaging Machinery 2026: High-Speed Aseptic Filling and PET Line Localization
A systematic review of the 2025-2026 China food packaging machinery market, PET blow molding and aseptic filling processes, financial performance of domestic leaders Tech-Long and Newamstar, benchmarked against global giants Krones, Tetra Pak, and Sidel, with deep analysis of the PET line localization roadmap and capex cycles in downstream beverage and food factories.
China Dyes & Pigments 2026 — Oligopoly in Disperse/Reactive and High-End Pigment Breakthrough
Deep 2026 research on China dyes and pigments: 1.1M-t output at 60% global share; Longsheng/Runtu/Jihua disperse CR3 60%+; Runtu H acid self-sufficiency 80%; Lily/Caihong high-end pigment localization (DPP, quinacridone); reduction-product 300% surge driving Q1 2026 rebound; EU PFAS+ZDHC+REACH compliance reshaping; 2027-2030 consolidation outlook.
China Chlor-Alkali and PVC 2026 — Carbide vs Ethylene, and the Western Energy Arbitrage Rewriting Industrial Geography
Chlor-alkali is China's largest inorganic chemical subsector: 52 Mt caustic and 29.2 Mt PVC capacity in 2025 (47% and 40% global). This report covers electrolysis, carbide vs ethylene battle, Western energy arbitrage, 12 key players, caustic and PVC downstream maps, price cycles, EU CBAM and anti-dumping dynamics, and 3-5 year outlook.
China High-Pressure Cylinders 2026 — Twin Ramp of 70 MPa Type-IV Hydrogen Storage and LNG Mobile Tank Containers
China's 2025 high-pressure cylinder market reached RMB 124 billion. 35 MPa Type-III is nearly fully localized; 70 MPa Type-IV just crossed national-standard certification; LNG-heavy-truck penetration is rising fast; industrial cylinders provide stable cash flow. This 14-chapter report maps the chain from carbon fiber to cylinder valves and the next 5-year evolution.
China Amino Acids 2026 — Global Feed Export Dominance and the Small-Variety Breakthrough
2026 deep research on China amino acids: China holds 76% global lysine and 93% threonine; five leaders — Meihua (RMB 24.2 bn + 1.3 mn t Jilin lysine #1), Fufeng (RMB 27.9 bn + Kazakhstan base), Xinghu (Yipin + Heilongjiang 450k t), Huaheng (synthetic biology), Angel Yeast (global YE #1); July 2025 EU AD 47.7-58.3% + April 2026 anti-absorption; 14 chapters cover corn, strain, fermenter, low-protein diet, small varieties, pharma-grade, overseas — full 2026-2030 four-plus-two outlook.
China Cutting Tools 2026: High-End Domestic Substitution of Carbide Indexable Inserts
Global metal cutting tools market USD 46.6 billion; China RMB 54 billion. From Zhuzhou Diamond, Oke Precision, Huarui Precision to Worldia and Hengfeng Tools, domestic indexable insert localization has exceeded 70%. Next 3 to 5 years are the critical window from mid-low to mid-high end.
China Special Steel 2026 — High-End Import Substitution in Bearing and Tool & Die Steel
Deep 2026 research on China midstream special steel: 84M-tonne output, purity migration, large-forging competence, the 3-to-5-year high-end substitution window; CITIC, Fushun, Baowu Tegang, Northeast, Xining, Daye vs Voestalpine, Tata, Sandvik, NSSMC, Daido, SeAH; GCr15 bearing and H13/718H/SKD11/SKH-9 die-steel downstream mapping; four-tier high-end tiers and pacing.
China Industrial Hydraulics 2026 — High-end Domestic Substitution from Excavator Cylinders to High-pressure Piston Pumps
China Offshore Engineering Equipment 2026: Premium Breakthrough in Wind Installation Vessels and Deep-Water Drilling Platforms
Global offshore engineering equipment hit 75 to 88 billion US dollars in 2025; Chinese yards captured 31.2 billion (41.2 percent global). WTIV is in short supply; deep-water drillship and FPSO orders rebound. Six firms (CSSC Offshore, CNOOC Engineering, Zhenhua, China Merchants, CIMC Raffles, Waigaoqiao) split workload. DP3, deep-sea pressure, and work-class ROV localization decides the 3 to 5 year premium breakthrough window.
China Copper Smelting 2026 — The Race for Overseas Copper Mines and Global Cathode Pricing Power
2026 China copper smelting: cathode 13.64 Mt (47% global); concentrate dependency 78%; TC/RC at -$8/ton; LME on $10,000 plateau. Six leaders — Jiangxi Copper, Tongling, Zijin (Kamoa + Julong), China Molybdenum (KFM + Tenke), Jinchuan, China Copper. 14 chapters: process, mining, midstream, three downstreams, expansion, cycle, dual-carbon, eight-drivers outlook.
China Aluminum Smelting 2026: Alumina Value-Chain Integration and the Electrolytic-Aluminum Green-Power Revolution
In 2025 China's electrolytic-aluminum output hit 43.7 Mt — 59.8 percent of global; operating capacity touched 44.2 Mt against the 45 Mt policy ceiling. Under the triple overlay of EU CBAM collection from Jan 2026, Guinea export-policy tightening, and super-linear NEV battery-foil demand, top producers keep migrating capacity to Yunnan hydropower aluminum. This 14-chapter report covers upstream bauxite, process, green-power replacement, recycled aluminum, capacity, prices, policy, and risks.
China Plastic Pipe Industry 2026 — The Three Resin Oligopolies (PPR, PVC, PE) and Overseas Penetration
Plastic pipes are the quiet workhorse of China's construction and municipal infrastructure. 2025 output 16.5 Mt (41% global), industry revenue RMB 258 bn. Covers PPR/PVC-U/PE/PEX/PB, extrusion and corrugated processes, Chinese leaders (Lesso, Weixing, Eric) versus global majors (Aliaxis, Wavin, Pipelife, Orbia, Georg Fischer), price cycles, export expansion, policy tailwinds, and the 3-5 year outlook.
China Sweeteners 2026 — Sucralose and Erythritol Global Export Oligopoly
Deep 2026 research on China sweeteners: Jinhe leads acesulfame and sucralose; San Yuan leads erythritol; Layn leads monk fruit; Bao Ling Bao anchors Yucheng hub; China holds 85%+ sucralose, 60%+ acesulfame, 65% erythritol, 80% stevia, 90% monk fruit; benchmarks Tate & Lyle, Ingredion, Cargill, ADM, Ajinomoto; full 2024-2026 cycle; 14 chapters.
China Vitamins 2026 — VA/VE/VD3 Oligopoly and Global Export Pricing Power
2026 deep research on China vitamins: DSM-Firmenich EUR 2.2 bn ANH divestment to CVC hands global VE pricing power to Xinhecheng + Nantekang/JV + Zhejiang Medicine; Garden Bio holds 70% global NF-grade cholesterol + #1 VD3; 2024 BASF Ludwigshafen explosion + H1 2026 Middle East geopolitics dual pulses; 14 chapters on 2026-2030 China vitamin pricing power + high-end + synthetic biology.
China Mechanical Seals 2026 — Hidden Champion Cdsii and High-End Domestic Substitution
China Mechanical Seals 2026 in-depth report: focusing on the pattern evolution between local leaders like Cdsii and global giants like John Crane, EagleBurgmann, Flowserve, AESSEAL — decomposing the three high-end breakthrough battlegrounds of dry gas seals, nuclear primary pump seals, and gas turbine seals.
China Powder Metallurgy 2026: The Dual-Track Breakthrough of MIM and High-End Metal Soft Magnetic Powder Cores
Powder metallurgy is long underestimated by outsiders, but China hit nearly RMB 48 billion in 2025 at 12% CAGR. Press-and-sinter, MIM, metal soft-magnetic cores, and 3D printing metal powder are four sub-tracks with vastly different growth. This report covers leading players, overseas giants, four downstream drivers (foldable, EV OBC, AI servers, COMAC), 3-5-year calls and risks.
China Biodegradable Plastics 2026: PLA, PBAT, and the Capacity Showdown
A 2026 panoramic on the Chinese biodegradable-plastic industry: PLA and PBAT process routes, the standoff between 4.2 million tonnes of planned capacity and 36% utilisation, the Kingfa-Fengyuan-Hisun-NatureWorks-BASF map, single-use-plastic restrictions and capacity overhang, EU SUP and CBAM impact on exports.
China Specialty Paper 2026 — Decor Base, Food Packaging and the High-End Breakthrough
2026 deep research on China specialty paper: industry output ~5 mn t, top-two share ~50%; Xianhe 2024 revenue RMB 10.3 bn; Wuzhou H1 2025 revenue RMB 4.1 bn; Huawang decor base going global; Kane capacitor paper duopoly; EU PPWR + PFAS effective August 2026; 14 chapters on 2026-2030 global pathway.
China Semiconductor Test Equipment 2026: SoC ATE and Probe Station Localization Push - Market Size and Competitive Landscape Deep Research Report
2025 global semiconductor test equipment market reached about USD 9 billion; mainland China 32% (USD 2.9B) at 28% localization. Analog and power 62/56% localized; high-end SoC ATE only 4%, HBM test 2%. Changchuan, Hwatsing, Jingce, Xinyichang combined CNY 8B 2025 revenue. Report dissects 6 ATE sub-segments, 7 process moats, customer groups, capacity expansion, price cycle, export controls; gives 2026-2030 path to 50% localization.
China Industrial Aluminum Extrusion 2026: Dual-Engine Restructuring Driven by Automotive Lightweighting and Solar Module Frames
China industrial aluminum extrusion crossed 12.5M tons in 2025 (54% of total profile output), completing the inversion from construction-led to industrial-led. Solar frames 3.95M, NEV 1.4M, general 3.6M, rail body 480K. Under EU CBAM 2026, anti-dumping, export-rebate cut, and green-power push, leaders pivot to auto-structural and solar-frame engines. 14 chapters: billet, process, players, downstream, capacity, prices, policy, risks.
China Oil & Gas Drilling Equipment 2026 — The Dual Engine of Shale Frac Pumps and Overseas Rig Exports
China oil & gas drilling equipment 2026: covers land rigs, frac pumps, cementing, workover and downhole tools. Benchmarks Jereh, Baoji and Zhongman against Halliburton, Schlumberger, Baker Hughes and NOV. Electric frac, Middle East and Central Asia exports, price cycles, 3-5 year outlook.
China Industrial Heat Exchanger 2026: High-End Localization and Overseas Penetration of Plate, Shell-and-Tube and Microchannel
An in-depth research view of China's industrial heat exchanger market in 2026: plate, shell-and-tube, microchannel, plate-fin and air-cooler segments; localization milestones against Alfa Laval, Kelvion, SWEP, Tranter and Danfoss; capacity maps for Yuanda, Shuangliang, Sifang, Hongsheng and Yinlun; data-center liquid cooling, NEV thermal management, heat pumps and hydrogen as the new growth engines.
China Industrial Filters 2026: How Domestic Substitution Is Quietly Rewriting a List Long Dominated by Foreign Giants
China's industrial filter sector — long undervalued — enters 2026 with policy and domestic substitution dividends. The report walks through five product categories, seven process barriers, thirteen makers, two downstream groups, seven substitution cells, capacity expansion, pricing, China 7, Phase III fund and risks. Total market 40-45B yuan with domestic share rising to 55-60%.
China Ternary Precursor 2026 — Nickel-Cobalt-Manganese Integration and the Global Resource Race
2026 China ternary precursor: shipments 88 kt (84% global), CR3 76% (CNGR 33 + Huayou 18 + GEM 16). NCM811 processing fee at floor ¥8500/t; high-nickel single crystal + NCMA + solid-state adaptation drive premium. Indonesian HPAL Ni 45 kt, DRC cobalt + EOL recycling 380 kt; CBAM + IRA reshape global flows. 14 chapters.
Tides of White Oil: 2026 Deep-Dive Research Report on China's Lithium Carbonate Industry
In Nov 2022 China's battery-grade lithium carbonate spiked to RMB 600,000/t; 21 months later it collapsed to RMB 72,000 — an 88% drop. By June 2026 the price hovers around RMB 100,000. China produced 780 kt LCE of carbonate and 360 kt of hydroxide in 2025, over 60% of global supply. This report covers the upstream-midstream-downstream chain across 14 chapters.
China Industrial Pneumatic Components 2026 — Localization of Cylinders, Solenoid Valves, and Vacuum Equipment
An in-depth research report on China's industrial pneumatic components industry in 2026, covering cylinders, solenoid valves, vacuum equipment, and domestic substitution by AirTAC, SMC China, Festo, and Ningbo Jialing.
China's Prefab Steel Structure and Construction 2026 — Industrial Plants, Mega Venues, and Steel Bridges Reshaping the General-Contracting Tier
2026 China steel-structure and prefab-construction deep research: 132M-t output, 35.6% prefab share, CR10 9.4%; Honglu/Jinggong/Hangxiao/Southeast/Fuhuang/CRBC vs Nucor/Steel Dynamics/Tata/SSAB/Cleveland-Cliffs/ArcelorMittal Europe; fabs, lithium, data centres, EV assembly, cross-sea bridges, prefab housing, floating wind; CBAM + prefab plan + East-West Compute + BRI; 5-to-10-year consolidation window.
China Industrial Kiln and Furnace Equipment 2026: Cement, Glass, Ceramics, Metallurgy EPC and Overseas Expansion
This report maps China industrial kiln and furnace equipment in 2026 — cement, float glass, ceramic, EAF, semiconductor vacuum, and lithium-battery firing furnaces. It tracks the retreat of FLSmidth, KHD, Maerz, Vesuvius from China; the rise of Sinoma International, Triumph Group, Tangshan Hexiang, NHI, Beijing Lier, NAURA; and the structural surge of overseas EPC and new-energy furnace demand.
China Industrial Lubricants 2026: Great Wall and Kunlun Duopoly with Longpan Going Abroad
China consumed about 7.7 Mt of lubricants in 2025; Sinopec Great Wall and PetroChina Kunlun together hold about 38%, while Lubrizol, Infineum, Chevron Oronite and Afton still control over 91% of compound additives. This report dissects the 2025 market structure, API Groups I-V base oils, refining and blending, leading players, industrial and automotive categories, EV coolants, downstream factory identification, Longpan going abroad via Lubricos, capacity, pricing, policy and risk.
2026 China PCB Equipment Industry: Market Size & Localization Substitution
A research-institute report on China PCB equipment 2026: mechanical and laser drillers, LDI direct-imaging exposure, wet lines and AOI. Benchmarks Han's CNC, Dingtai Hi-Tech, Dongwei, Suzhou Tianzhun against Schmoll Maschinen, Hitachi ViaMechanics, Mitsubishi, Posalux, Orbotech, with a 2026–2030 outlook.
China Industrial Force Sensors 2026: The Hidden Champions Behind Weighing, Torque and Pressure
Comprehensive 2026 research on China's industrial force sensor industry: load cells, torque, pressure, 6-axis, dynamic piezoelectric, microbalance. 14 chapters covering RMB 22B China market, USD 10.5B global market, humanoid robot 6-axis ramp, COMAC C919/C929 + CJ-1000A high-end breakthrough, capacity expansion across Ningbo/Xi'an/Suzhou/Xiangyang/Beijing, OIML international recognition, price cycles, policy windfalls and six major risks.
2026 China Sewing Machinery Industry: Market Size & Competitive Landscape
In 2025 Vietnam overtook China as the largest apparel supplier to the US — yet the sewing machines stitching those garments still come from Taizhou. This report dissects China's sewing machinery industry: 170 years of migration (US–Japan–China), a strongly cyclical market and its export structure, the four survival paths of leading firms, four decades of the Taizhou cluster, the Zhuji embroidery-machine belt, the frontier of automated sewing, and our 2026–2030 outlook.
2026 China Surface Treatment Industry: Market Size & Competitive Landscape
The last stop for almost every industrial product is a plating tank, an anodizing line or a spray booth. Surface treatment never appears on the nameplate, yet it decides how long a product lasts. This report dissects the invisible industry: a RMB 180 billion plating services market, 40,000+ companies, some 160 centralized parks, two decades of environmental consolidation, the localization battle in chemistry, the copper foil bust, semiconductor plating growth, and a 2026-2030 outlook.
2026 China Electric Motor Industry: Market Size & Competitive Landscape
Everything that spins hides an electric motor, yet no consumer can name a motor brand. This report dissects the heart of industry: the volume-down-value-up shift since the 2021 output peak, high-efficiency motor output rising from 39% to 73% in three years, WEG overtaking ABB while Nidec exits EV traction, 7.76 million EV drive units and their profit squeeze, humanoid-robot hype versus a RMB 209M frameless-motor market, and a 2026-2030 outlook.
2026 China High-Temperature Superconductor Industry: Market Size & Competitive Landscape
Superconductivity is over 110 years old, yet China's entire HTS tape market sells only a few hundred million yuan a year. Now fusion brings real orders: one compact tokamak consumes some 10,000 km of REBCO tape. This report dissects the business of selling certainty to a dream: one of the world's only two kilometer-scale tape makers in Shanghai, localization of substrates, targets and equipment, the LTS/HTS accounting traps, and a 2026-2030 outlook set by the fusion calendar.